Your own mobile money.
Your brand. Live in weeks.
PesaBridge gives banks, telcos, fintechs and SACCOs everything a national-scale mobile money wallet needs: customer, agent and merchant apps, USSD, prompt-to-pay and an open API, all running on a double-entry ledger you own.
- Double-entry ledger
- KYC and AML built in
- Android and iOS · USSD · Web · API
Made in Africa, for Africa — and ready for the world.
- 190+ countries
- 180+ currencies
- 12 languages
- Every mobile network
Choose a product
Three products. Take one, or all three.
Mobile money, international remittance and a payment gateway. Each runs on its own with its own price, and together they share one ledger and one back office.
White label: each product runs under your name, logo and colours. Your customers see your brand, not ours.
Two products: 15% off the setup and the monthly fees. All three: 25% off. See the prices
The whole platform
Everything a mobile money business runs on
Wallets, cash, merchants and payouts are only what customers see. Underneath sits the machinery an operator needs on day one: a balanced ledger, an agent network, compliance, back office and the rails to the outside world.
New
What's new in the platform
Added across the three products, and ready to try in the demo.
The customer app
Every way people move money, one tap away.
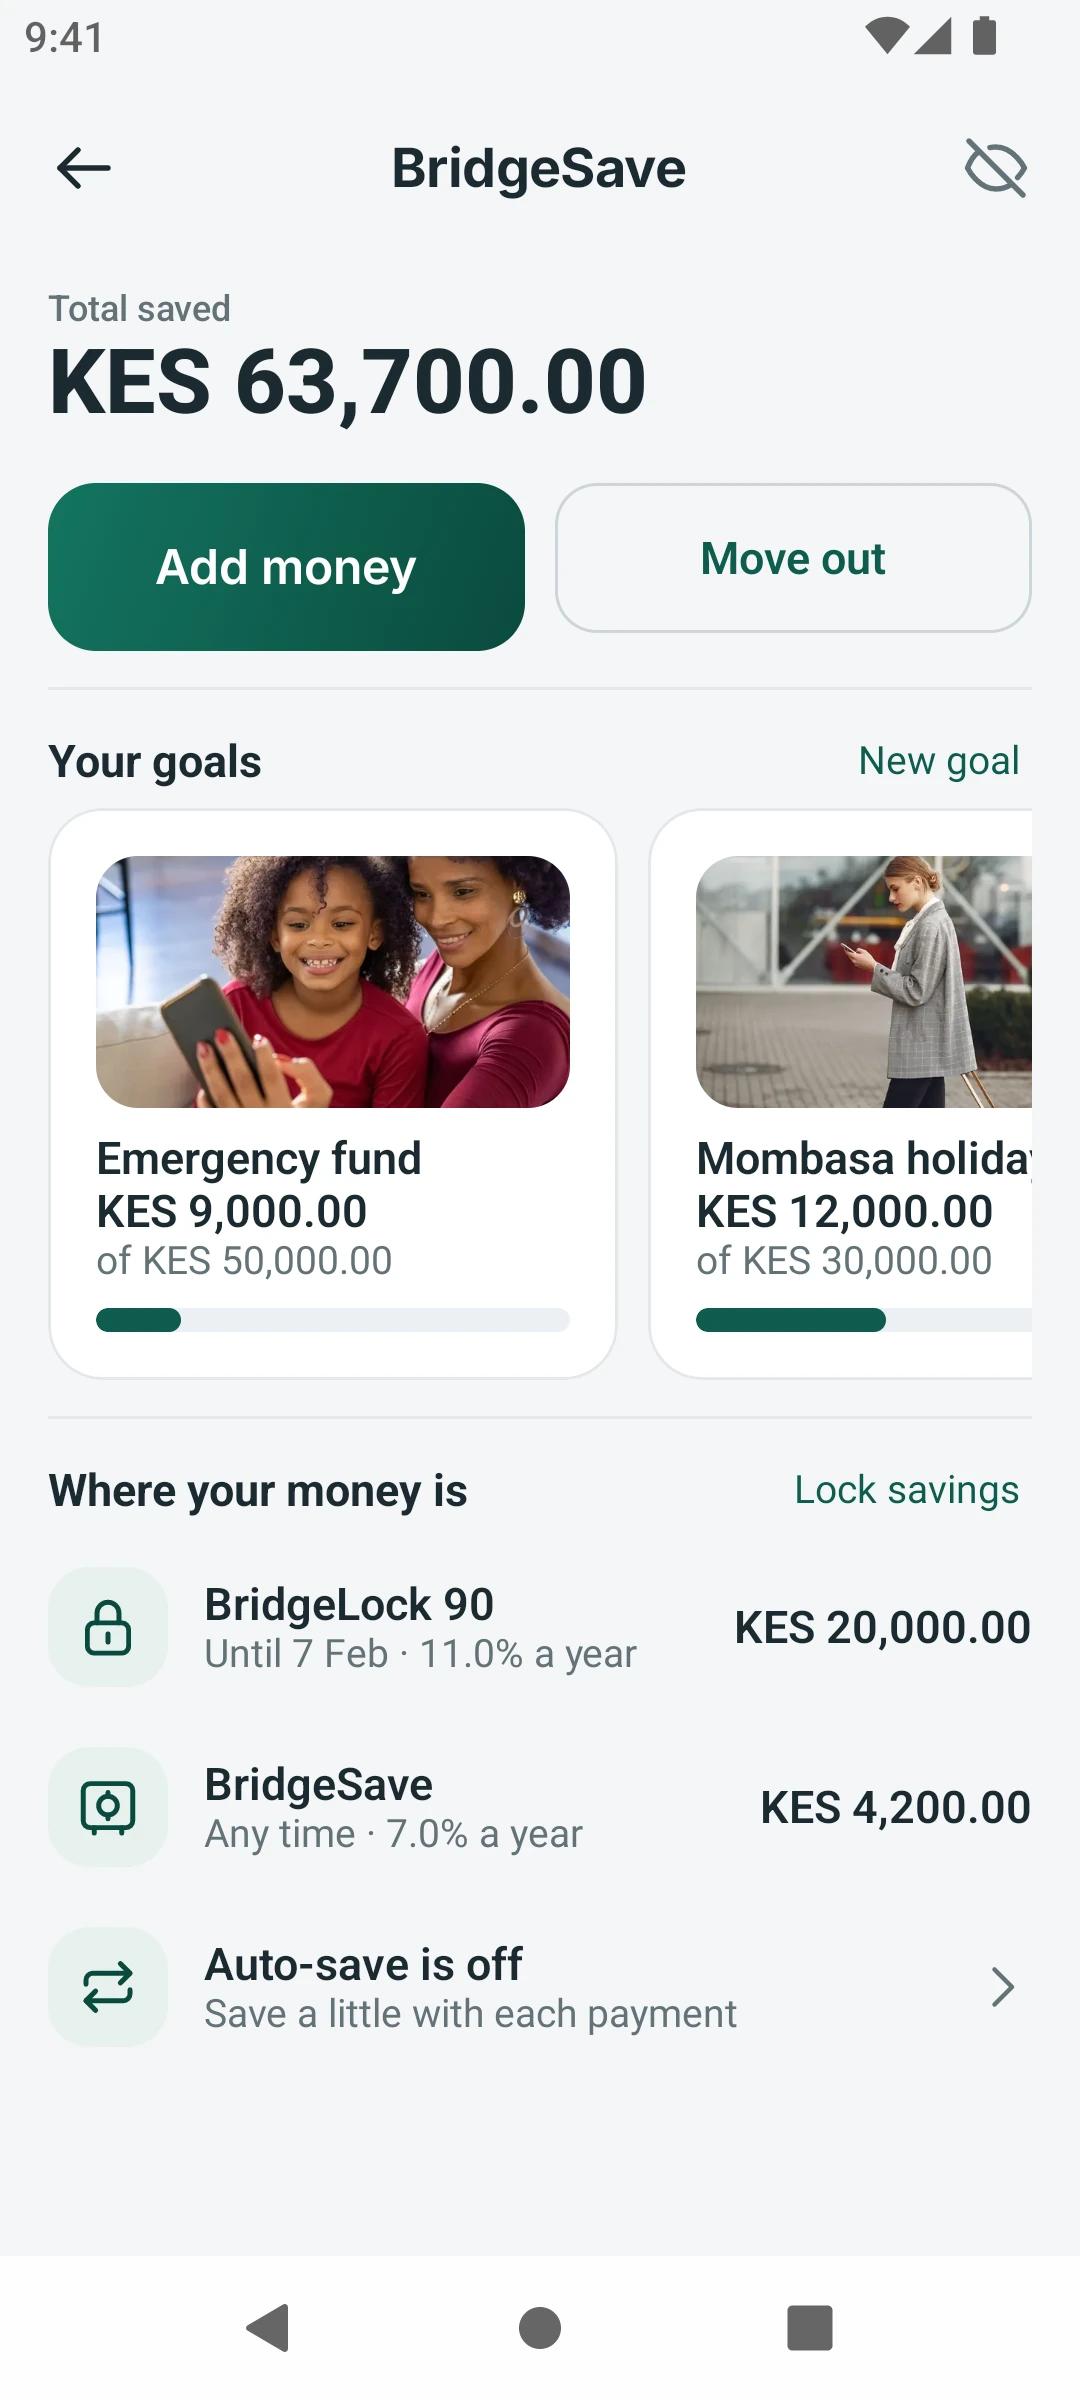
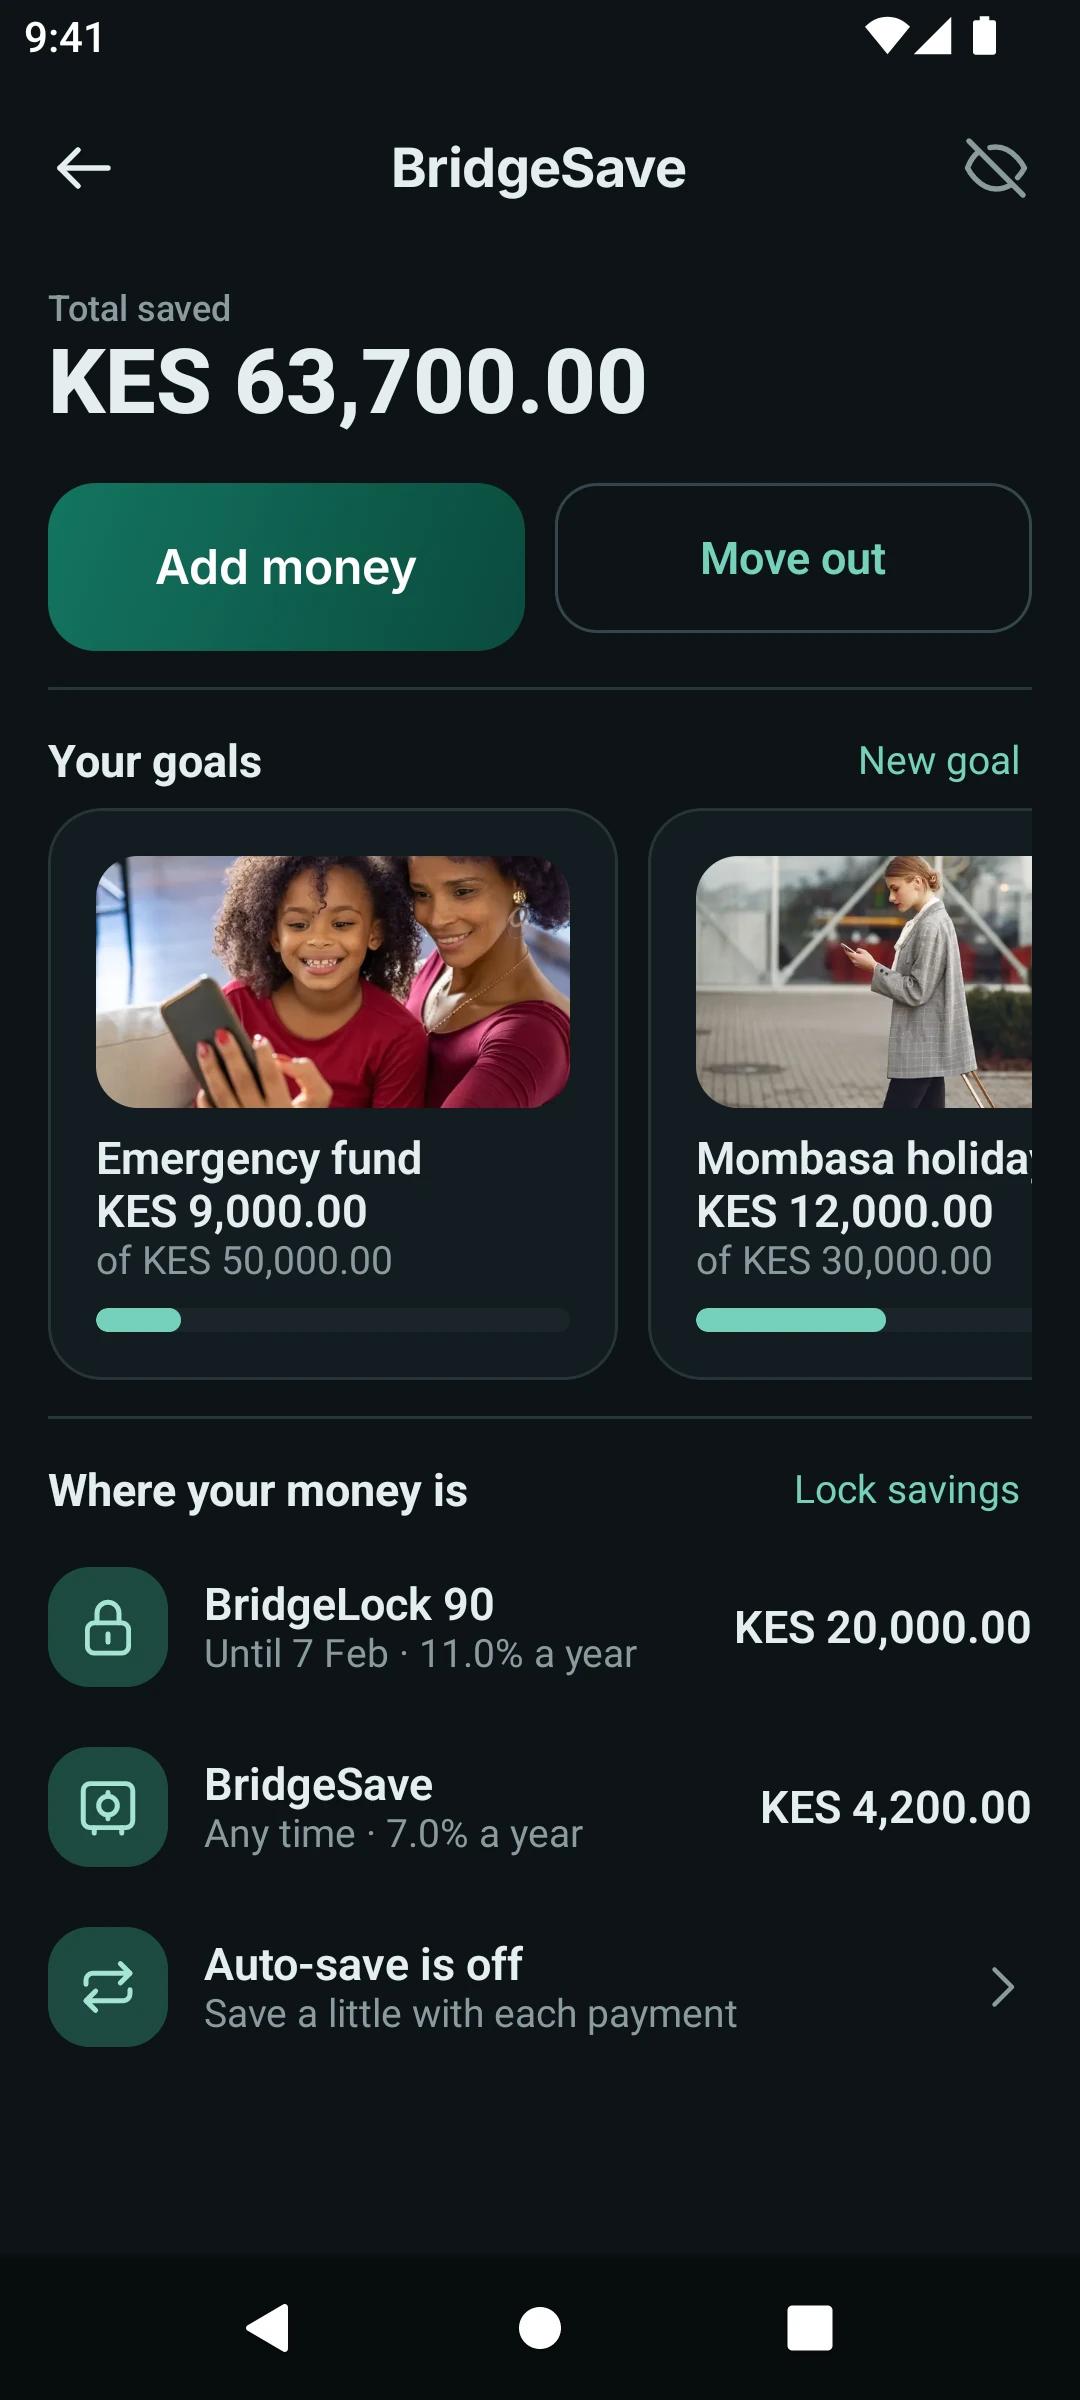
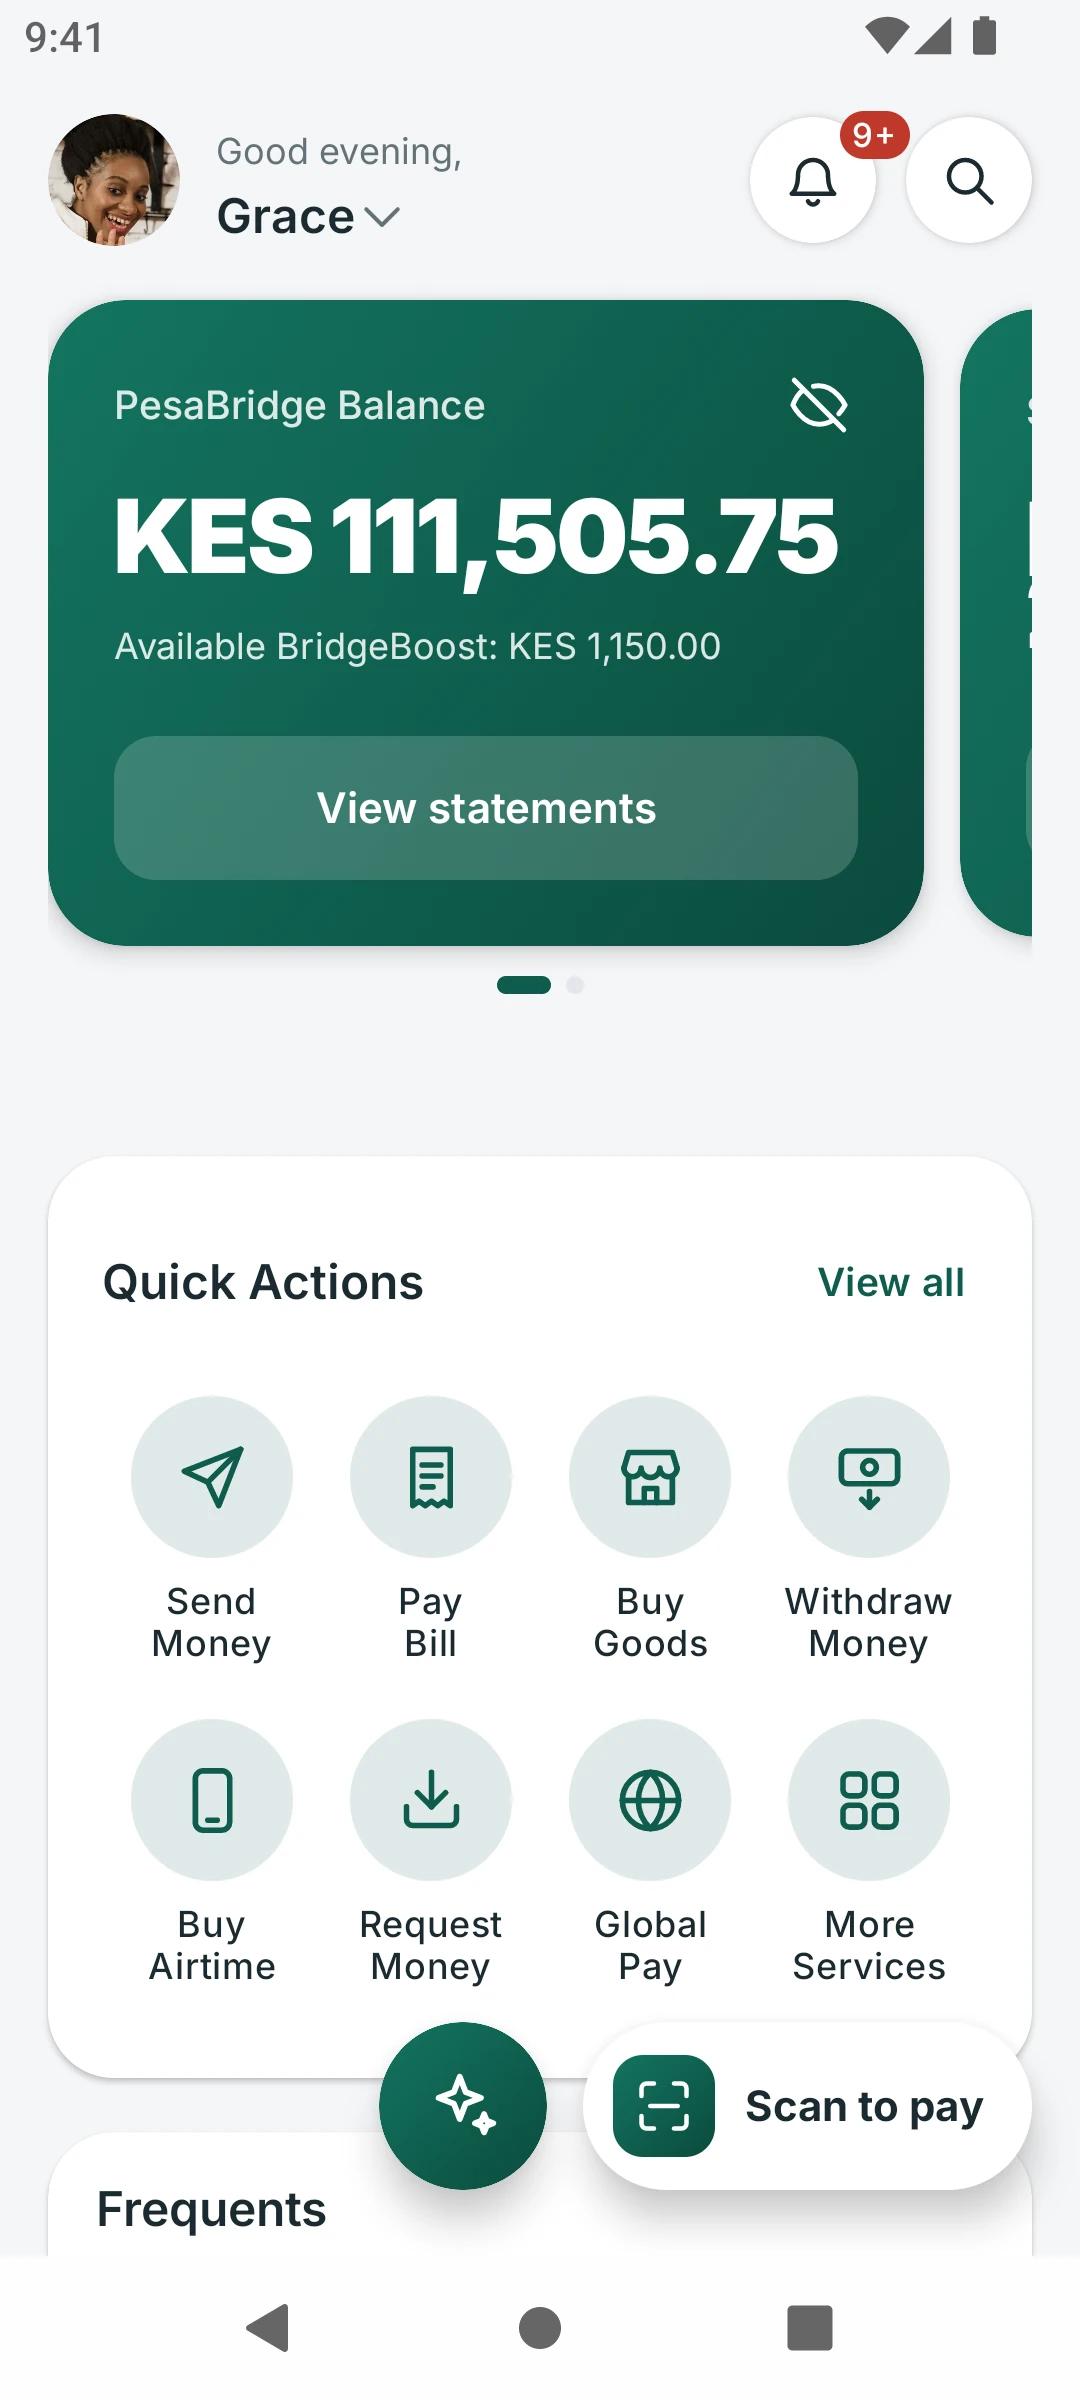
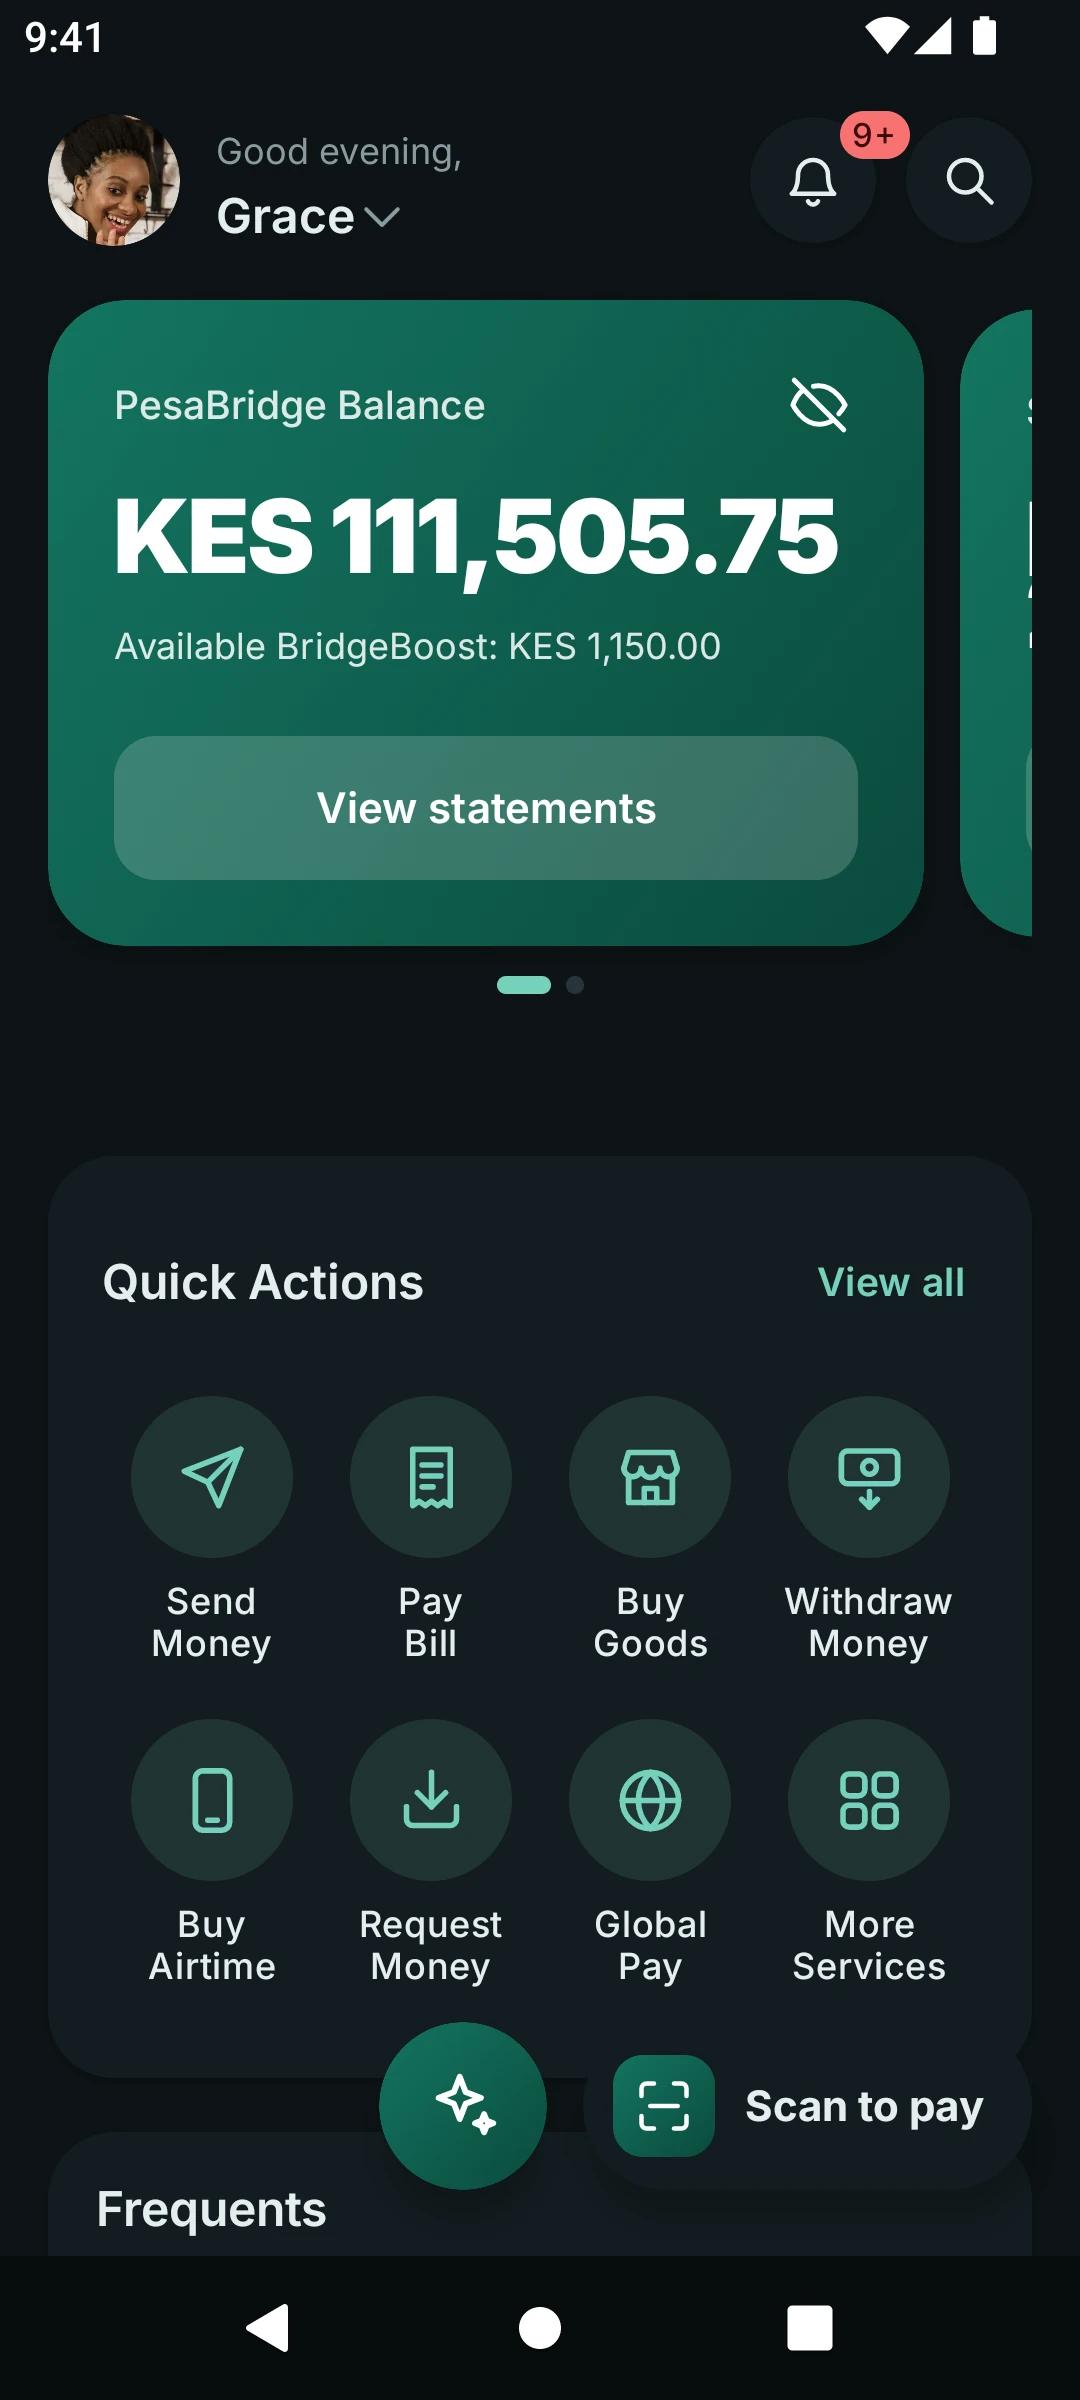
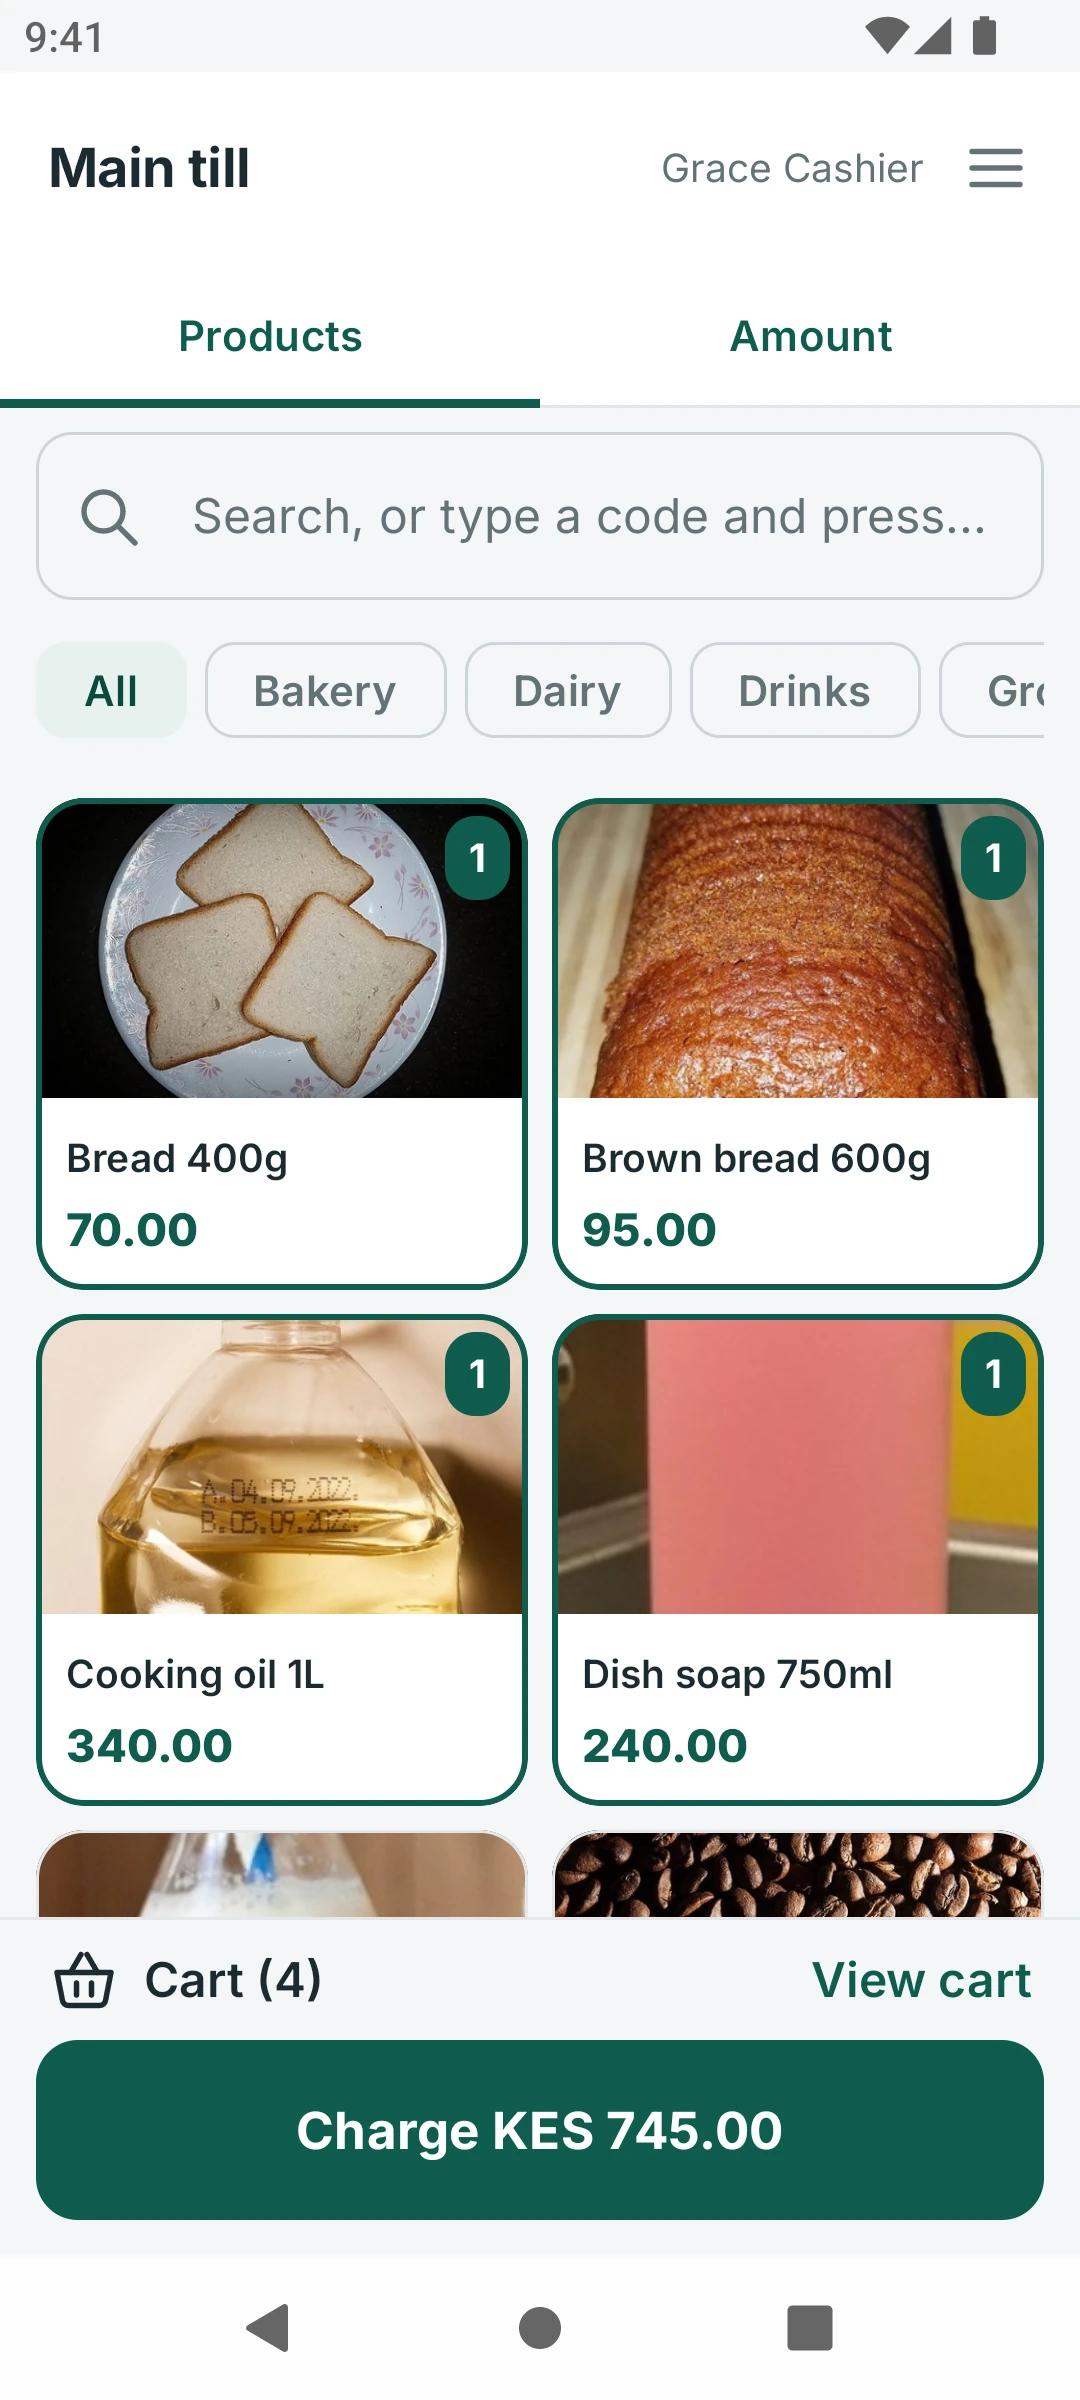
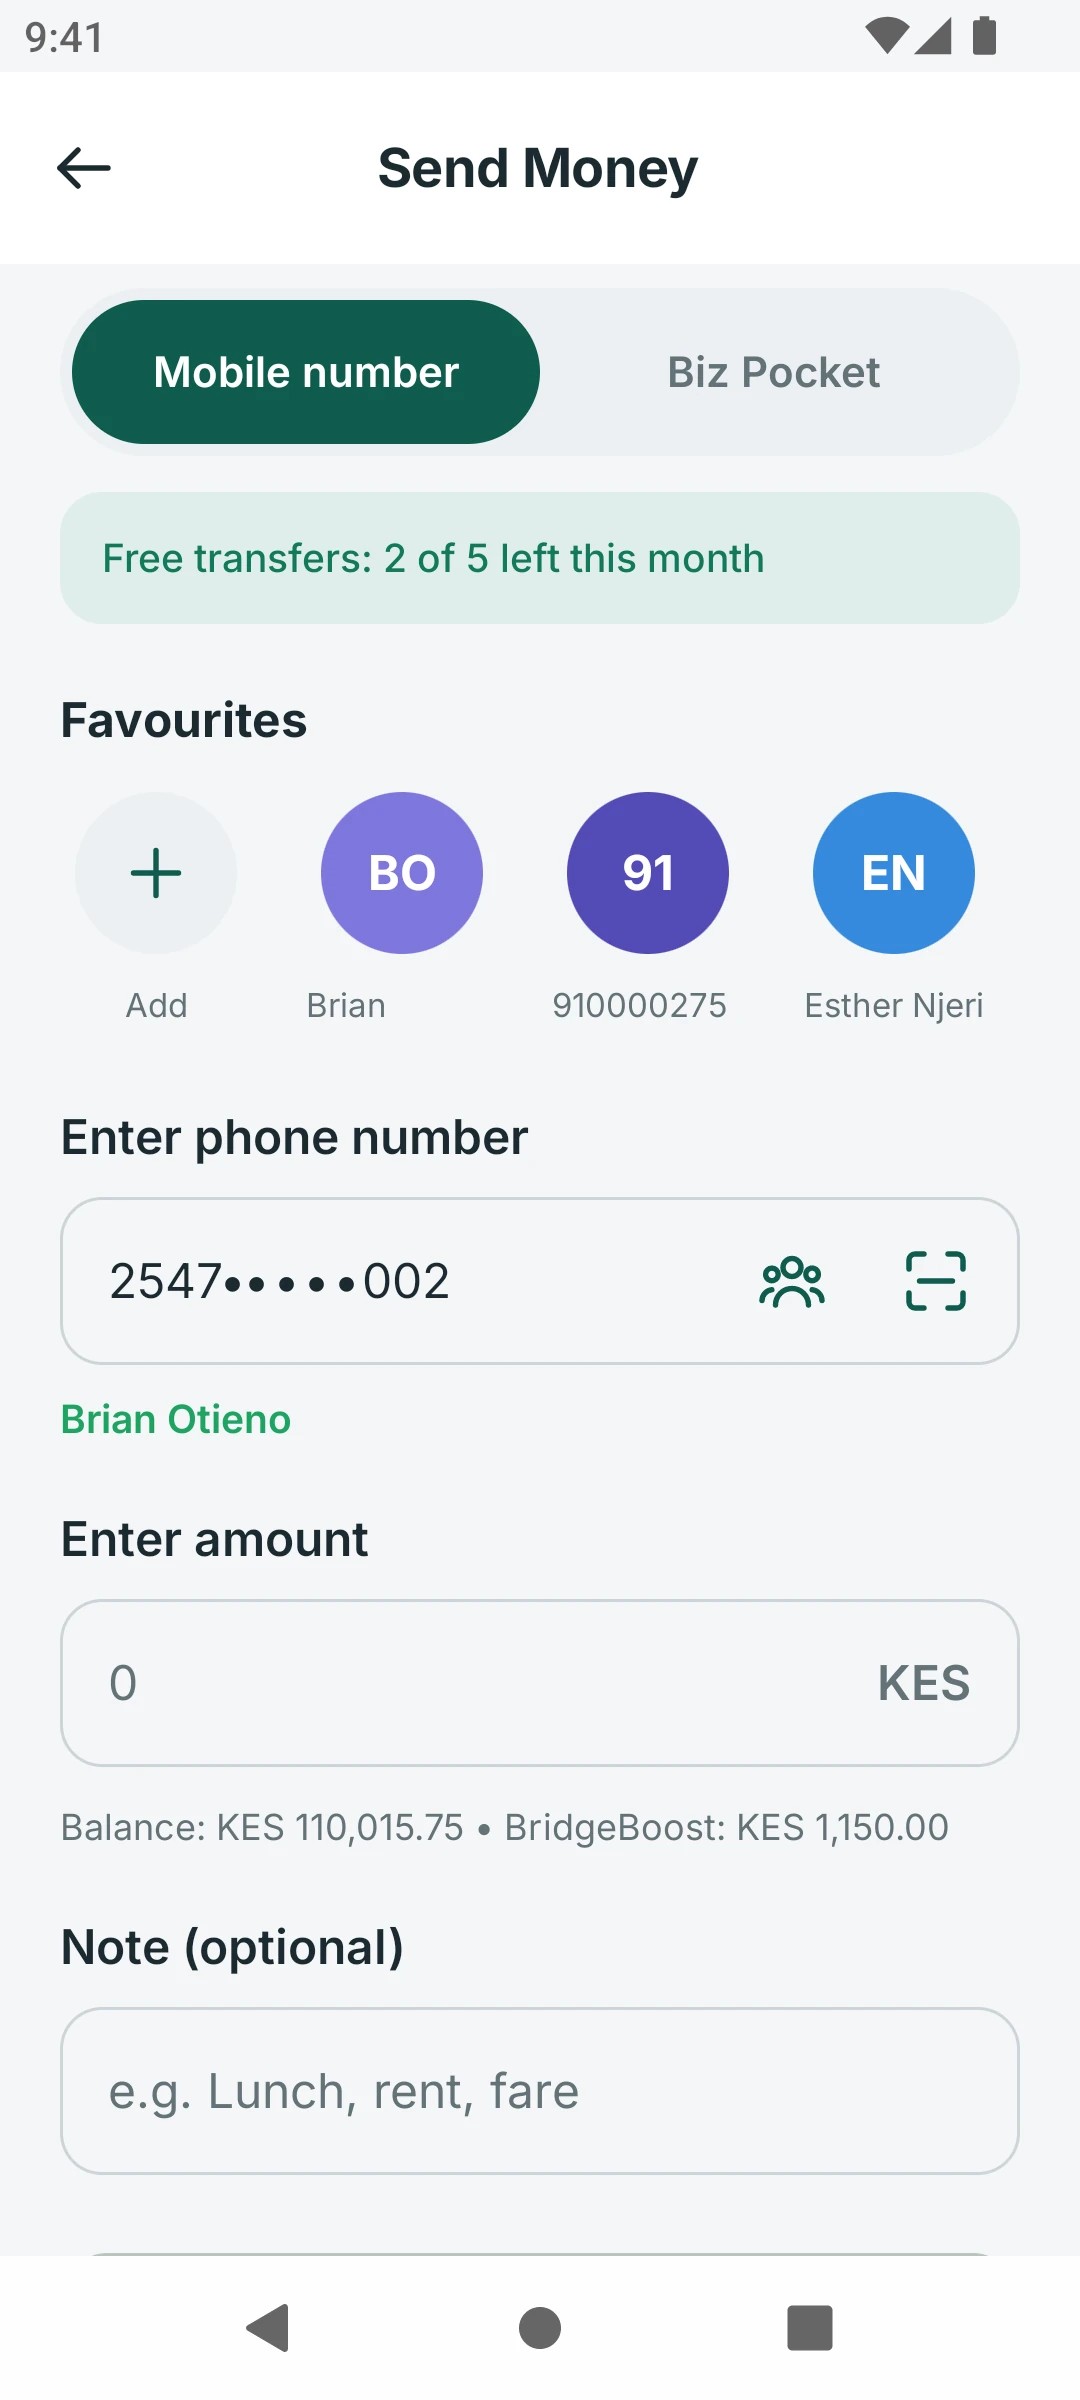
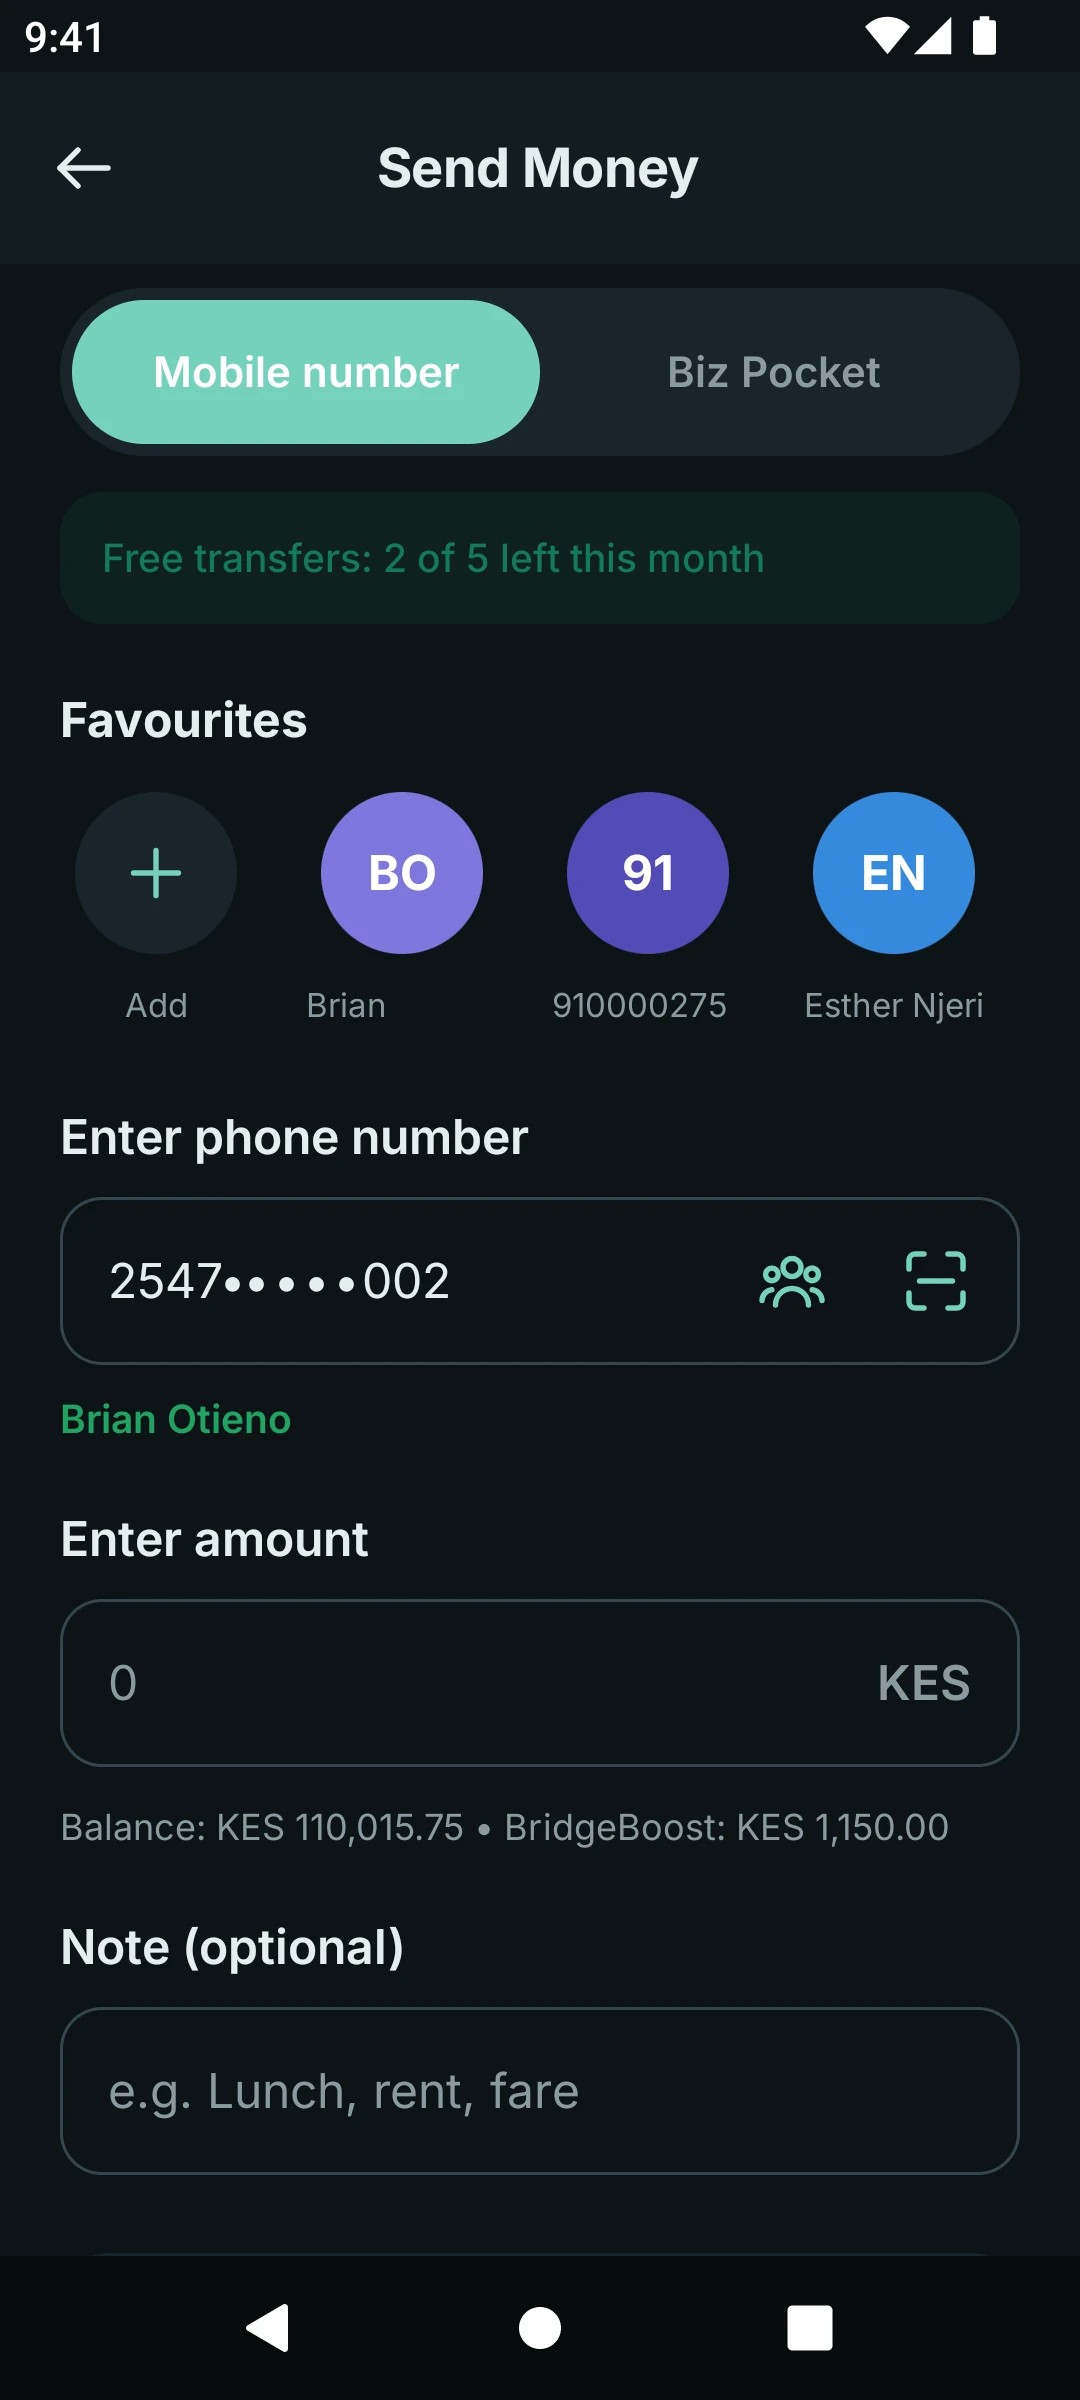
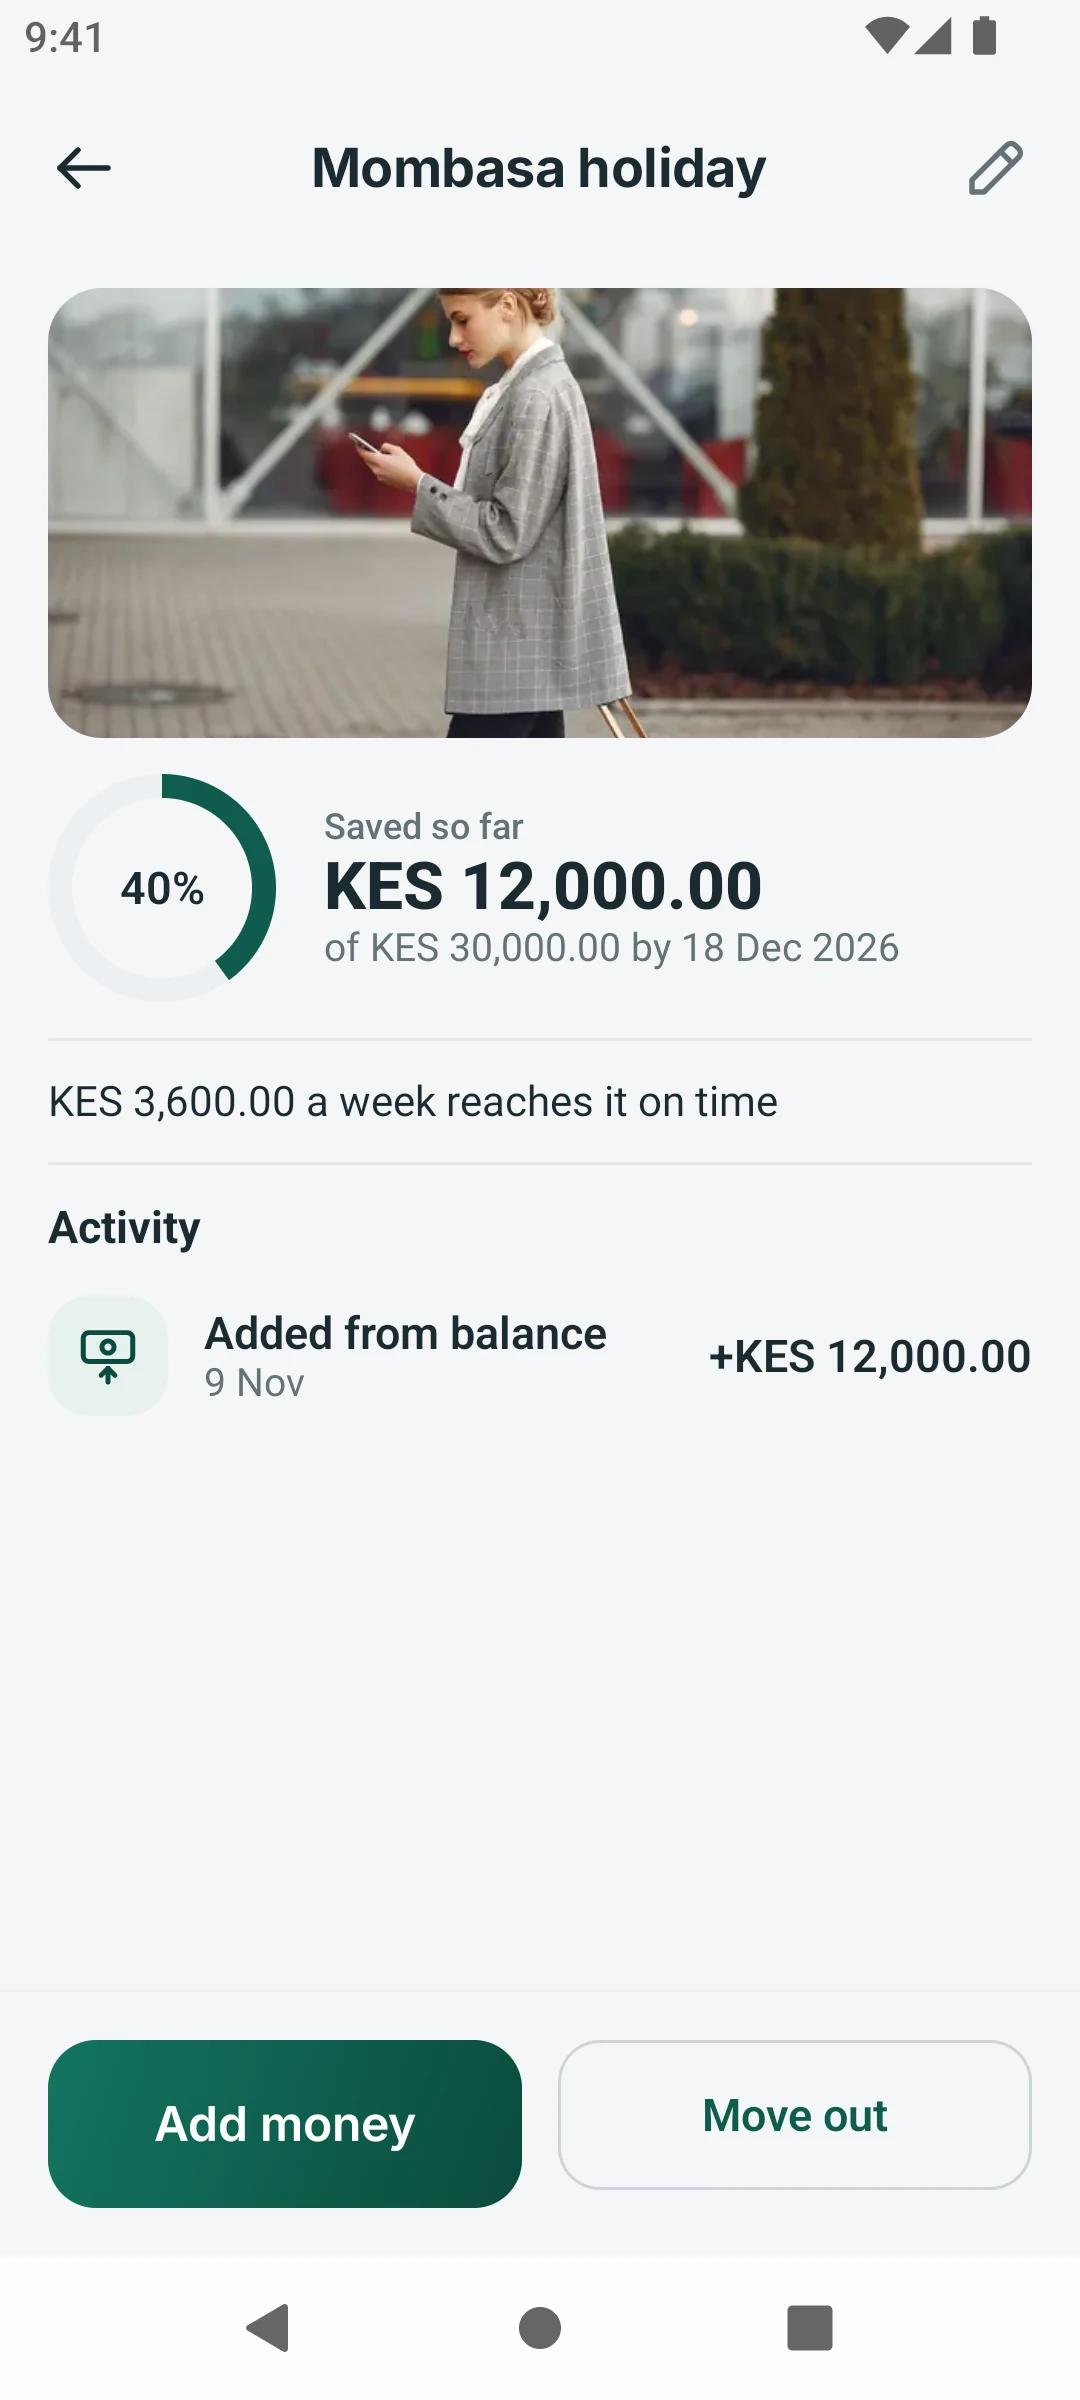
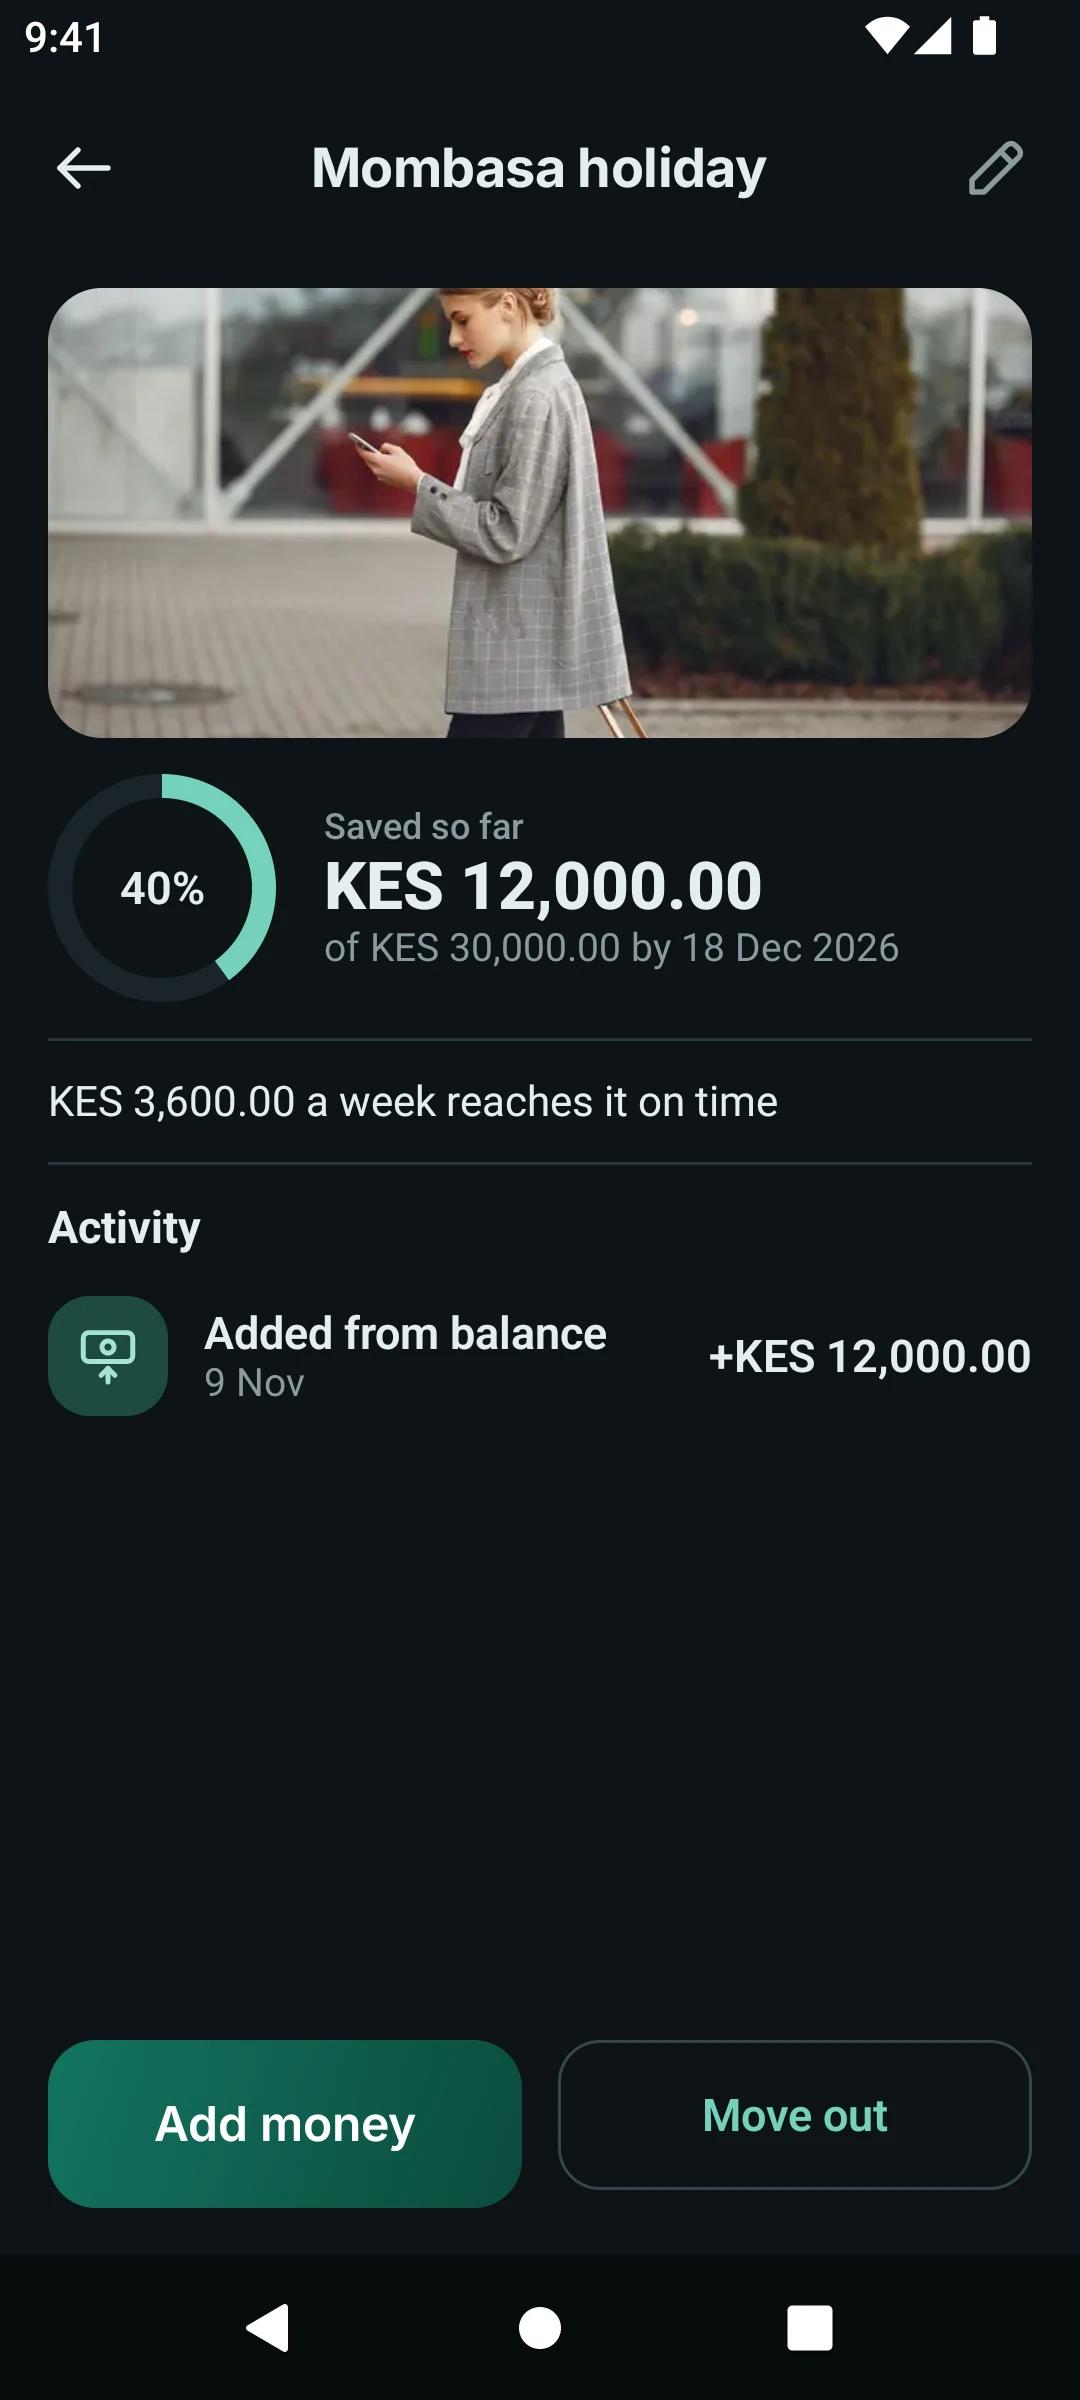
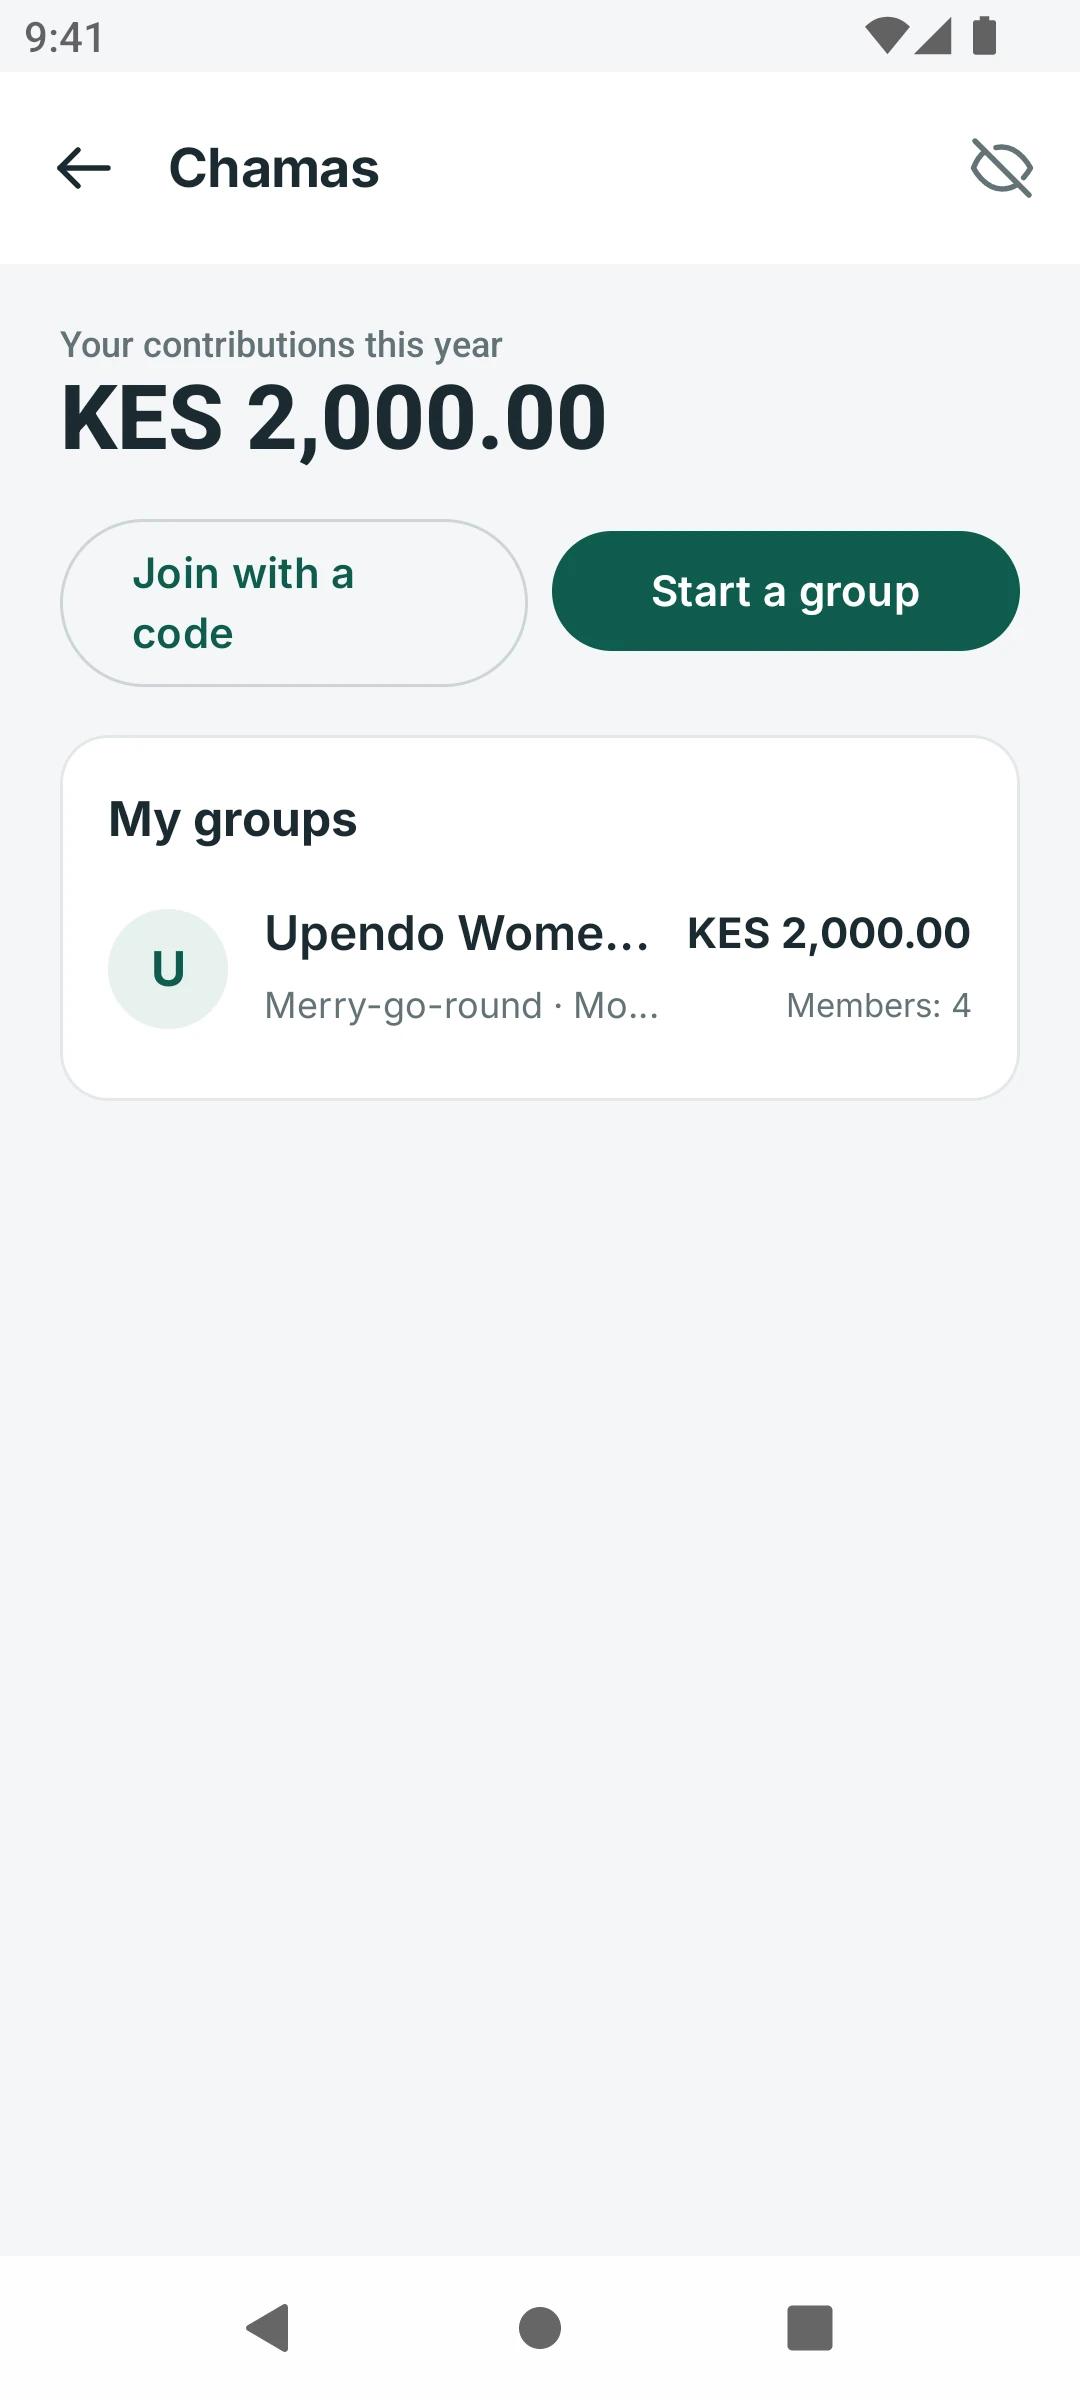
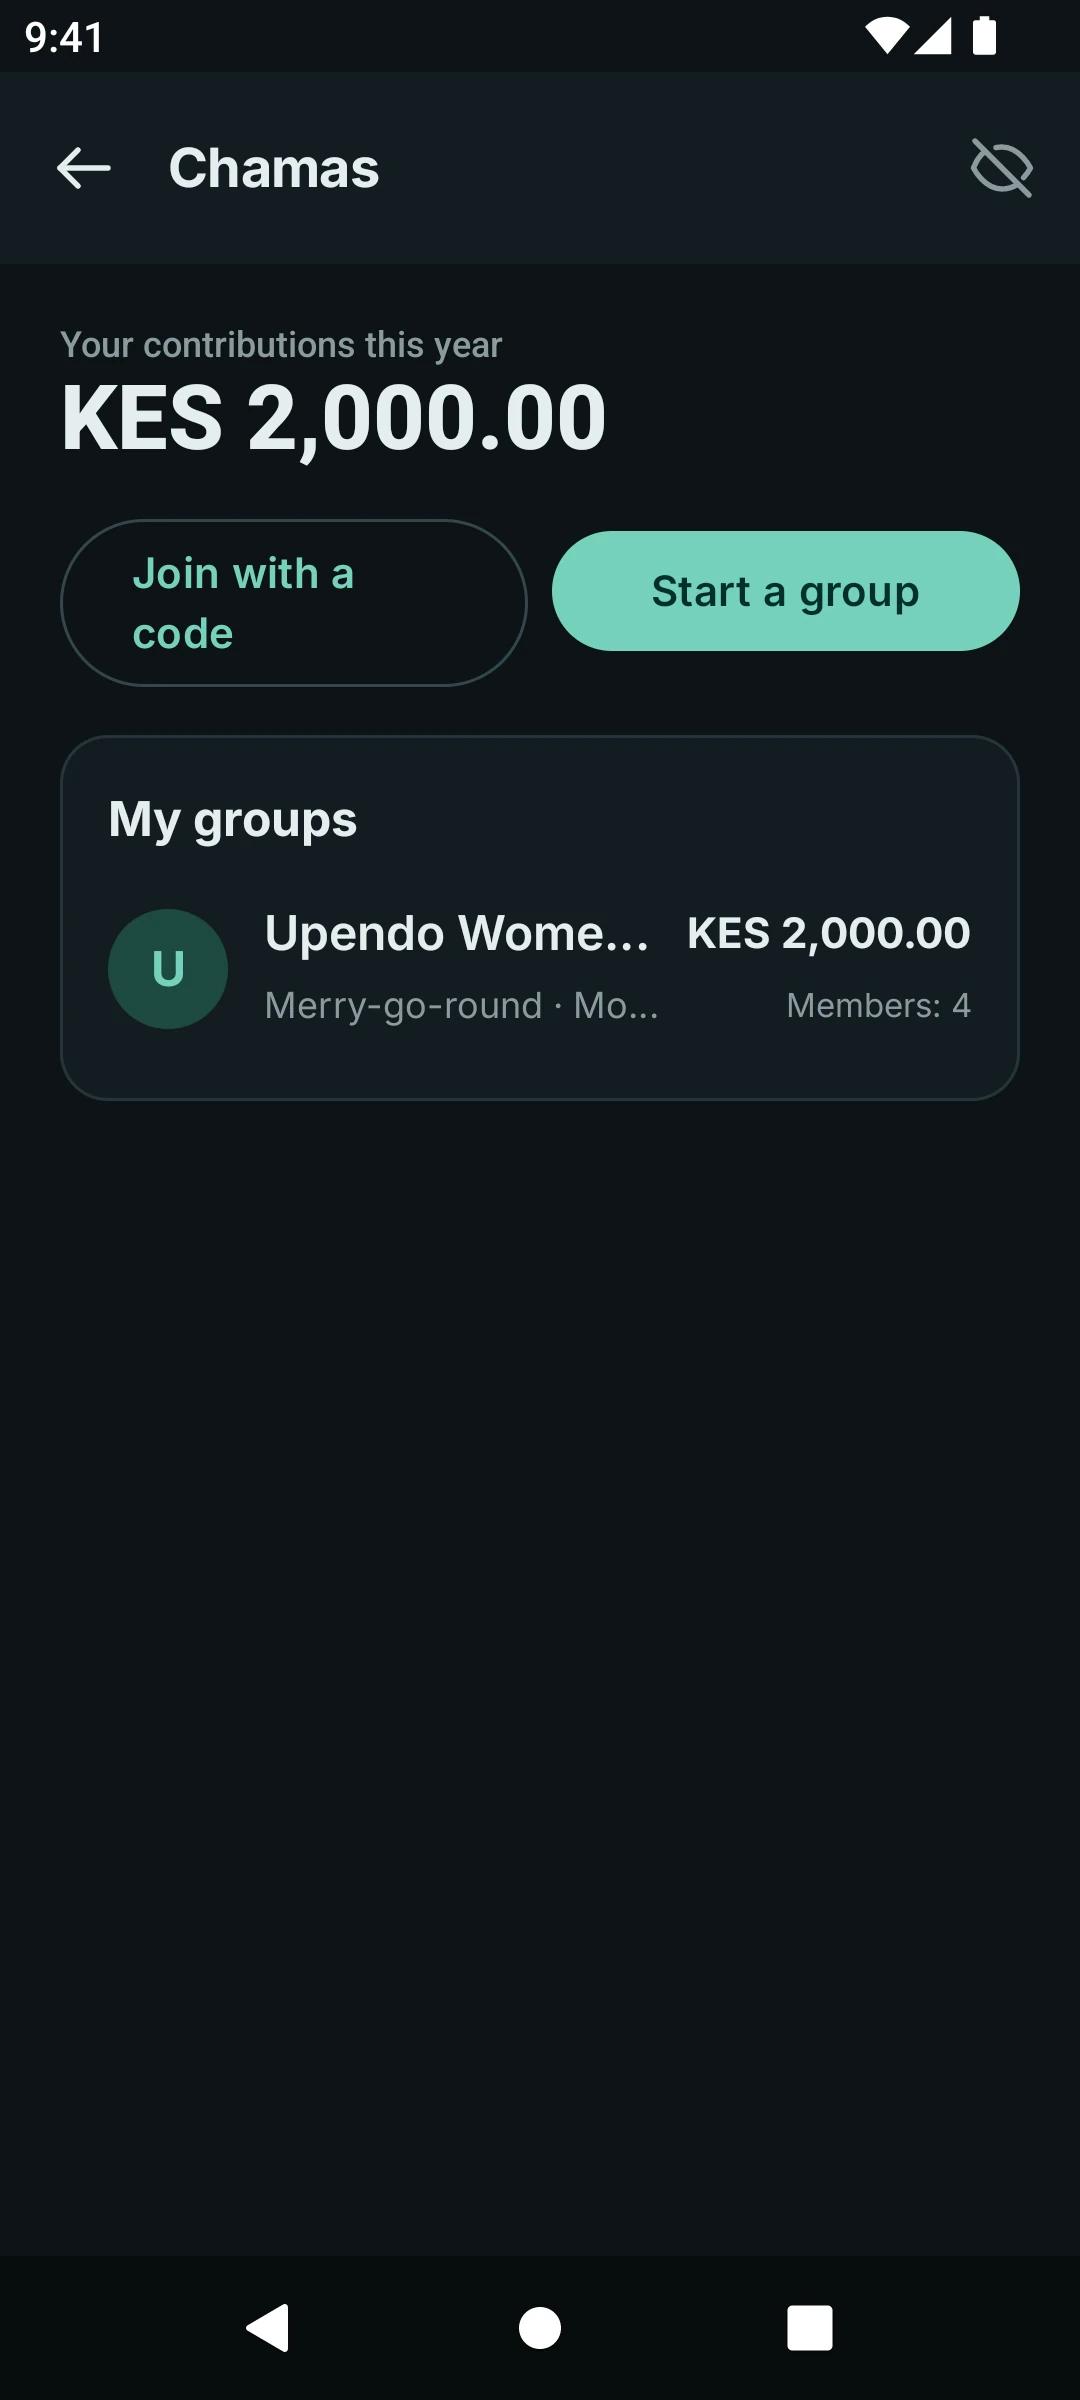
These are real screens from the PesaBridge app, not mock-ups. Your customers get all of it under your name and colours.
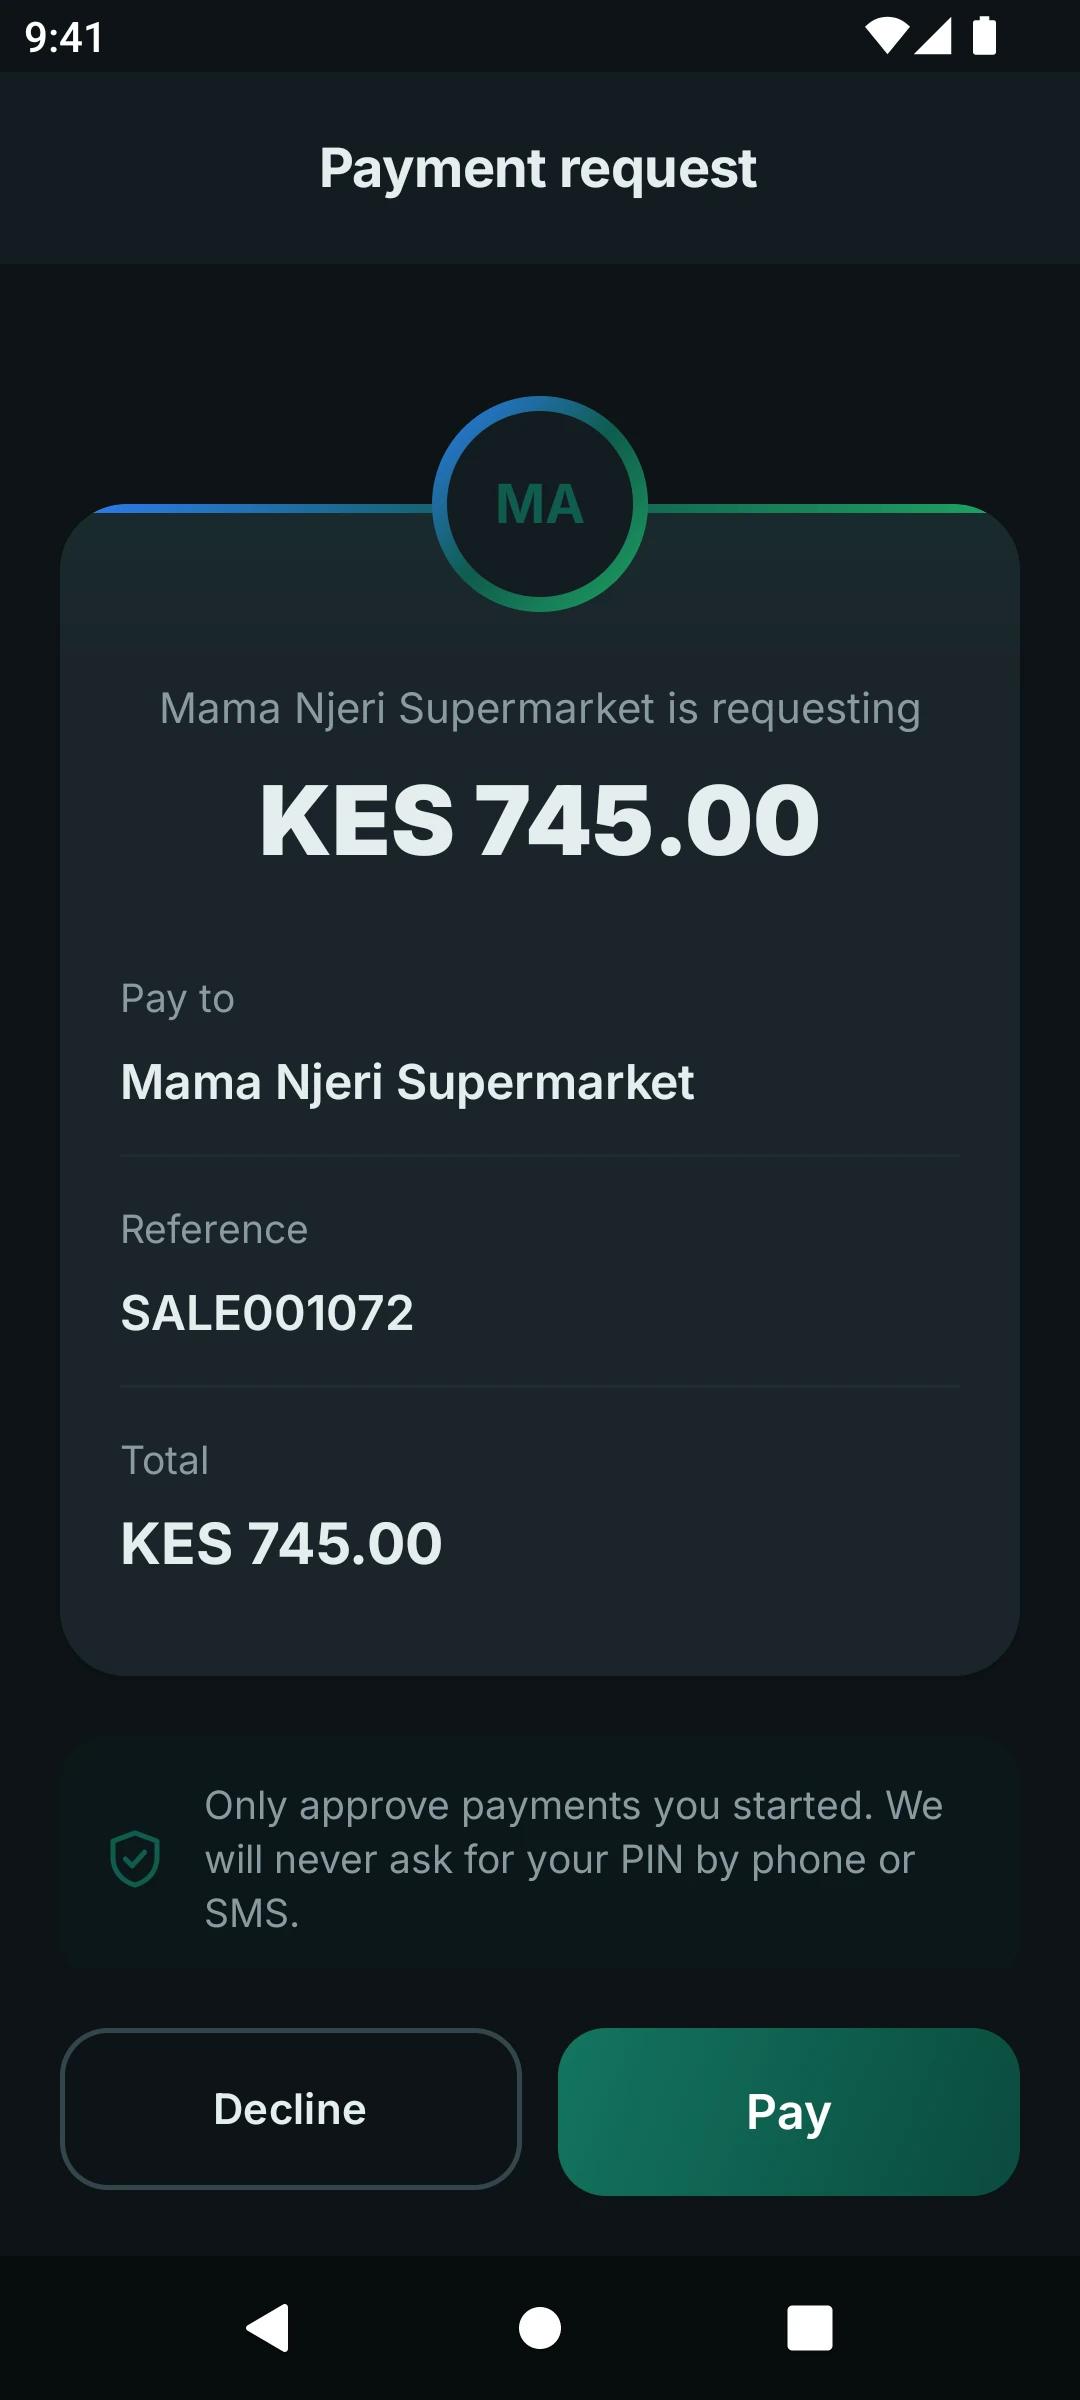
Prompt-to-pay
Request. Approve. Paid.
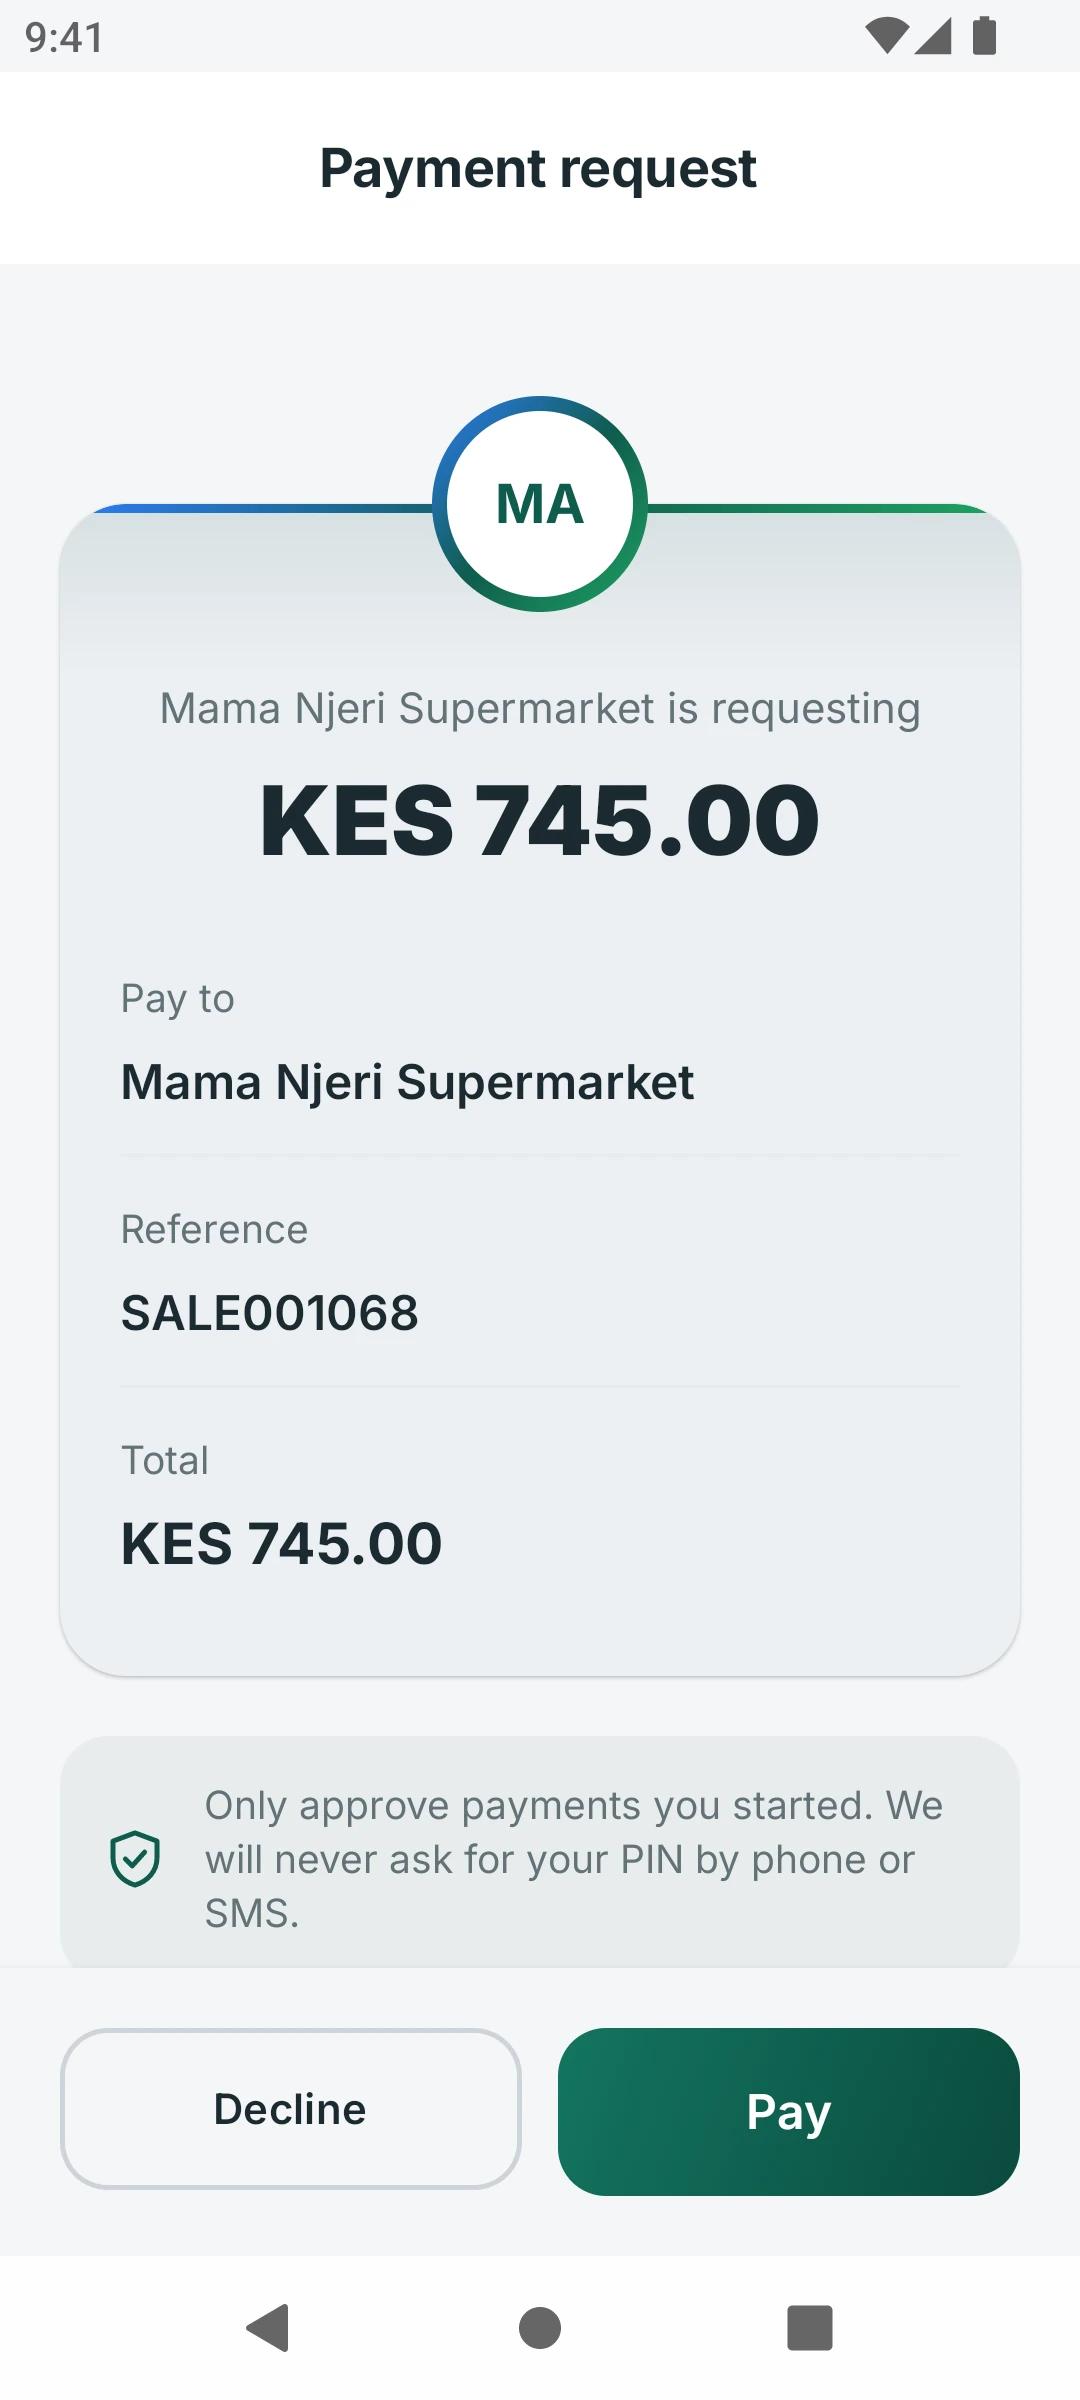
The checkout customers already trust, built into every till and available to your partners through the API.
- 1
The merchant requests
Enter the customer's number and amount in the Business app, a POS, or your own system through the API.
- 2
The customer approves
A full-screen payment request opens in their wallet showing who is asking and why. They approve with their PIN and get a receipt at once.
- 3
Both sides settle instantly
The ledger posts balanced entries, the customer gets a receipt, the till is notified and a signed webhook tells your system.
Everyday Africa
Built for the way people really pay.
Market stalls, boda rides, school fees and money home to family. Your wallet has to fit real life, on any phone, on any network.
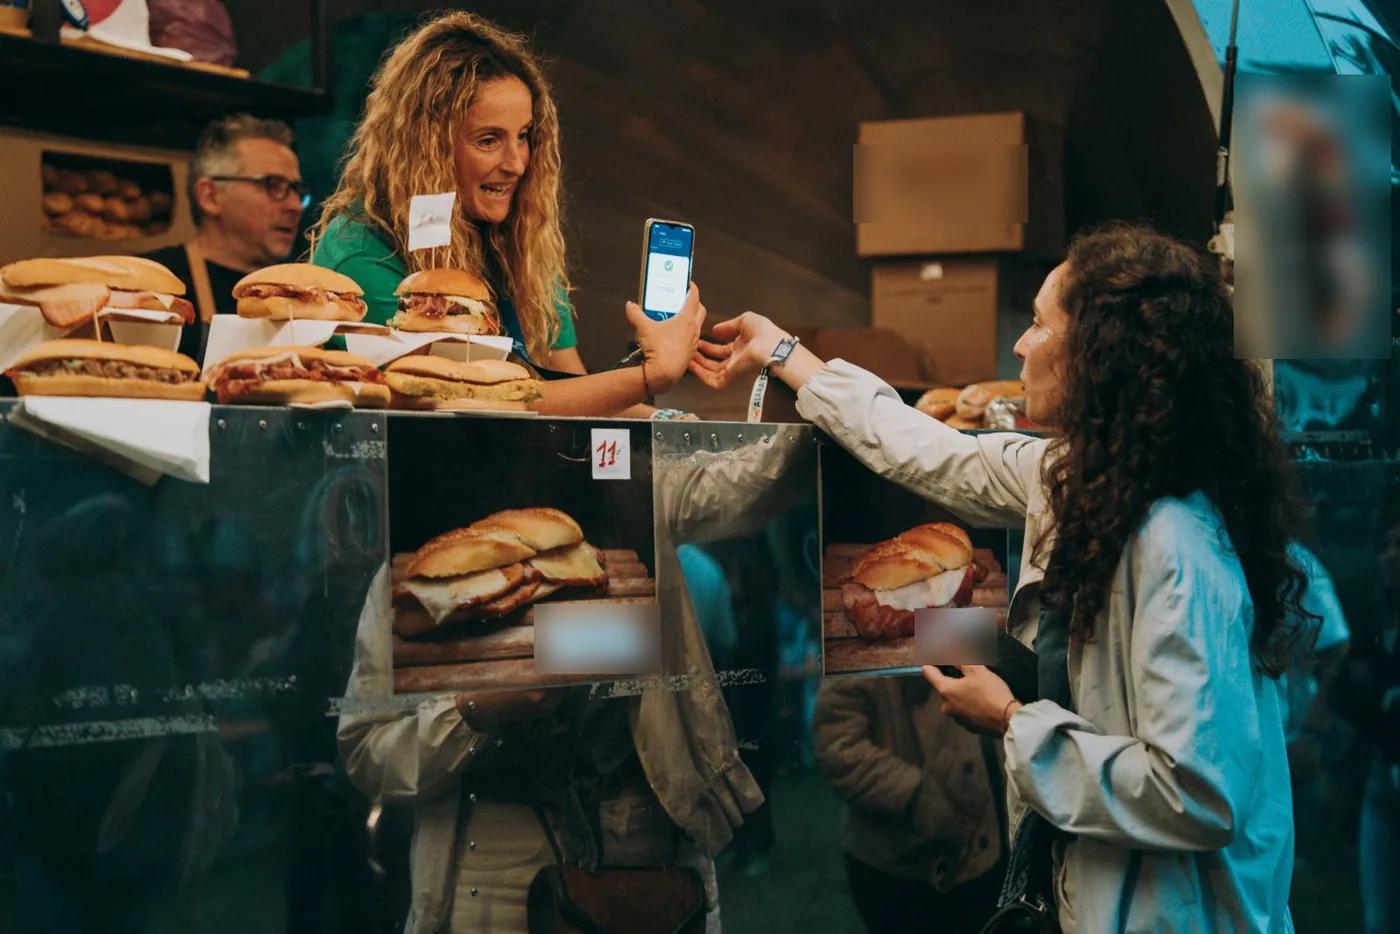
Customers pay the stall with a prompt or a QR code, and the money is ready to spend straight away.
Riders get paid per trip, straight to the wallet.
Money home in seconds, across borders.
Know the day's takings from anywhere, sale by sale.
Save, borrow and pay bills from one wallet.
For merchants
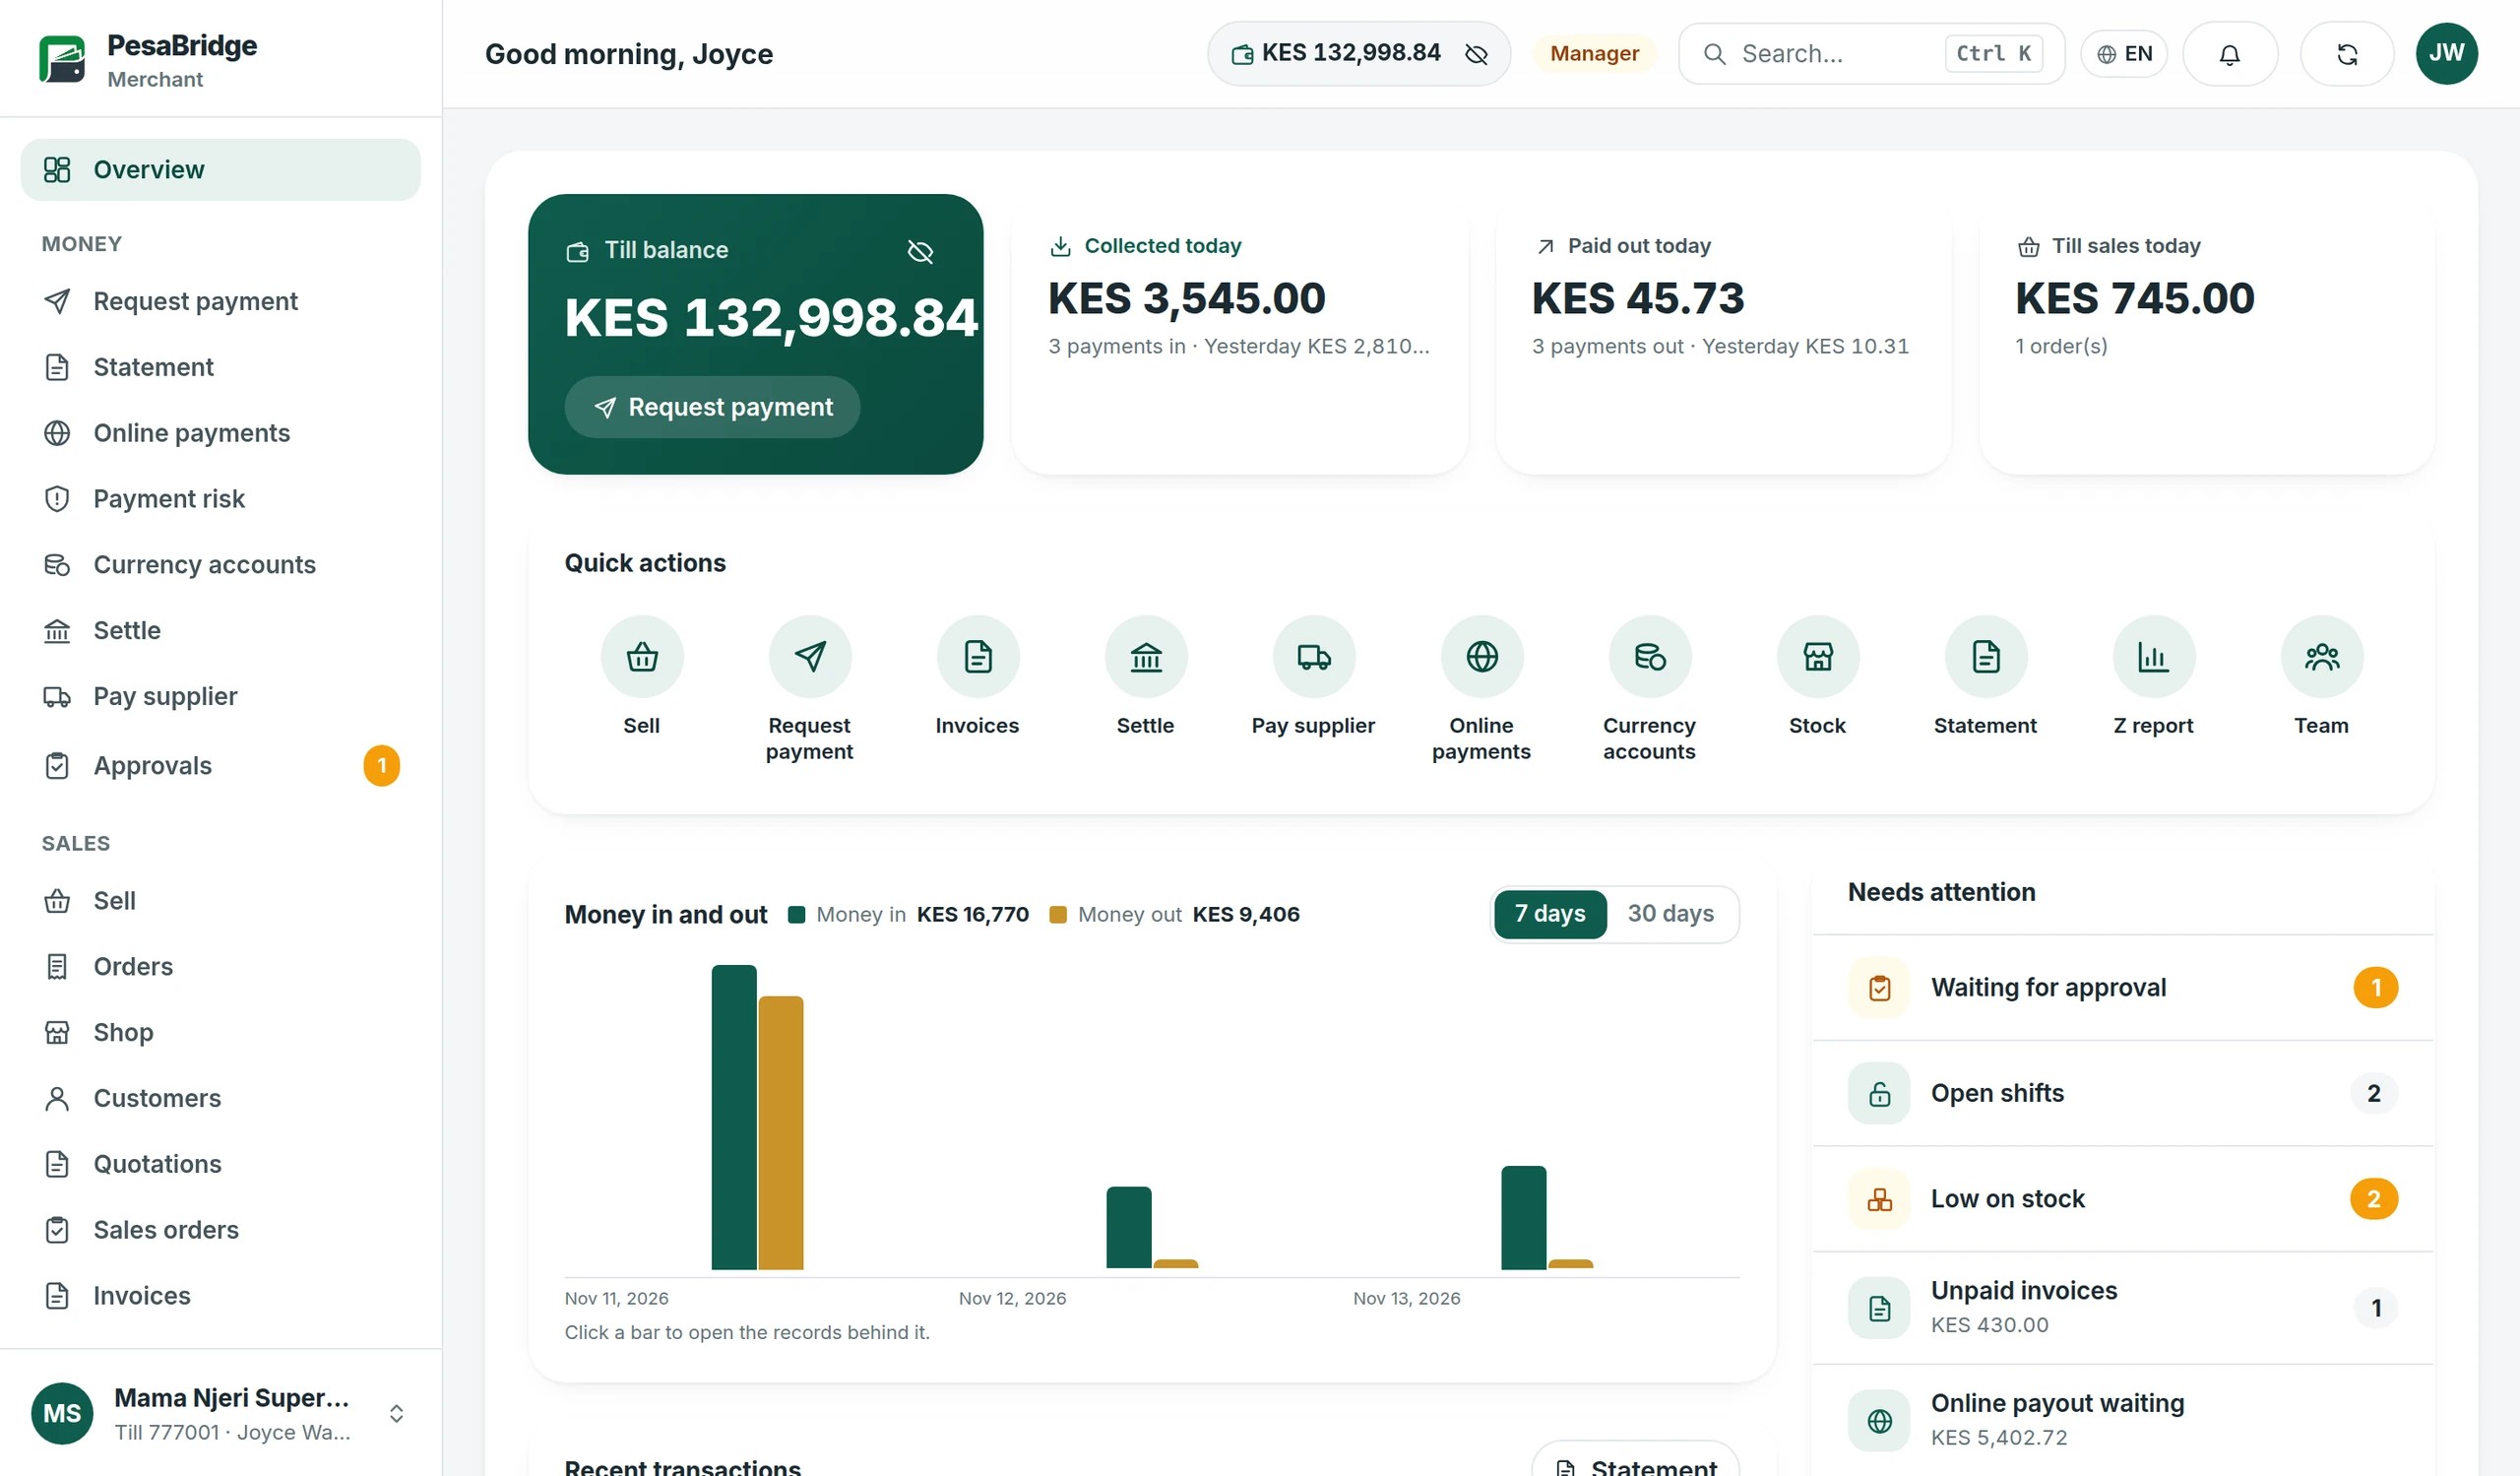
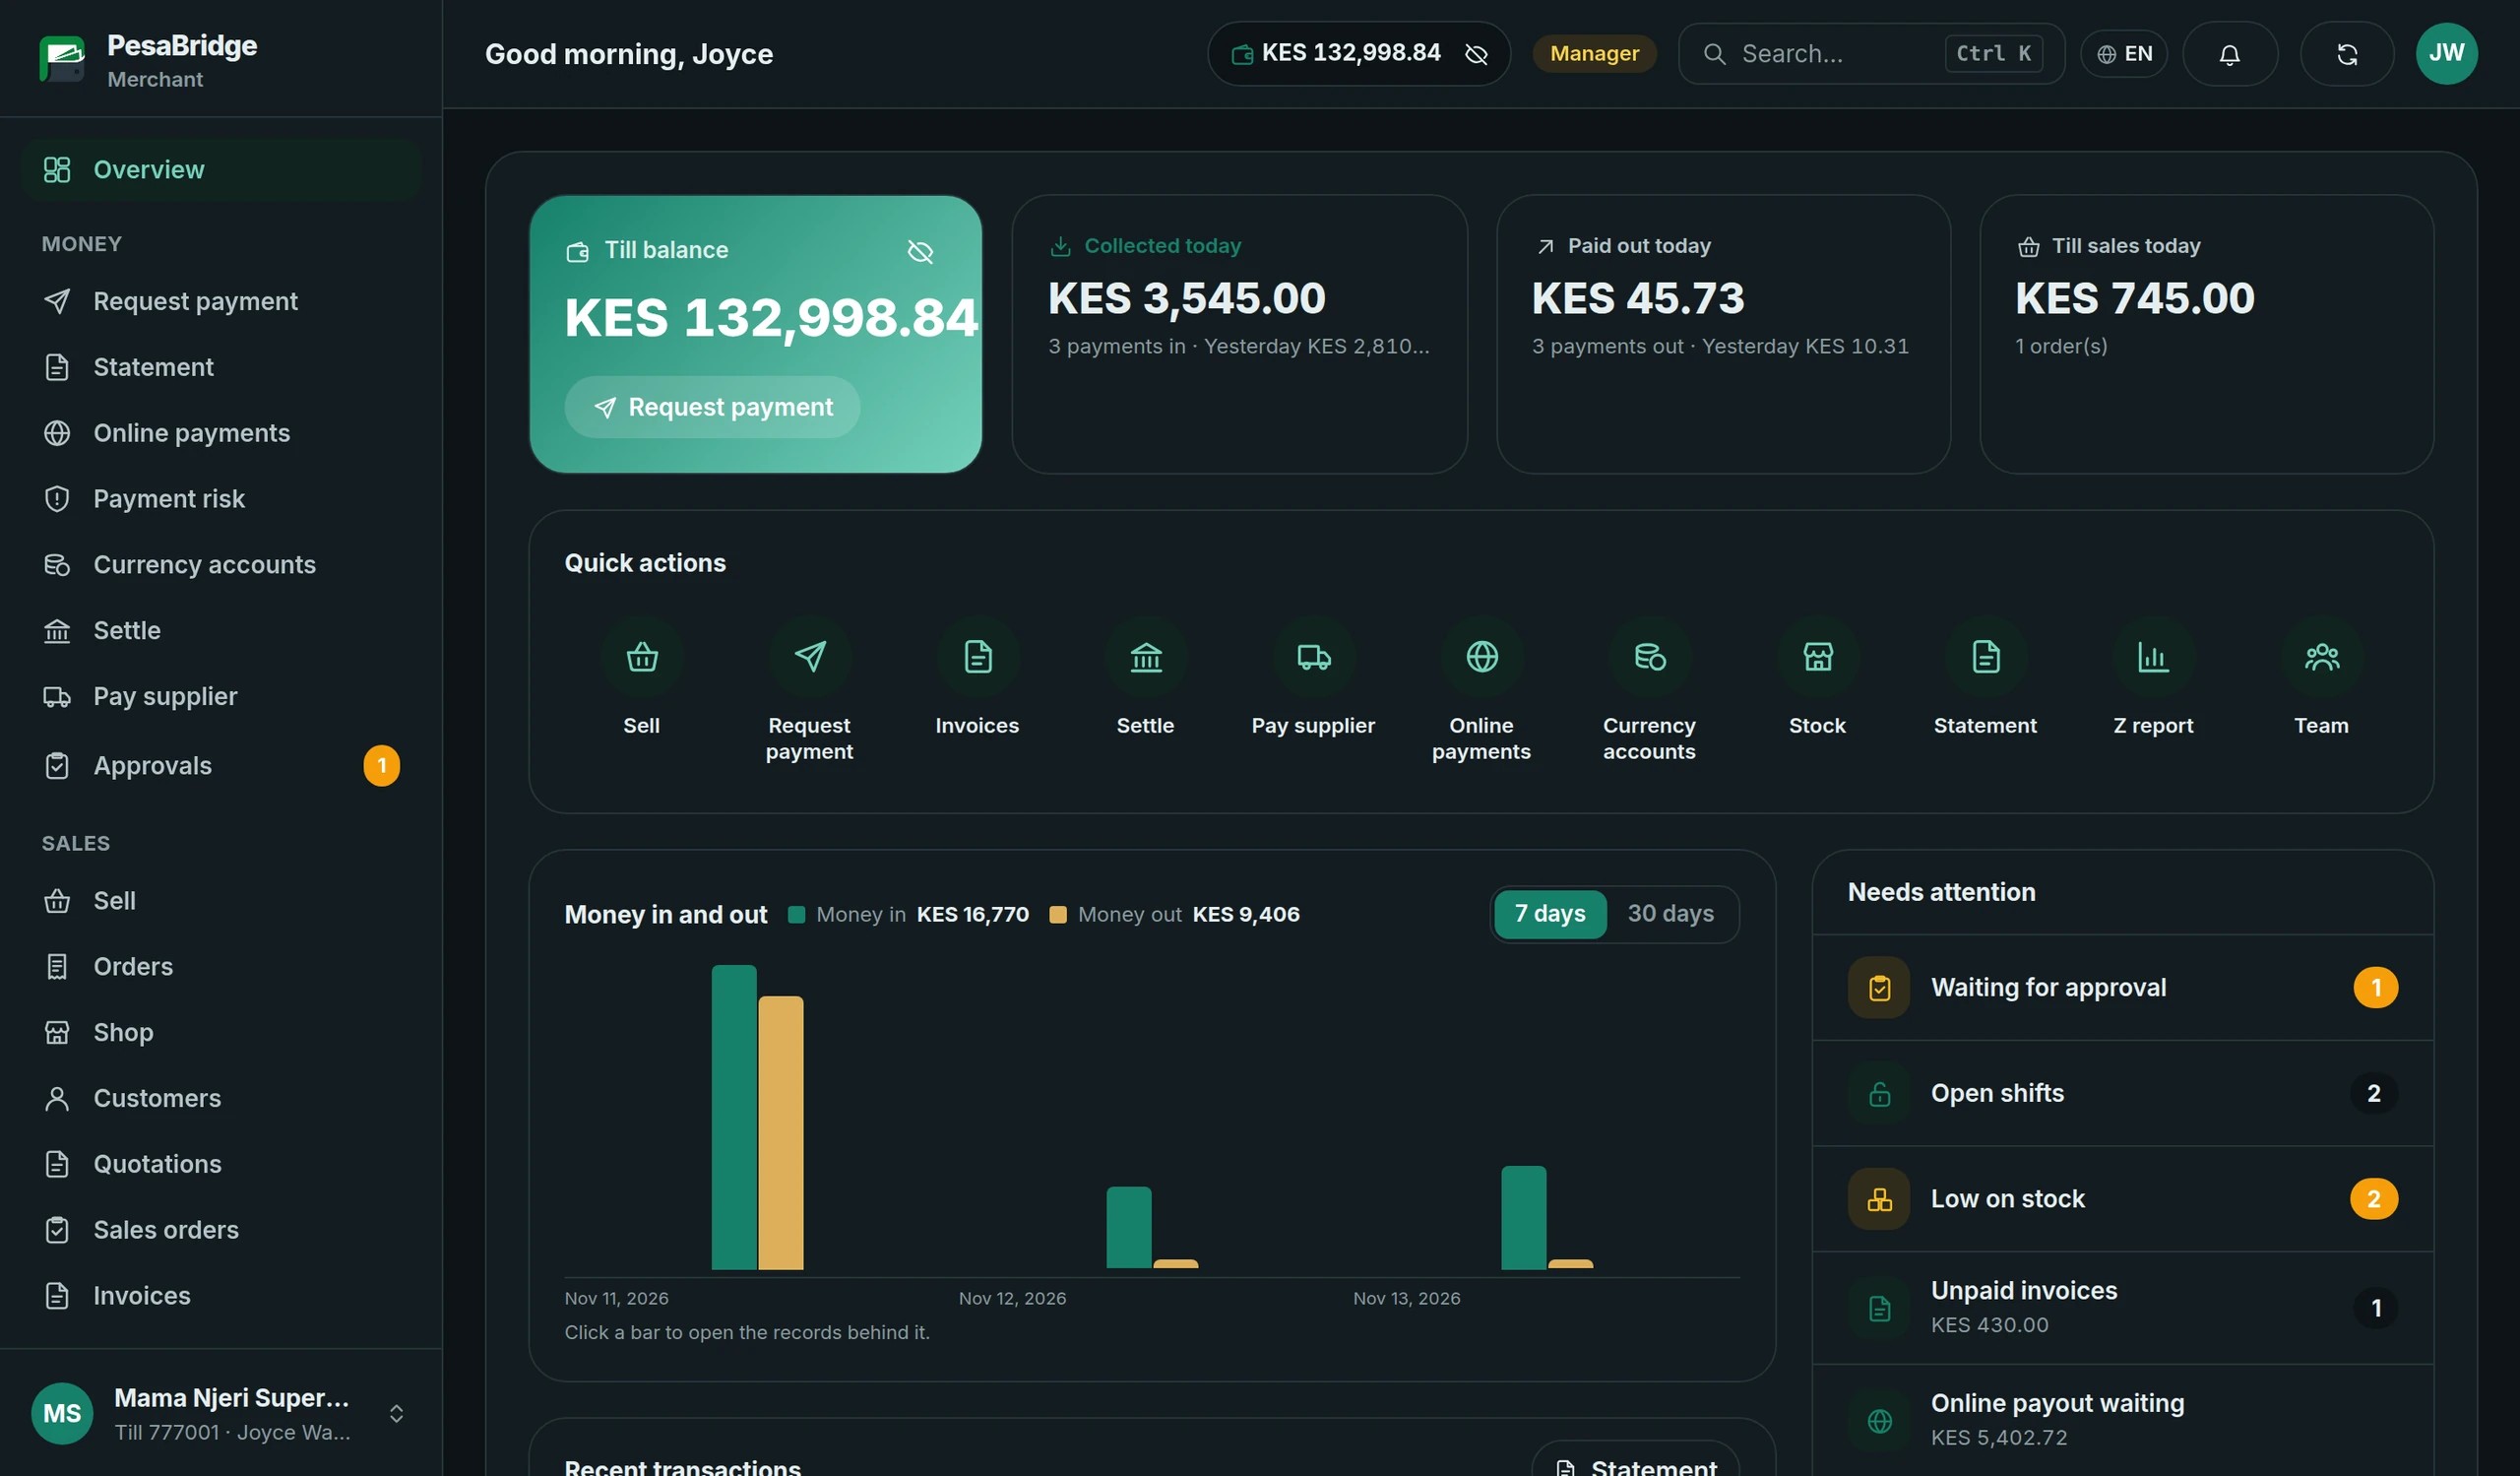
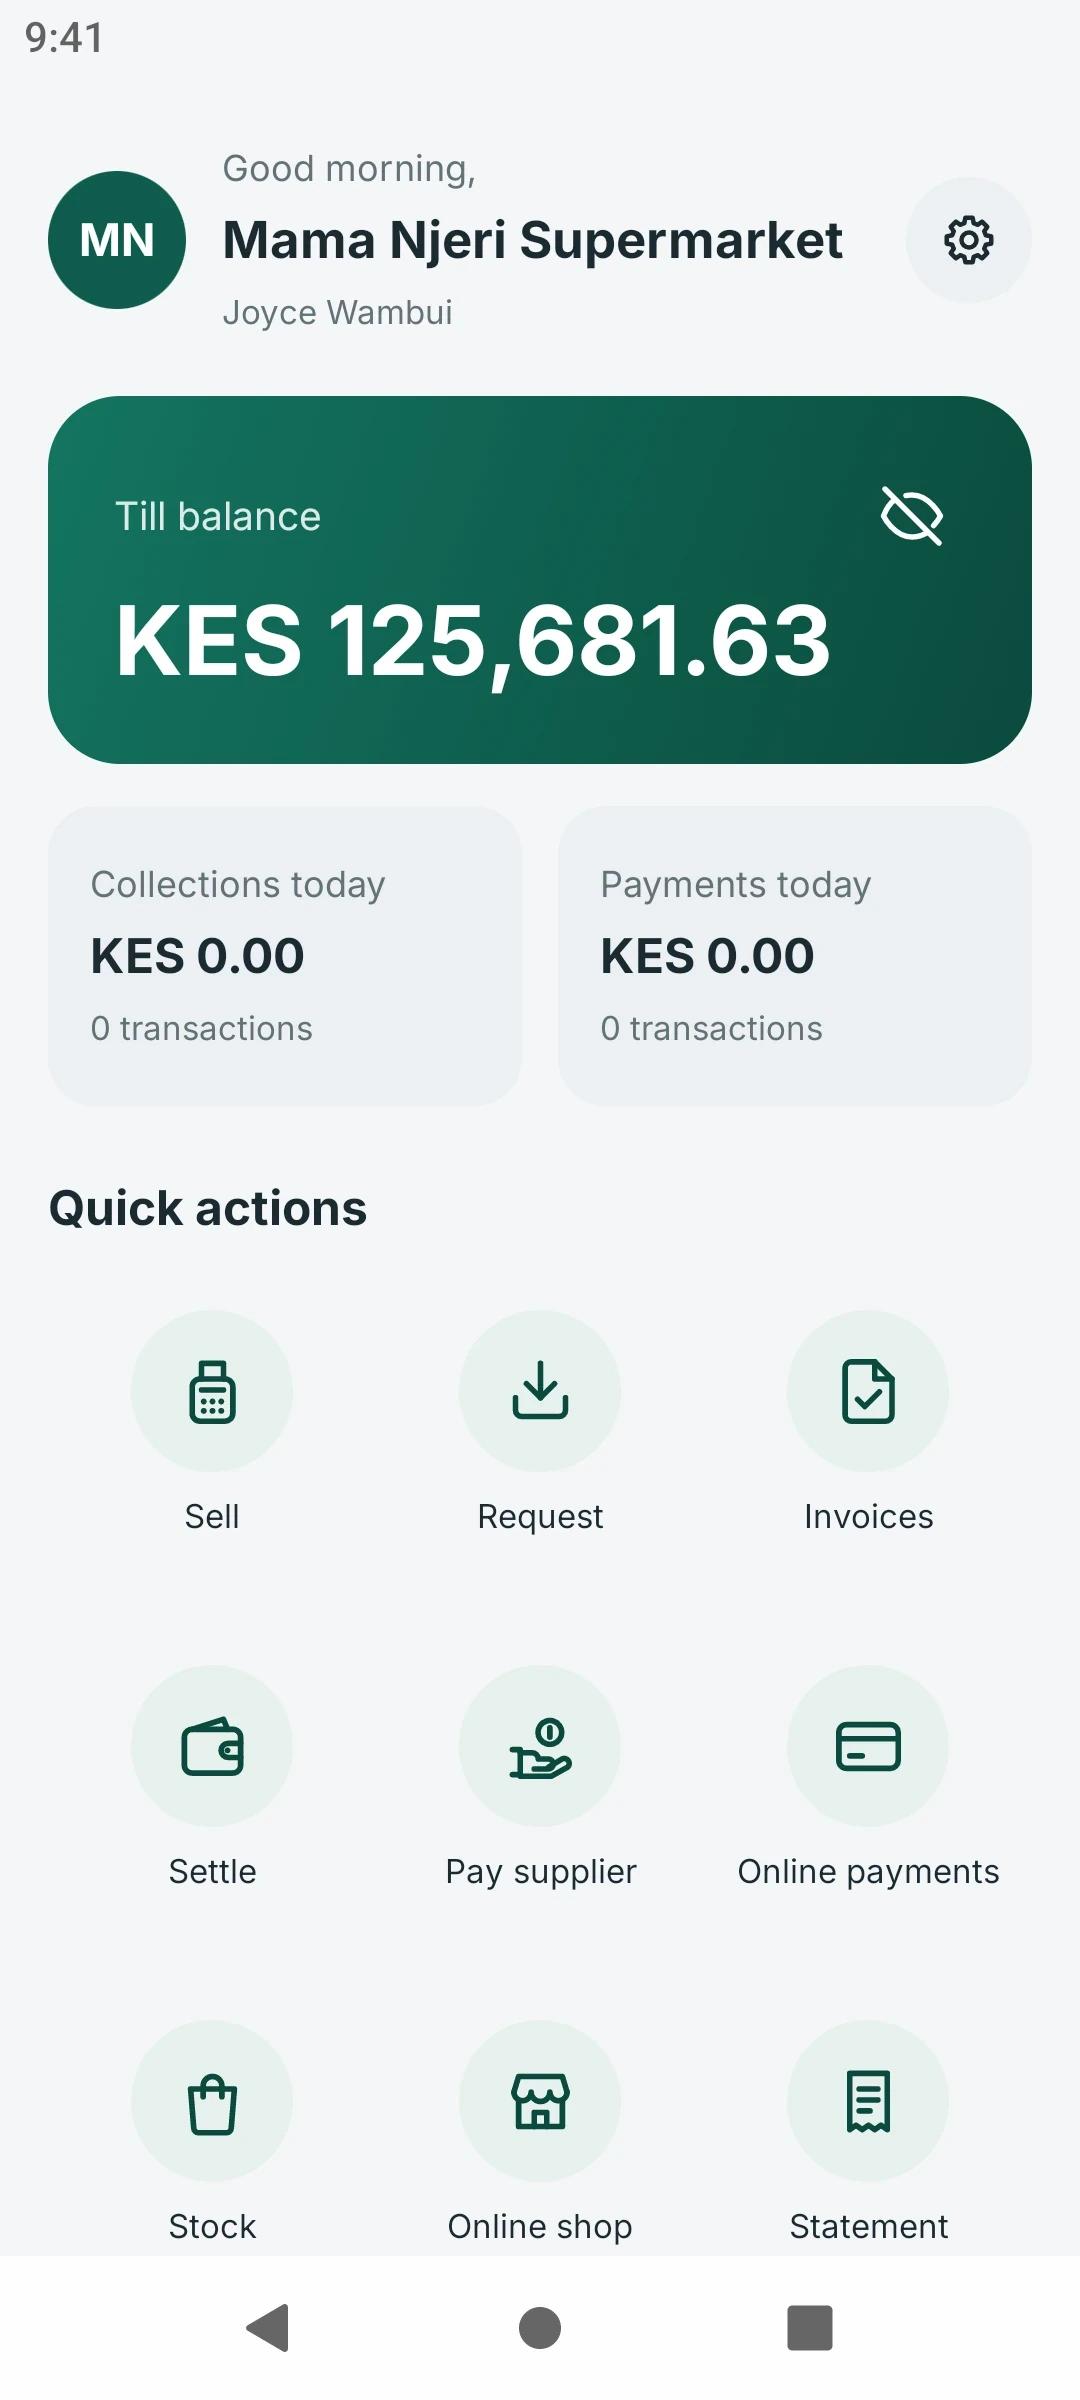
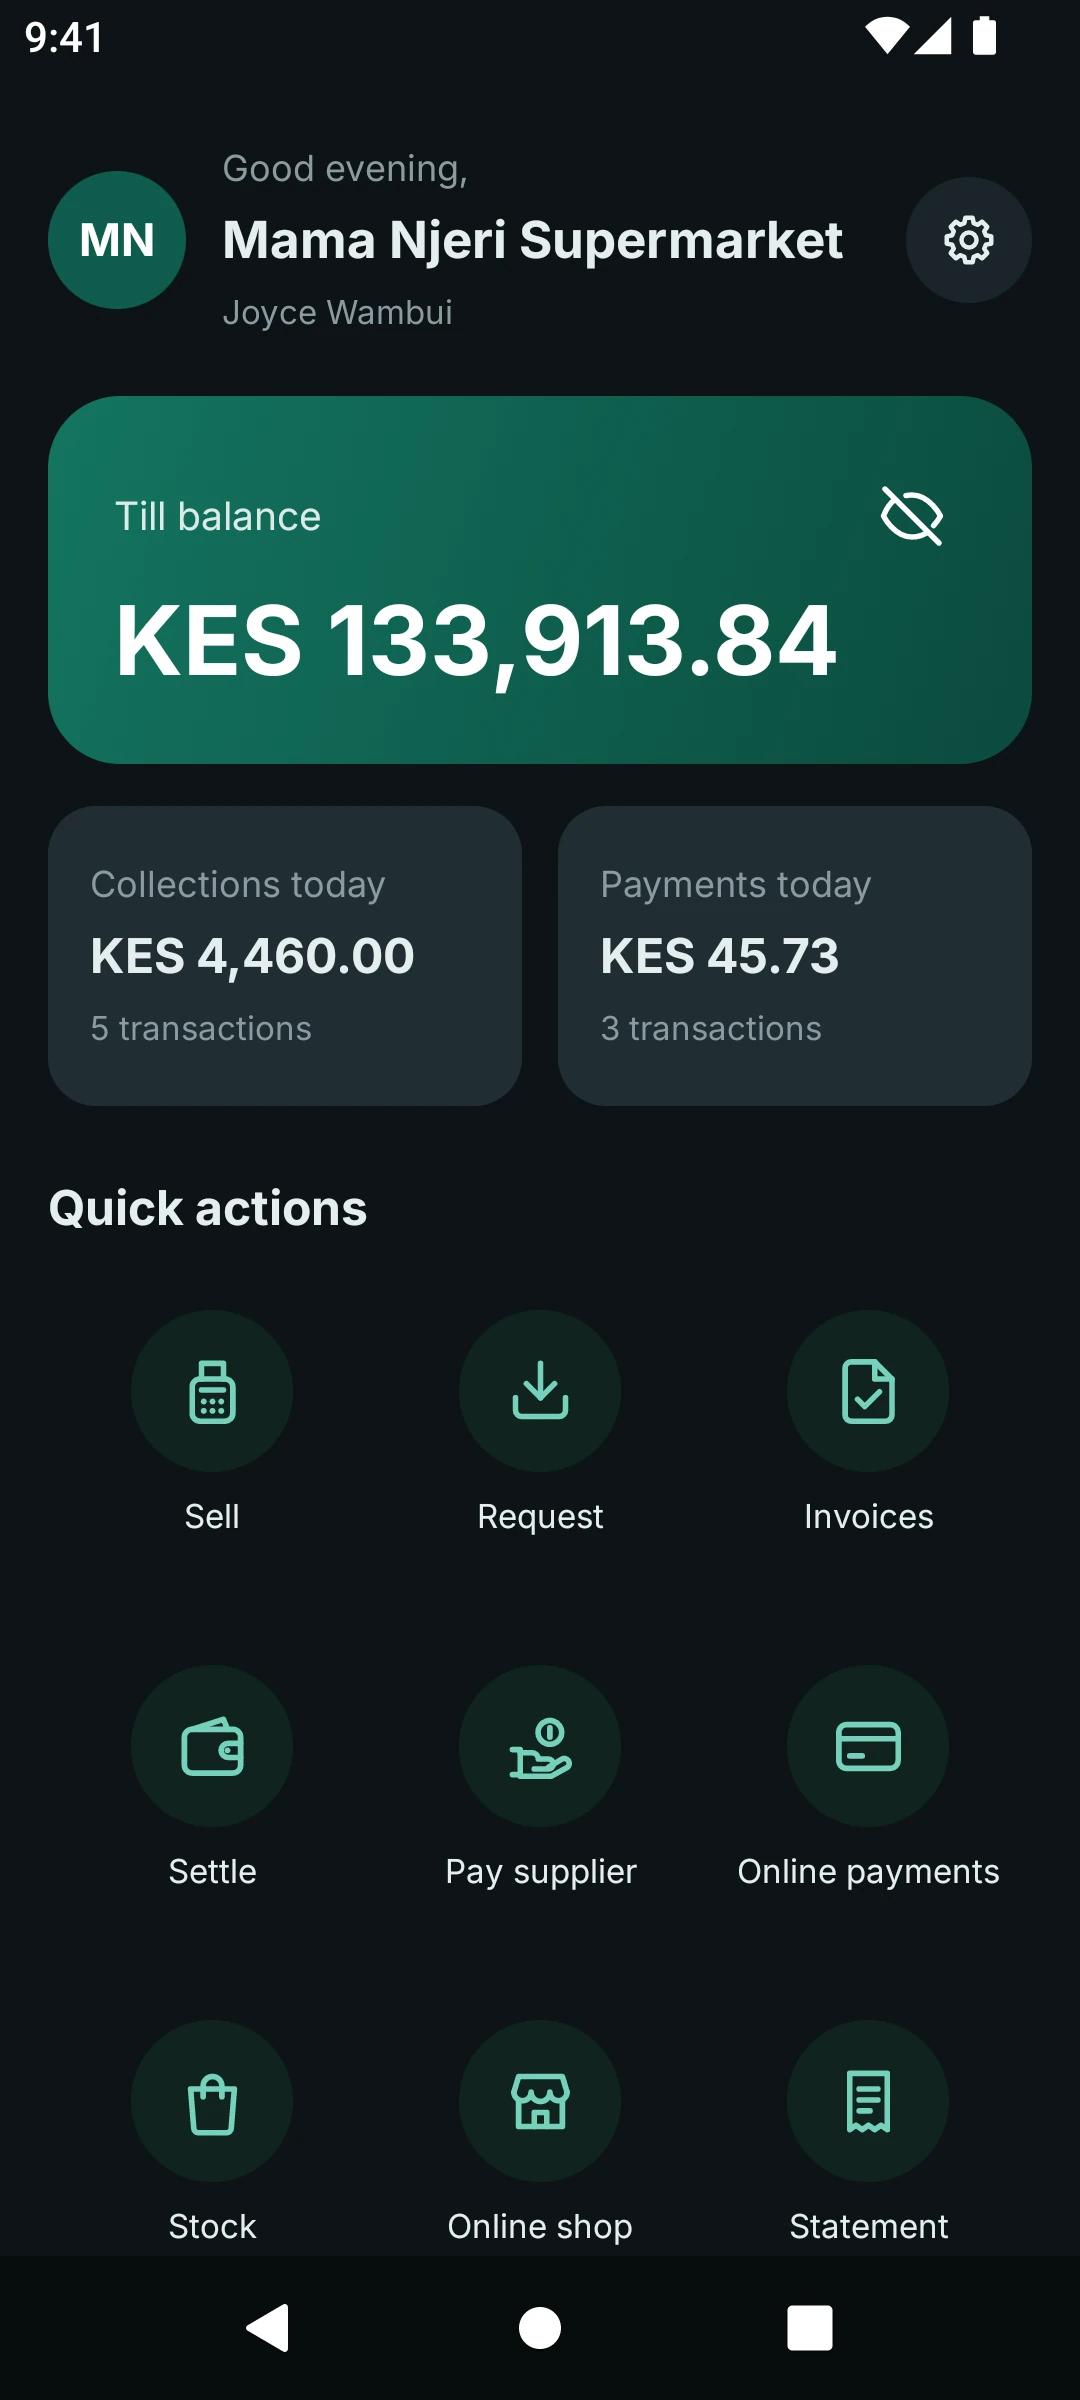
A till, a POS and a back office in one app
Sell from a product list or barcode, charge by prompt or QR, settle to bank or wallet, and close the day with a Z-report.
- Sell fast. Products from a list or a barcode, with stock that updates on every sale.
- Paid by prompt or QR. The customer approves on their own phone and the till balance updates at once.
- Staff with their own logins. Operators sell under their own name, and you approve what needs a second pair of eyes.
- Settle your way. Move the money to the wallet, an agent or a bank account.
- Close the day. A Z-report for the till, with every sale in the history and reports.
Cash in, cash out
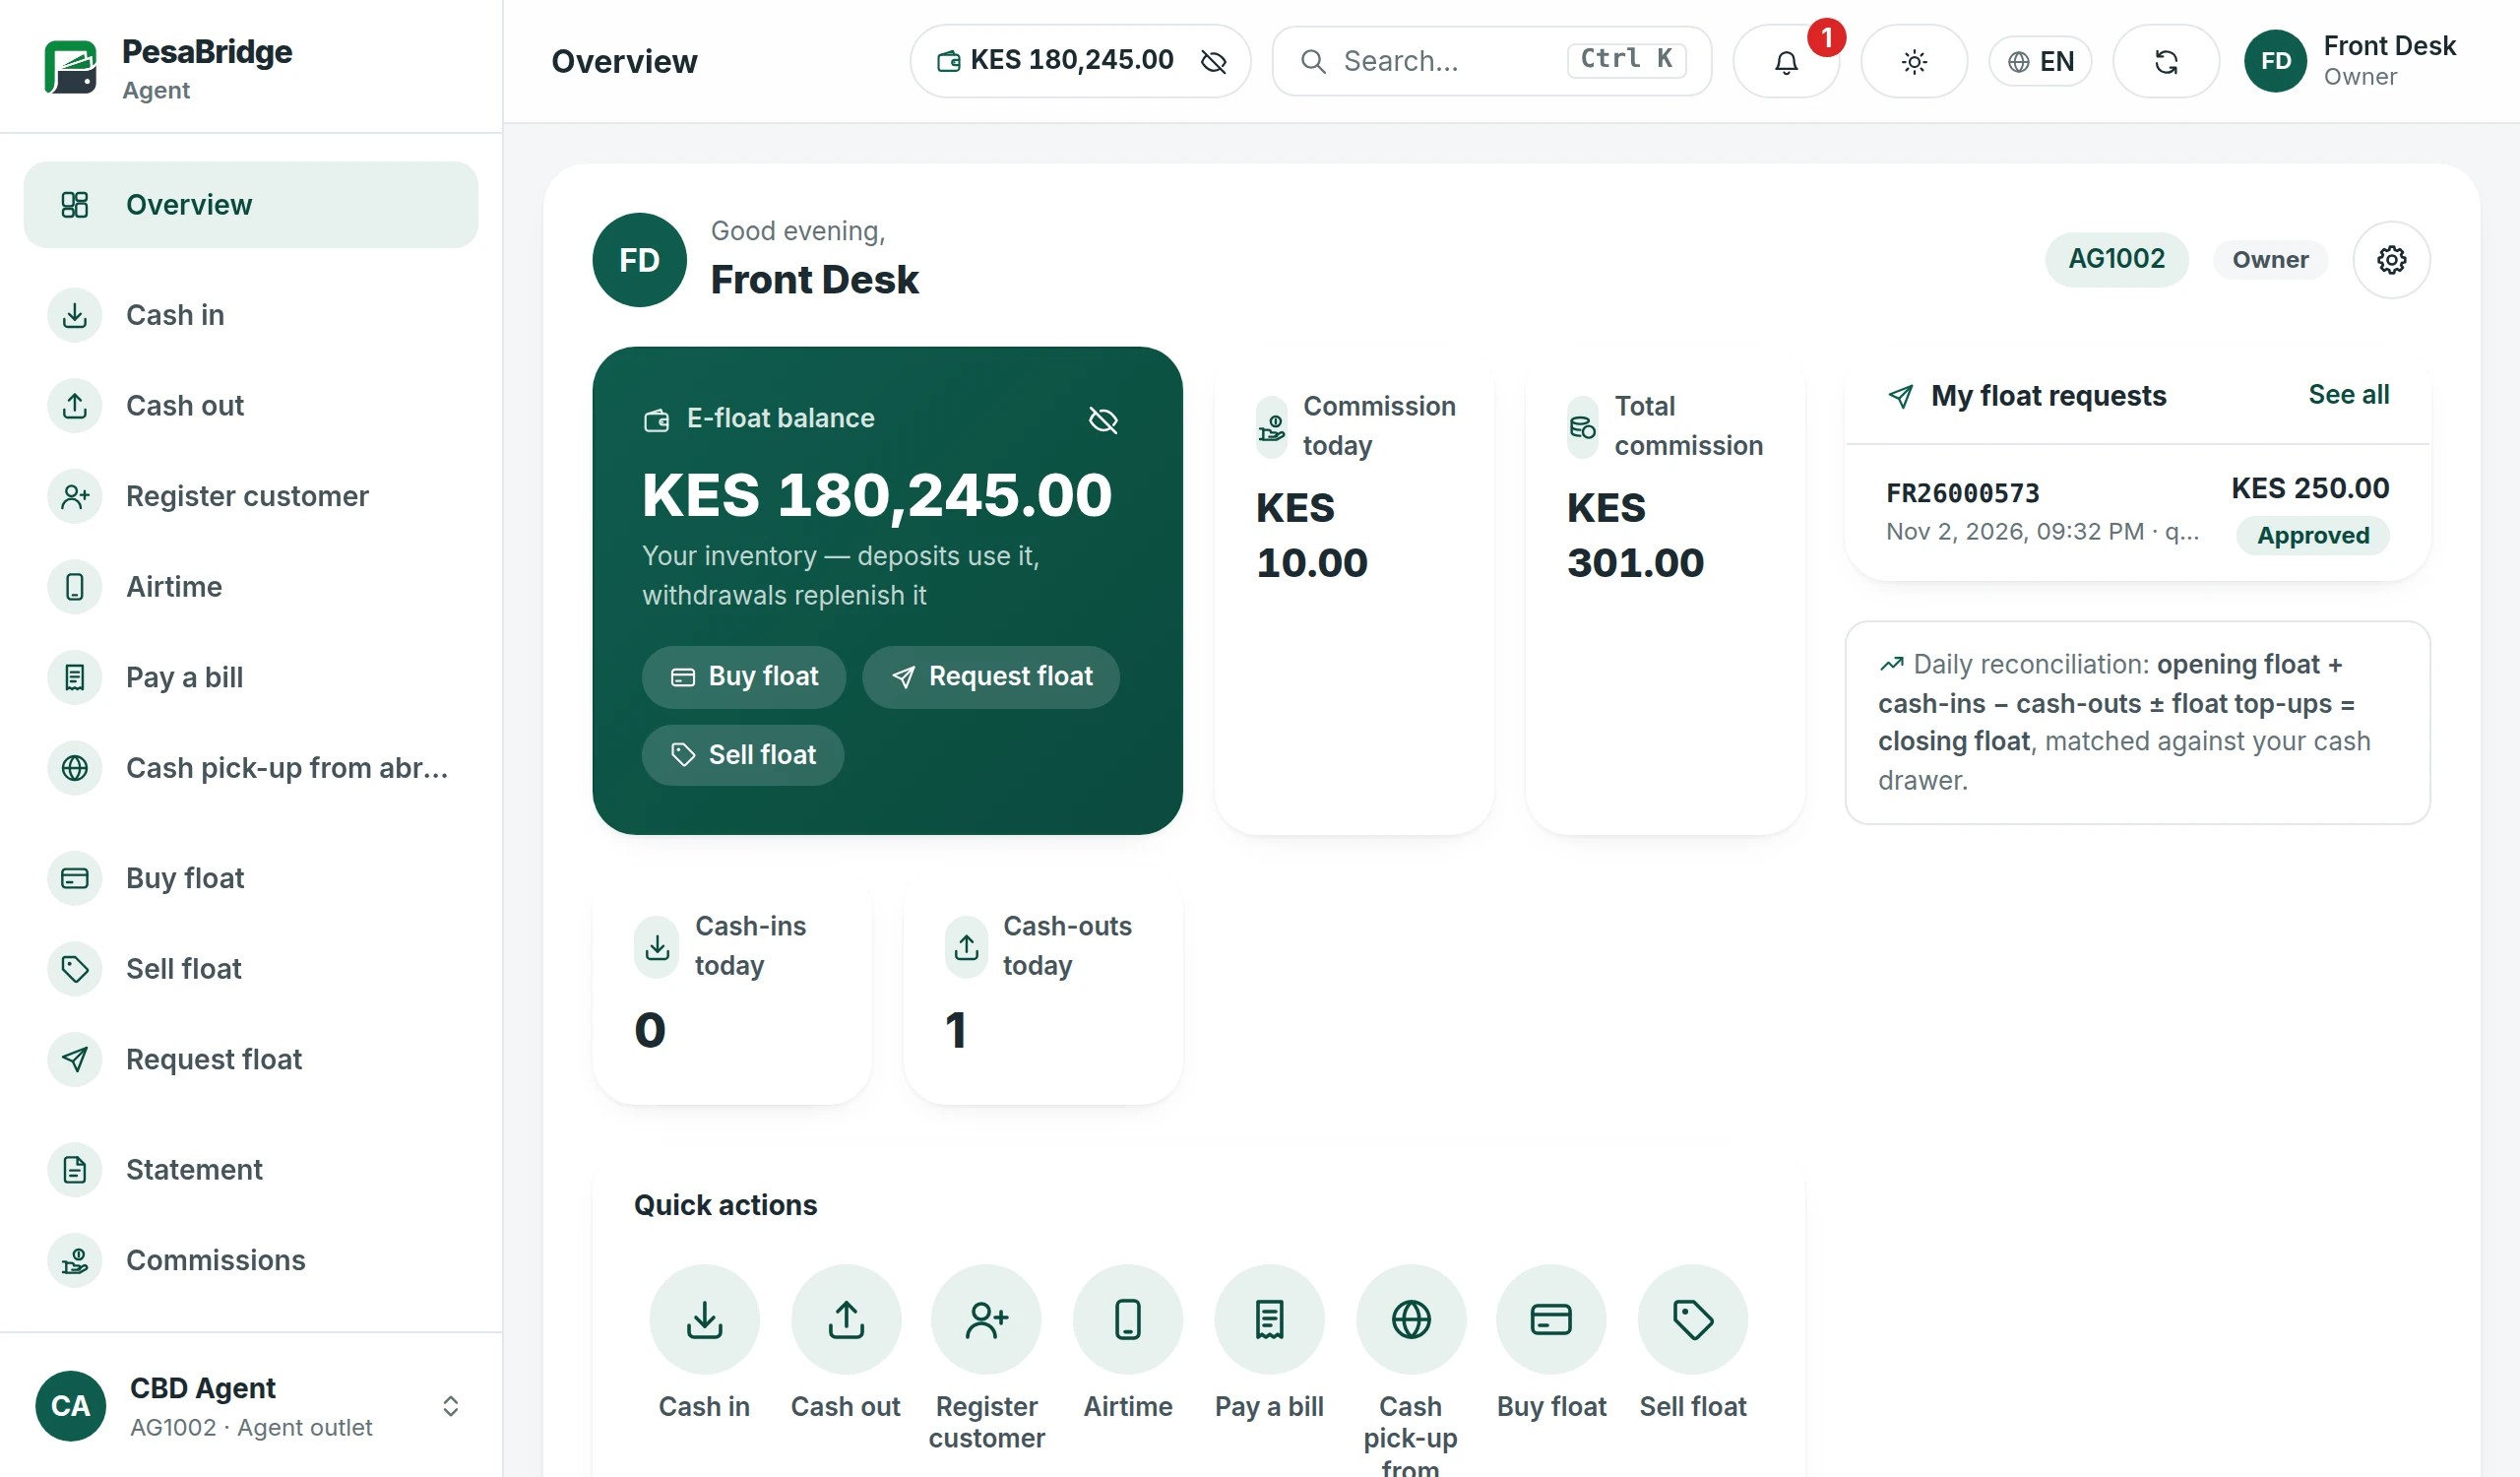
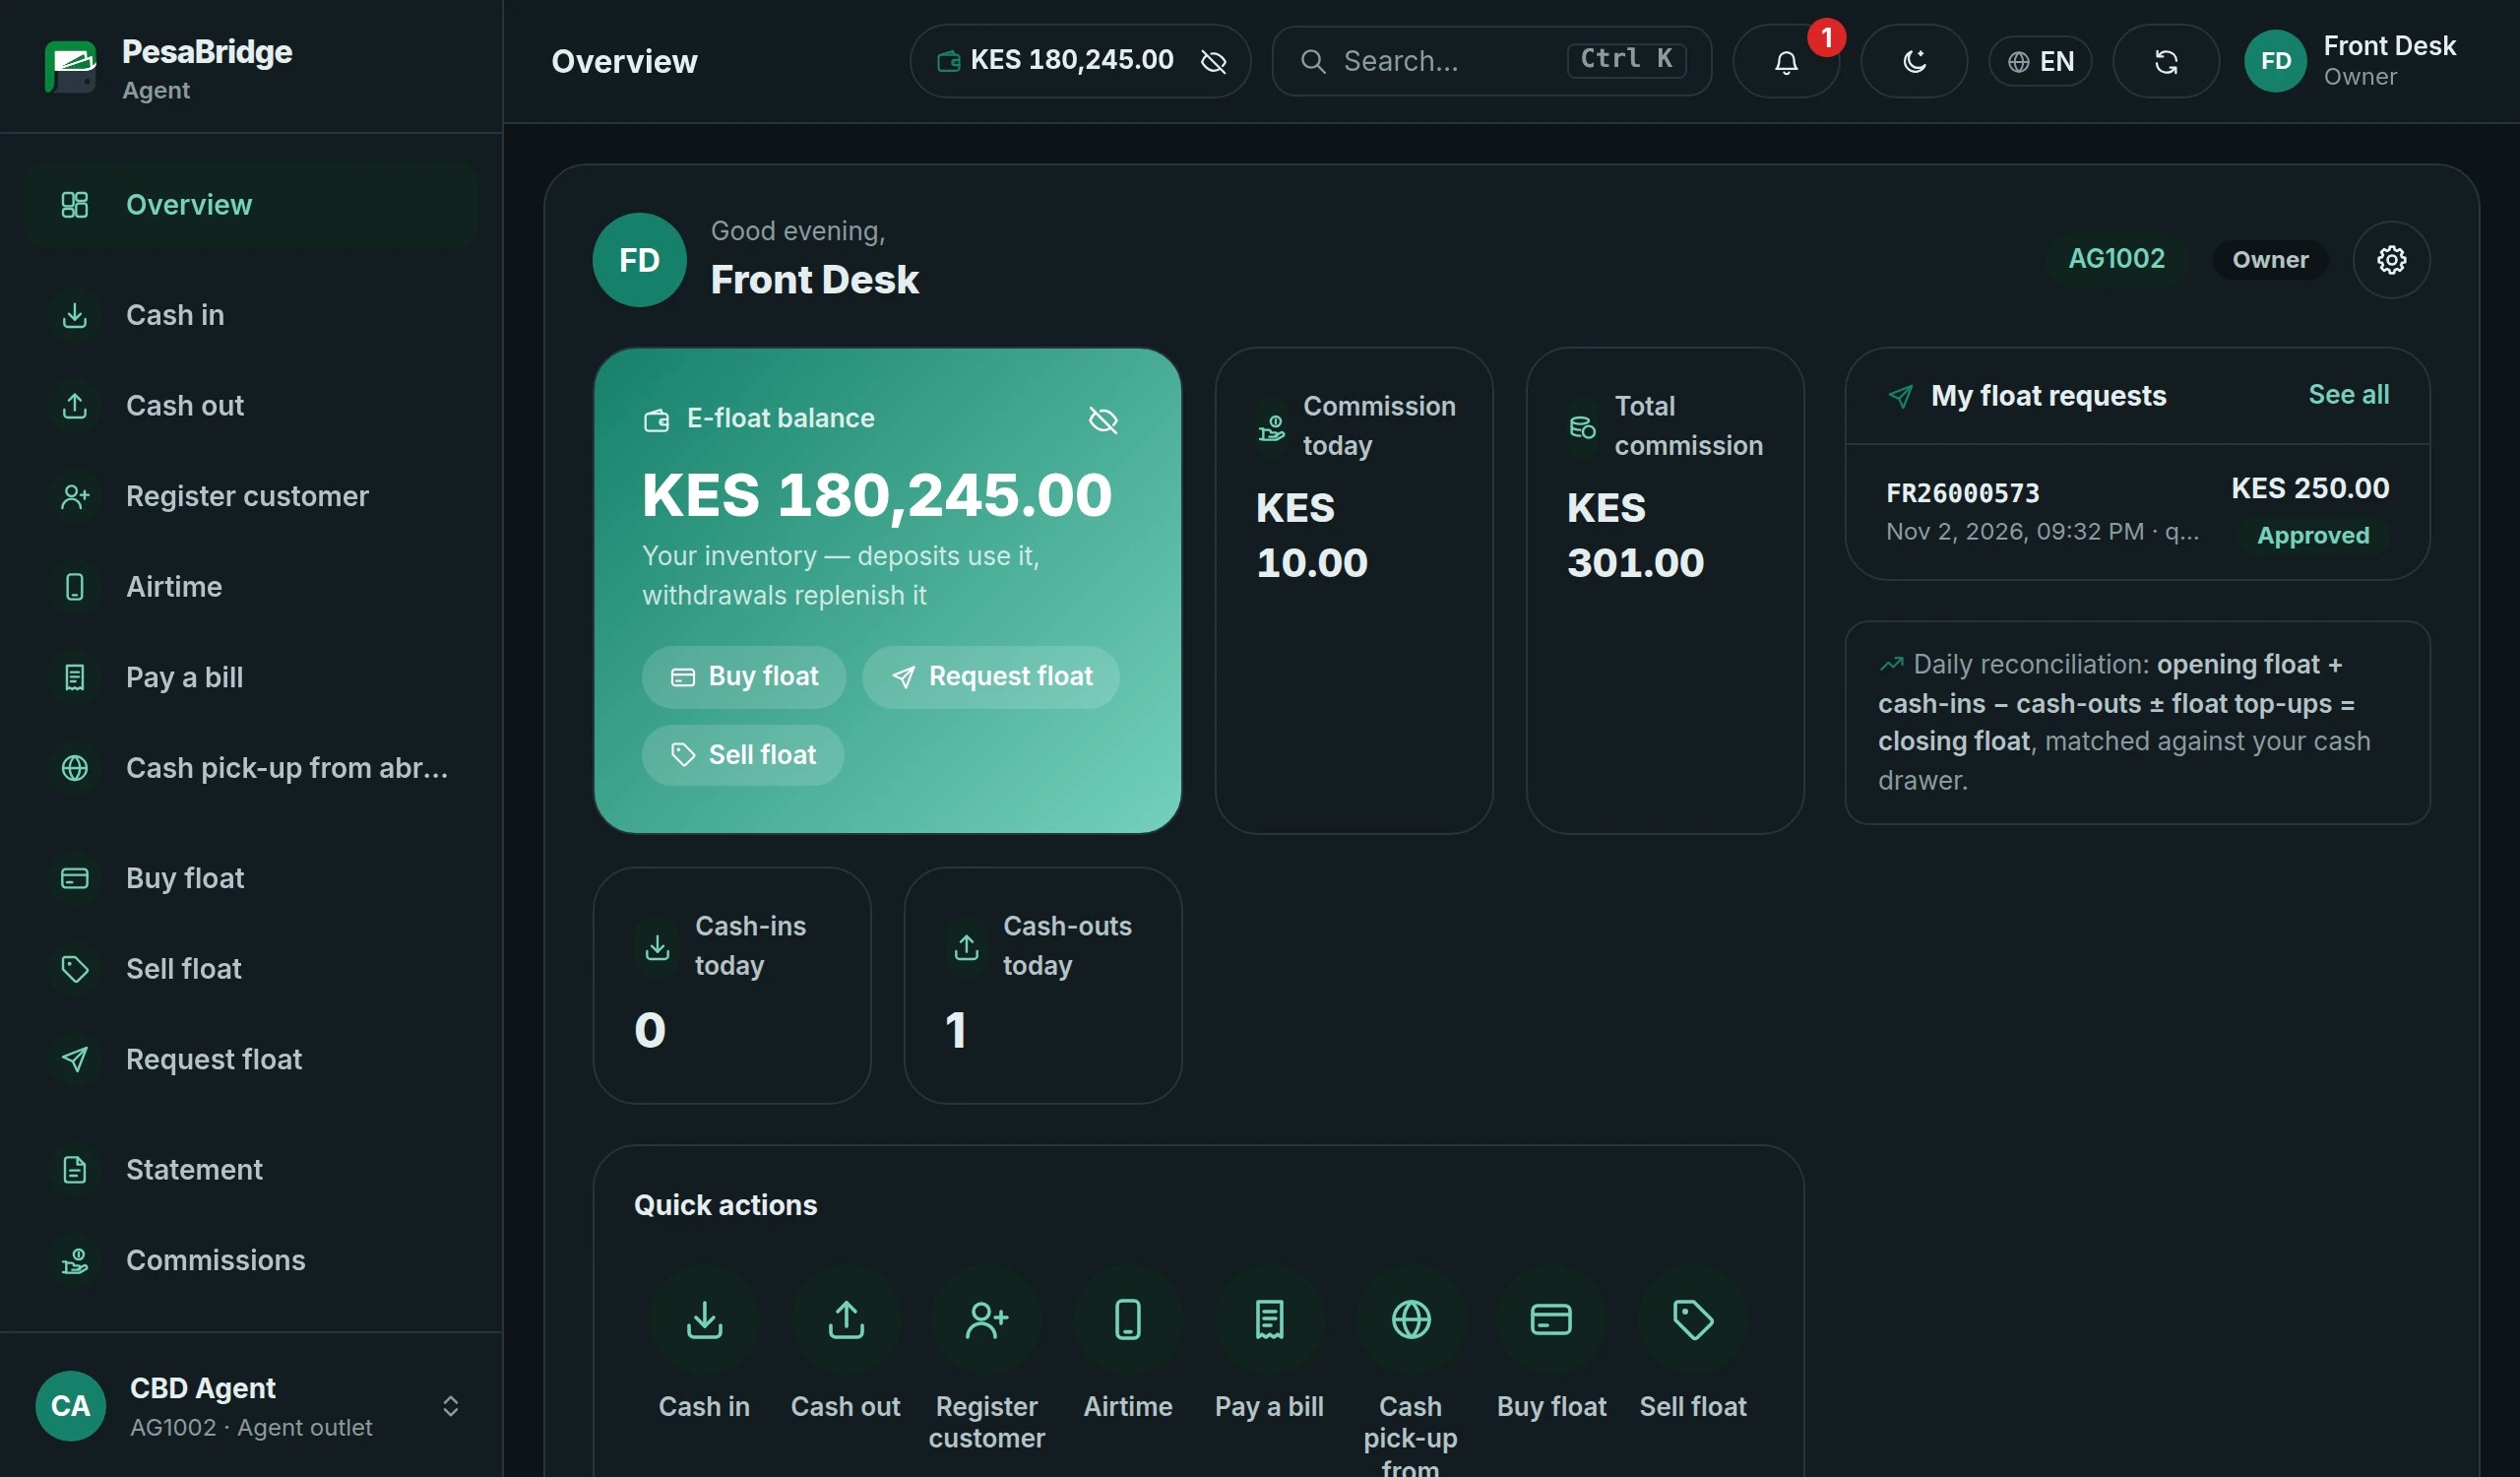
An agent network that turns cash into digital money and back
Most customers start with cash. Your agents take deposits, pay out withdrawals and register new customers, and a three-level network of dealers, super-agents and agents keeps every outlet stocked with float.
- Deposits and withdrawals. The agent enters the amount, the customer approves a withdrawal on their own phone with their PIN.
- ID checks at the counter. A deposit stops if the phone number and the ID do not match.
- Float that flows down. Dealers and super-agents allocate float to their agents, approve float requests and recall float in a tap.
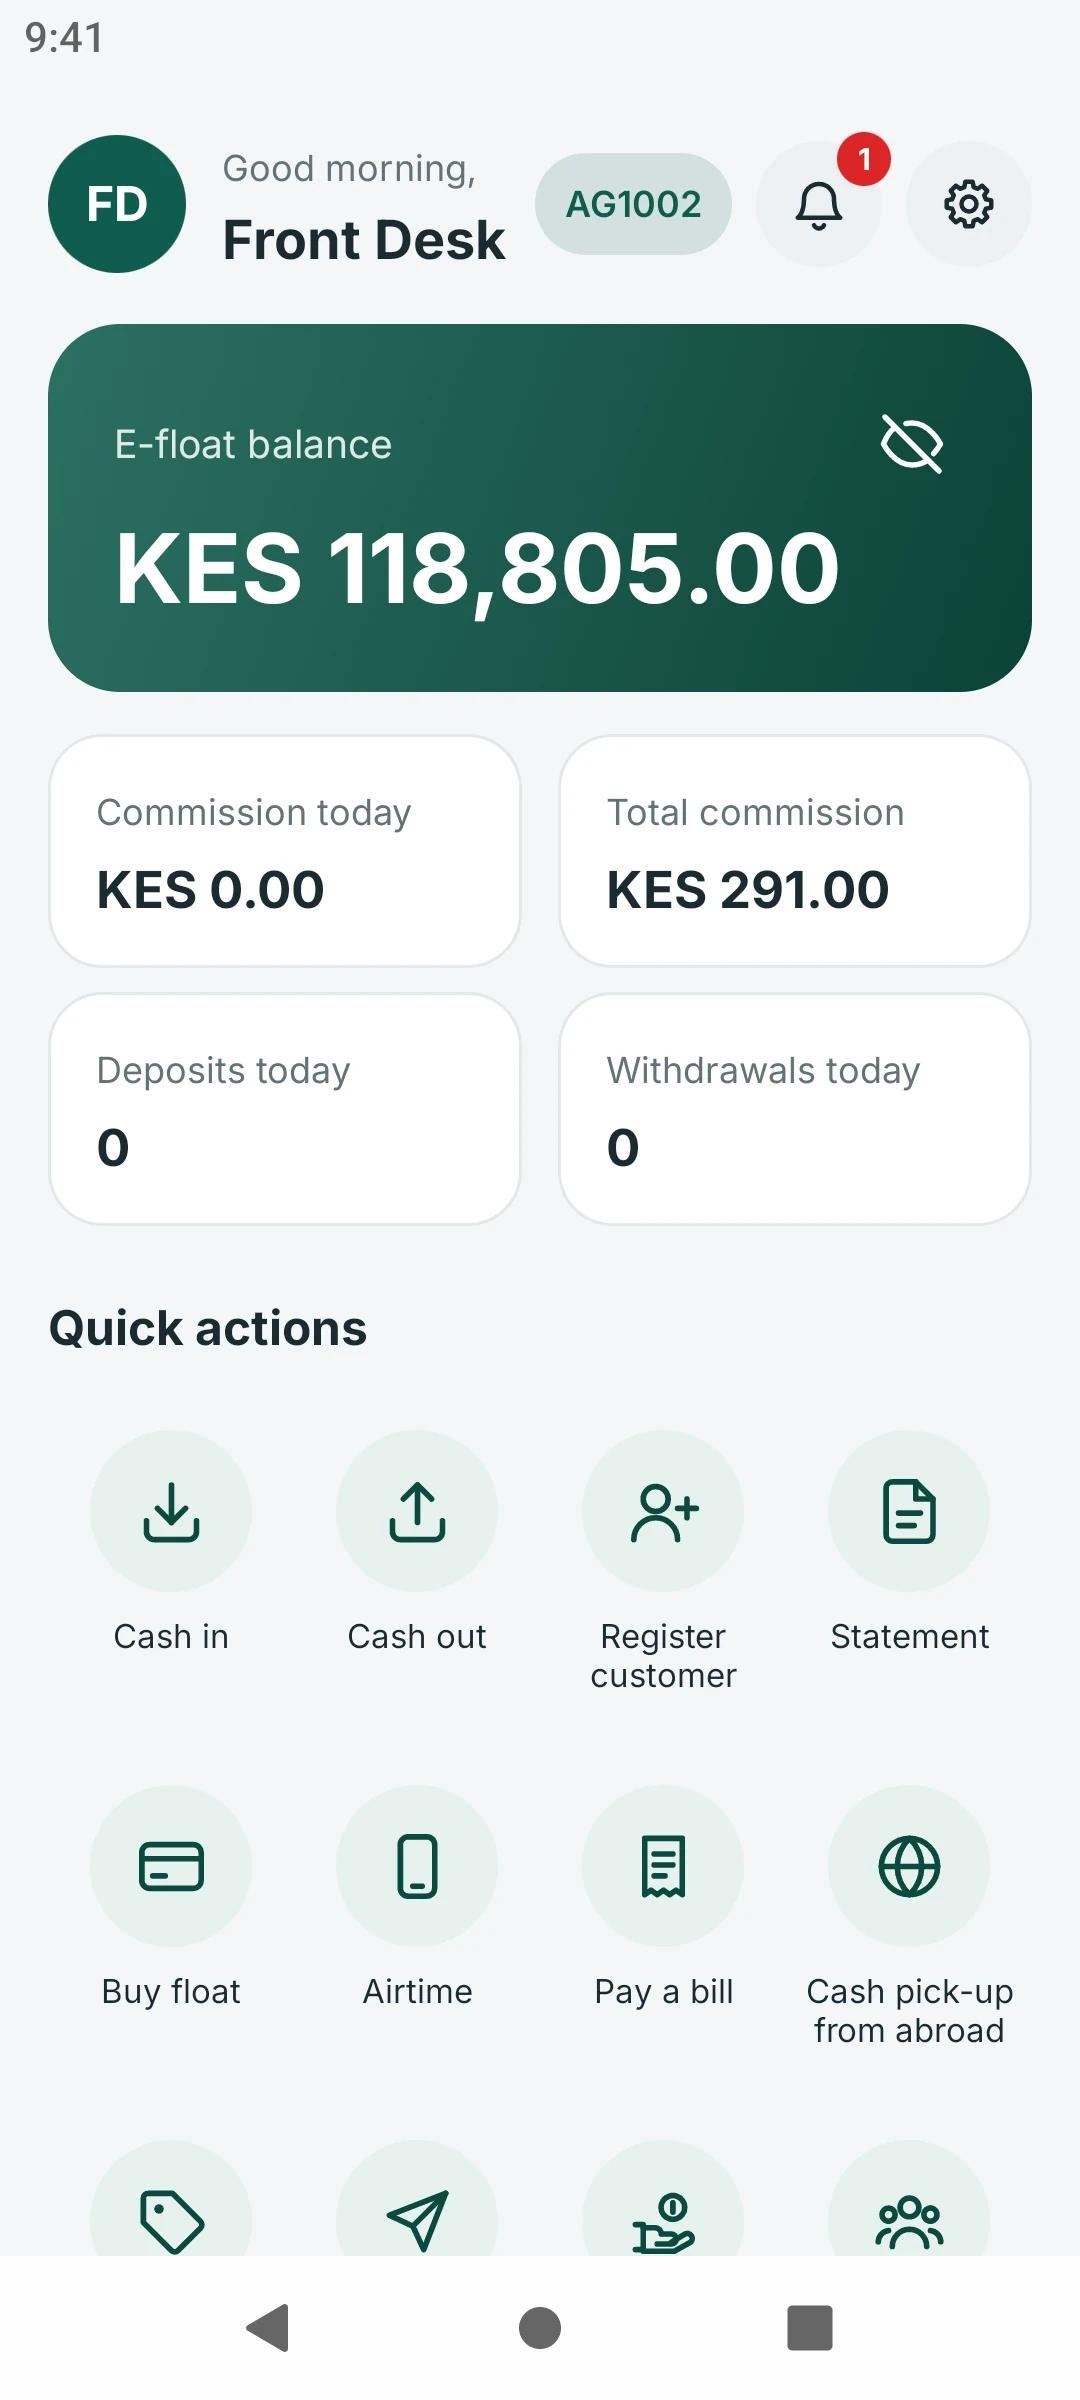
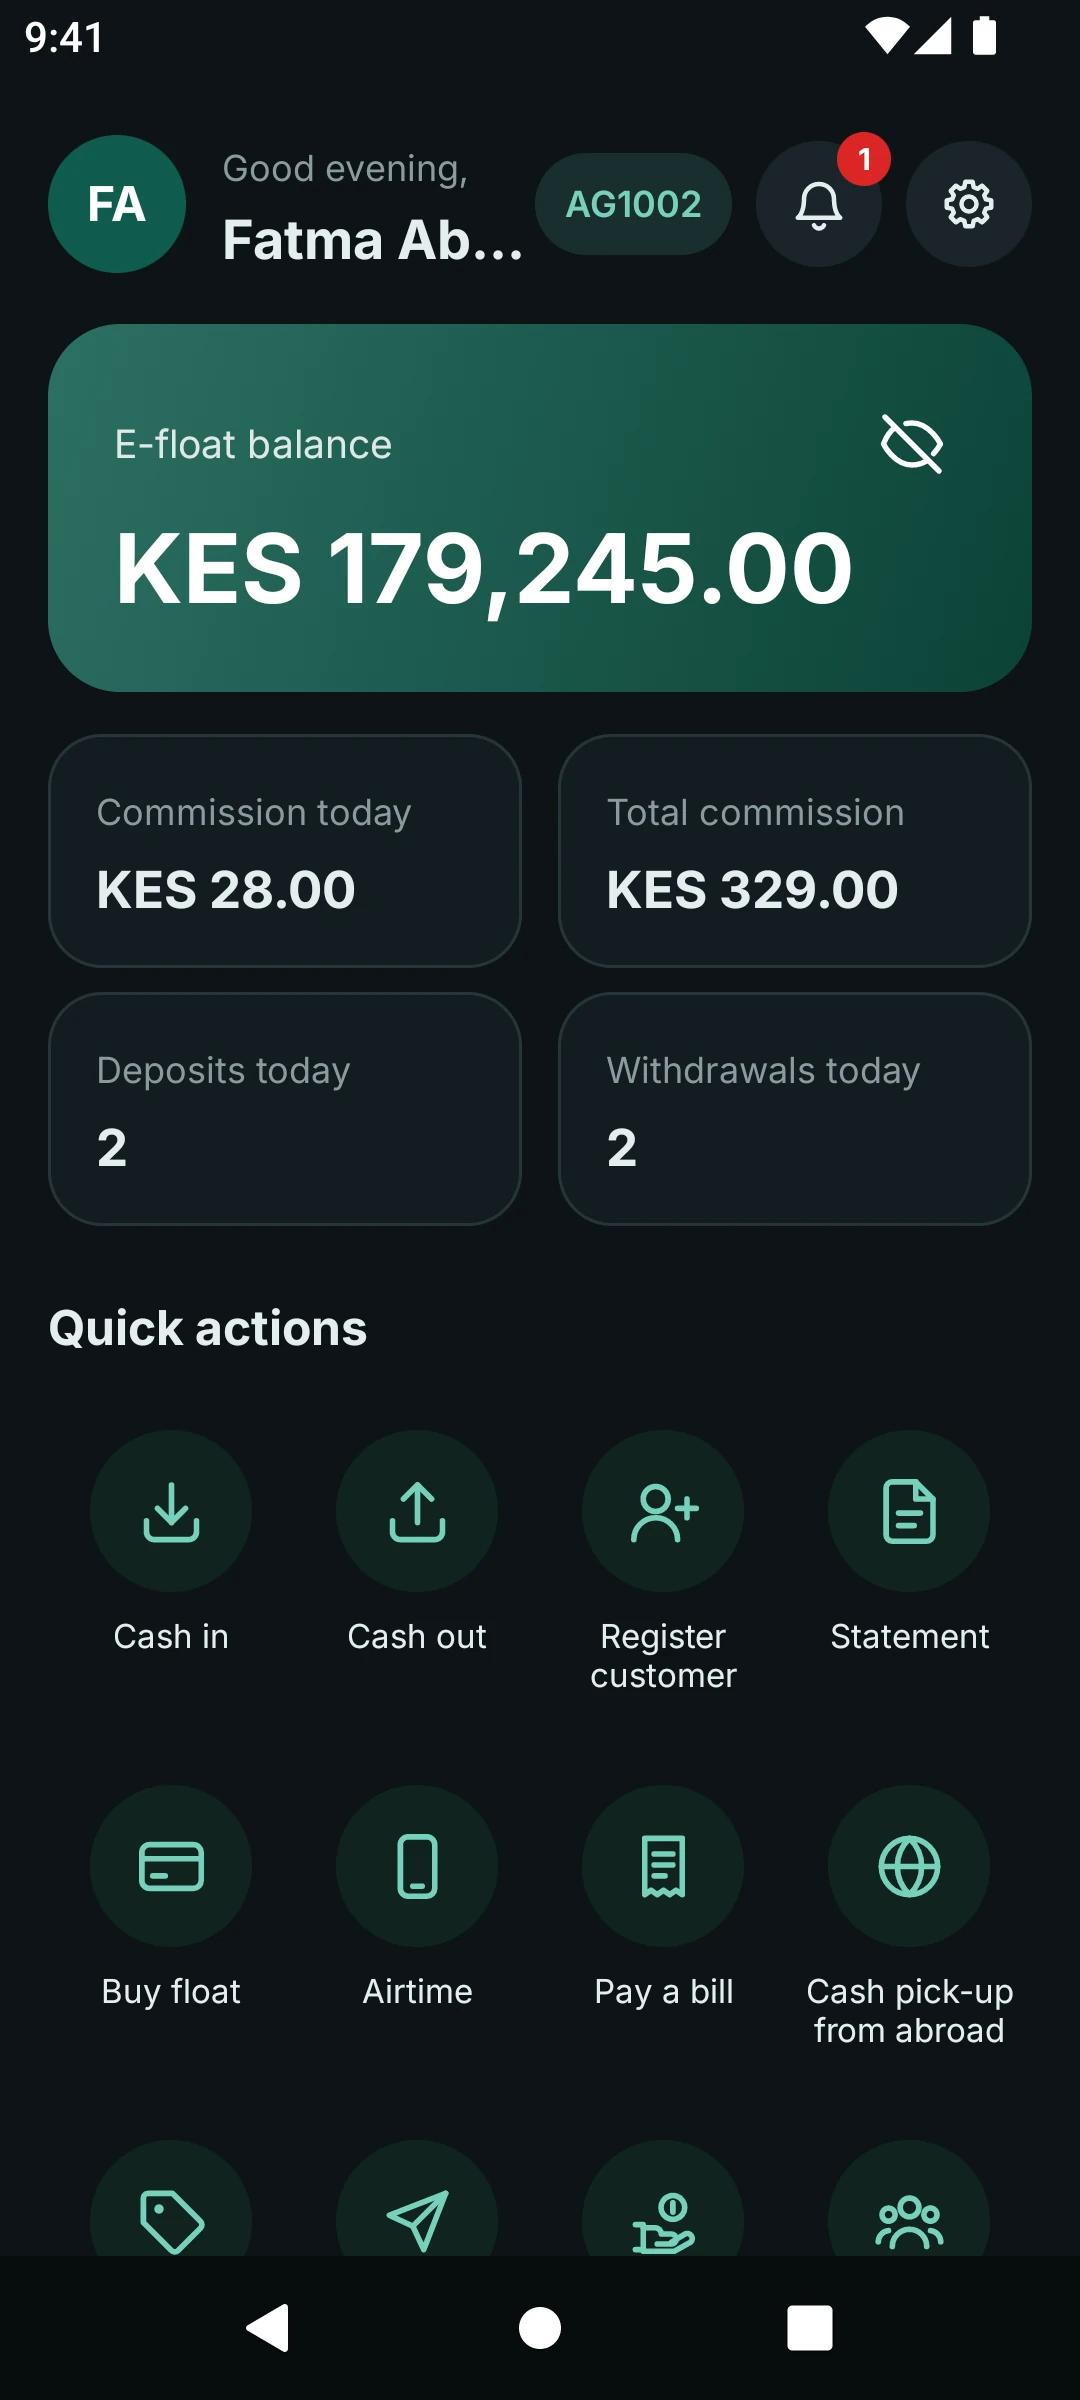
- Commissions that pay themselves. Agents see today's commission on their home screen. A monthly run, approved by a second person, pays it into their float, with an override share for the super-agent.
For companies
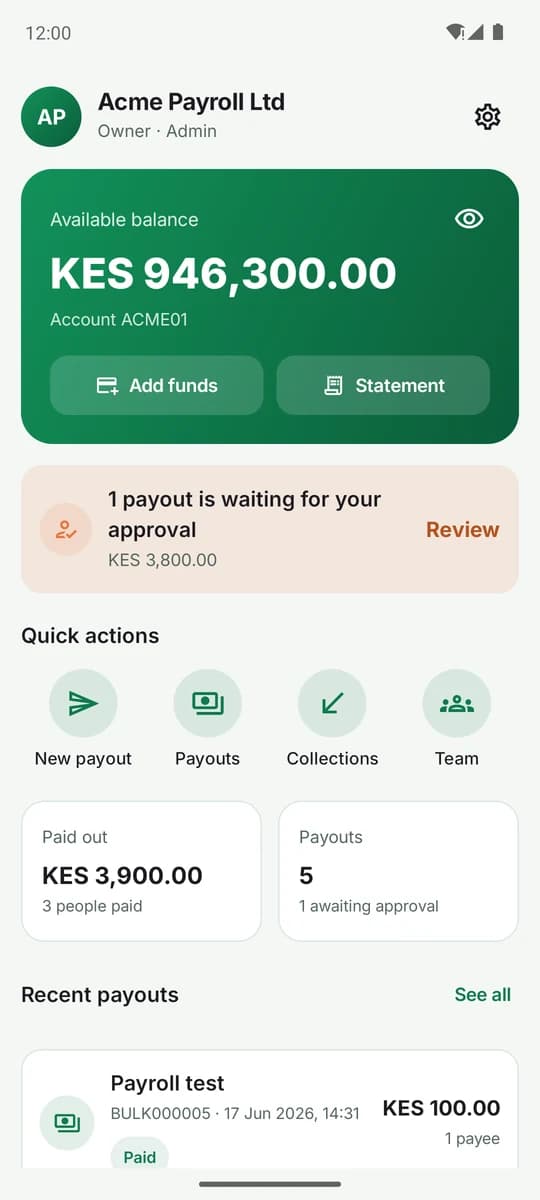
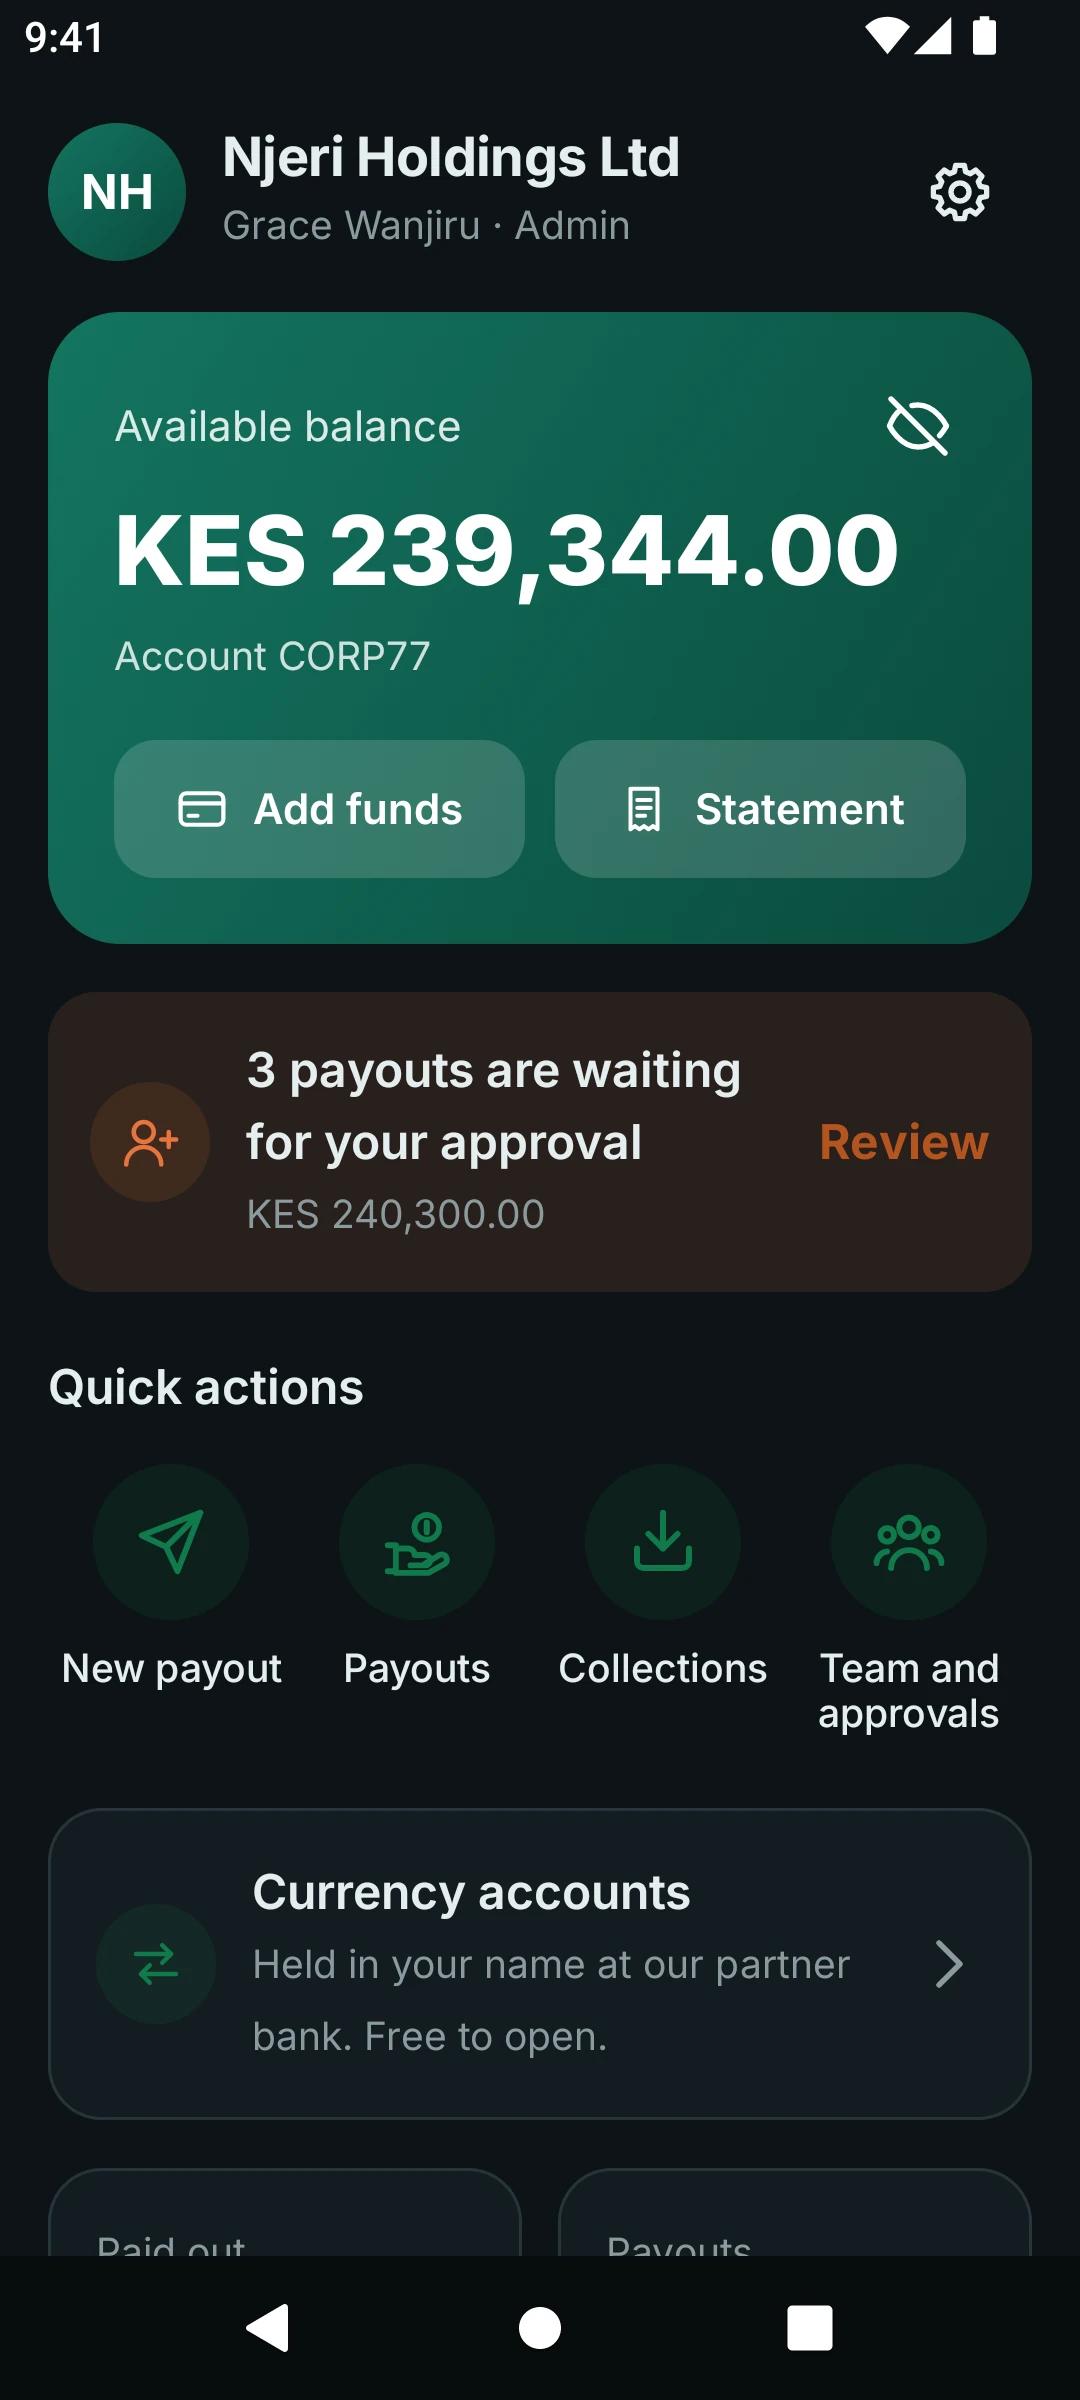
Pay salaries, suppliers and partners from one corporate wallet
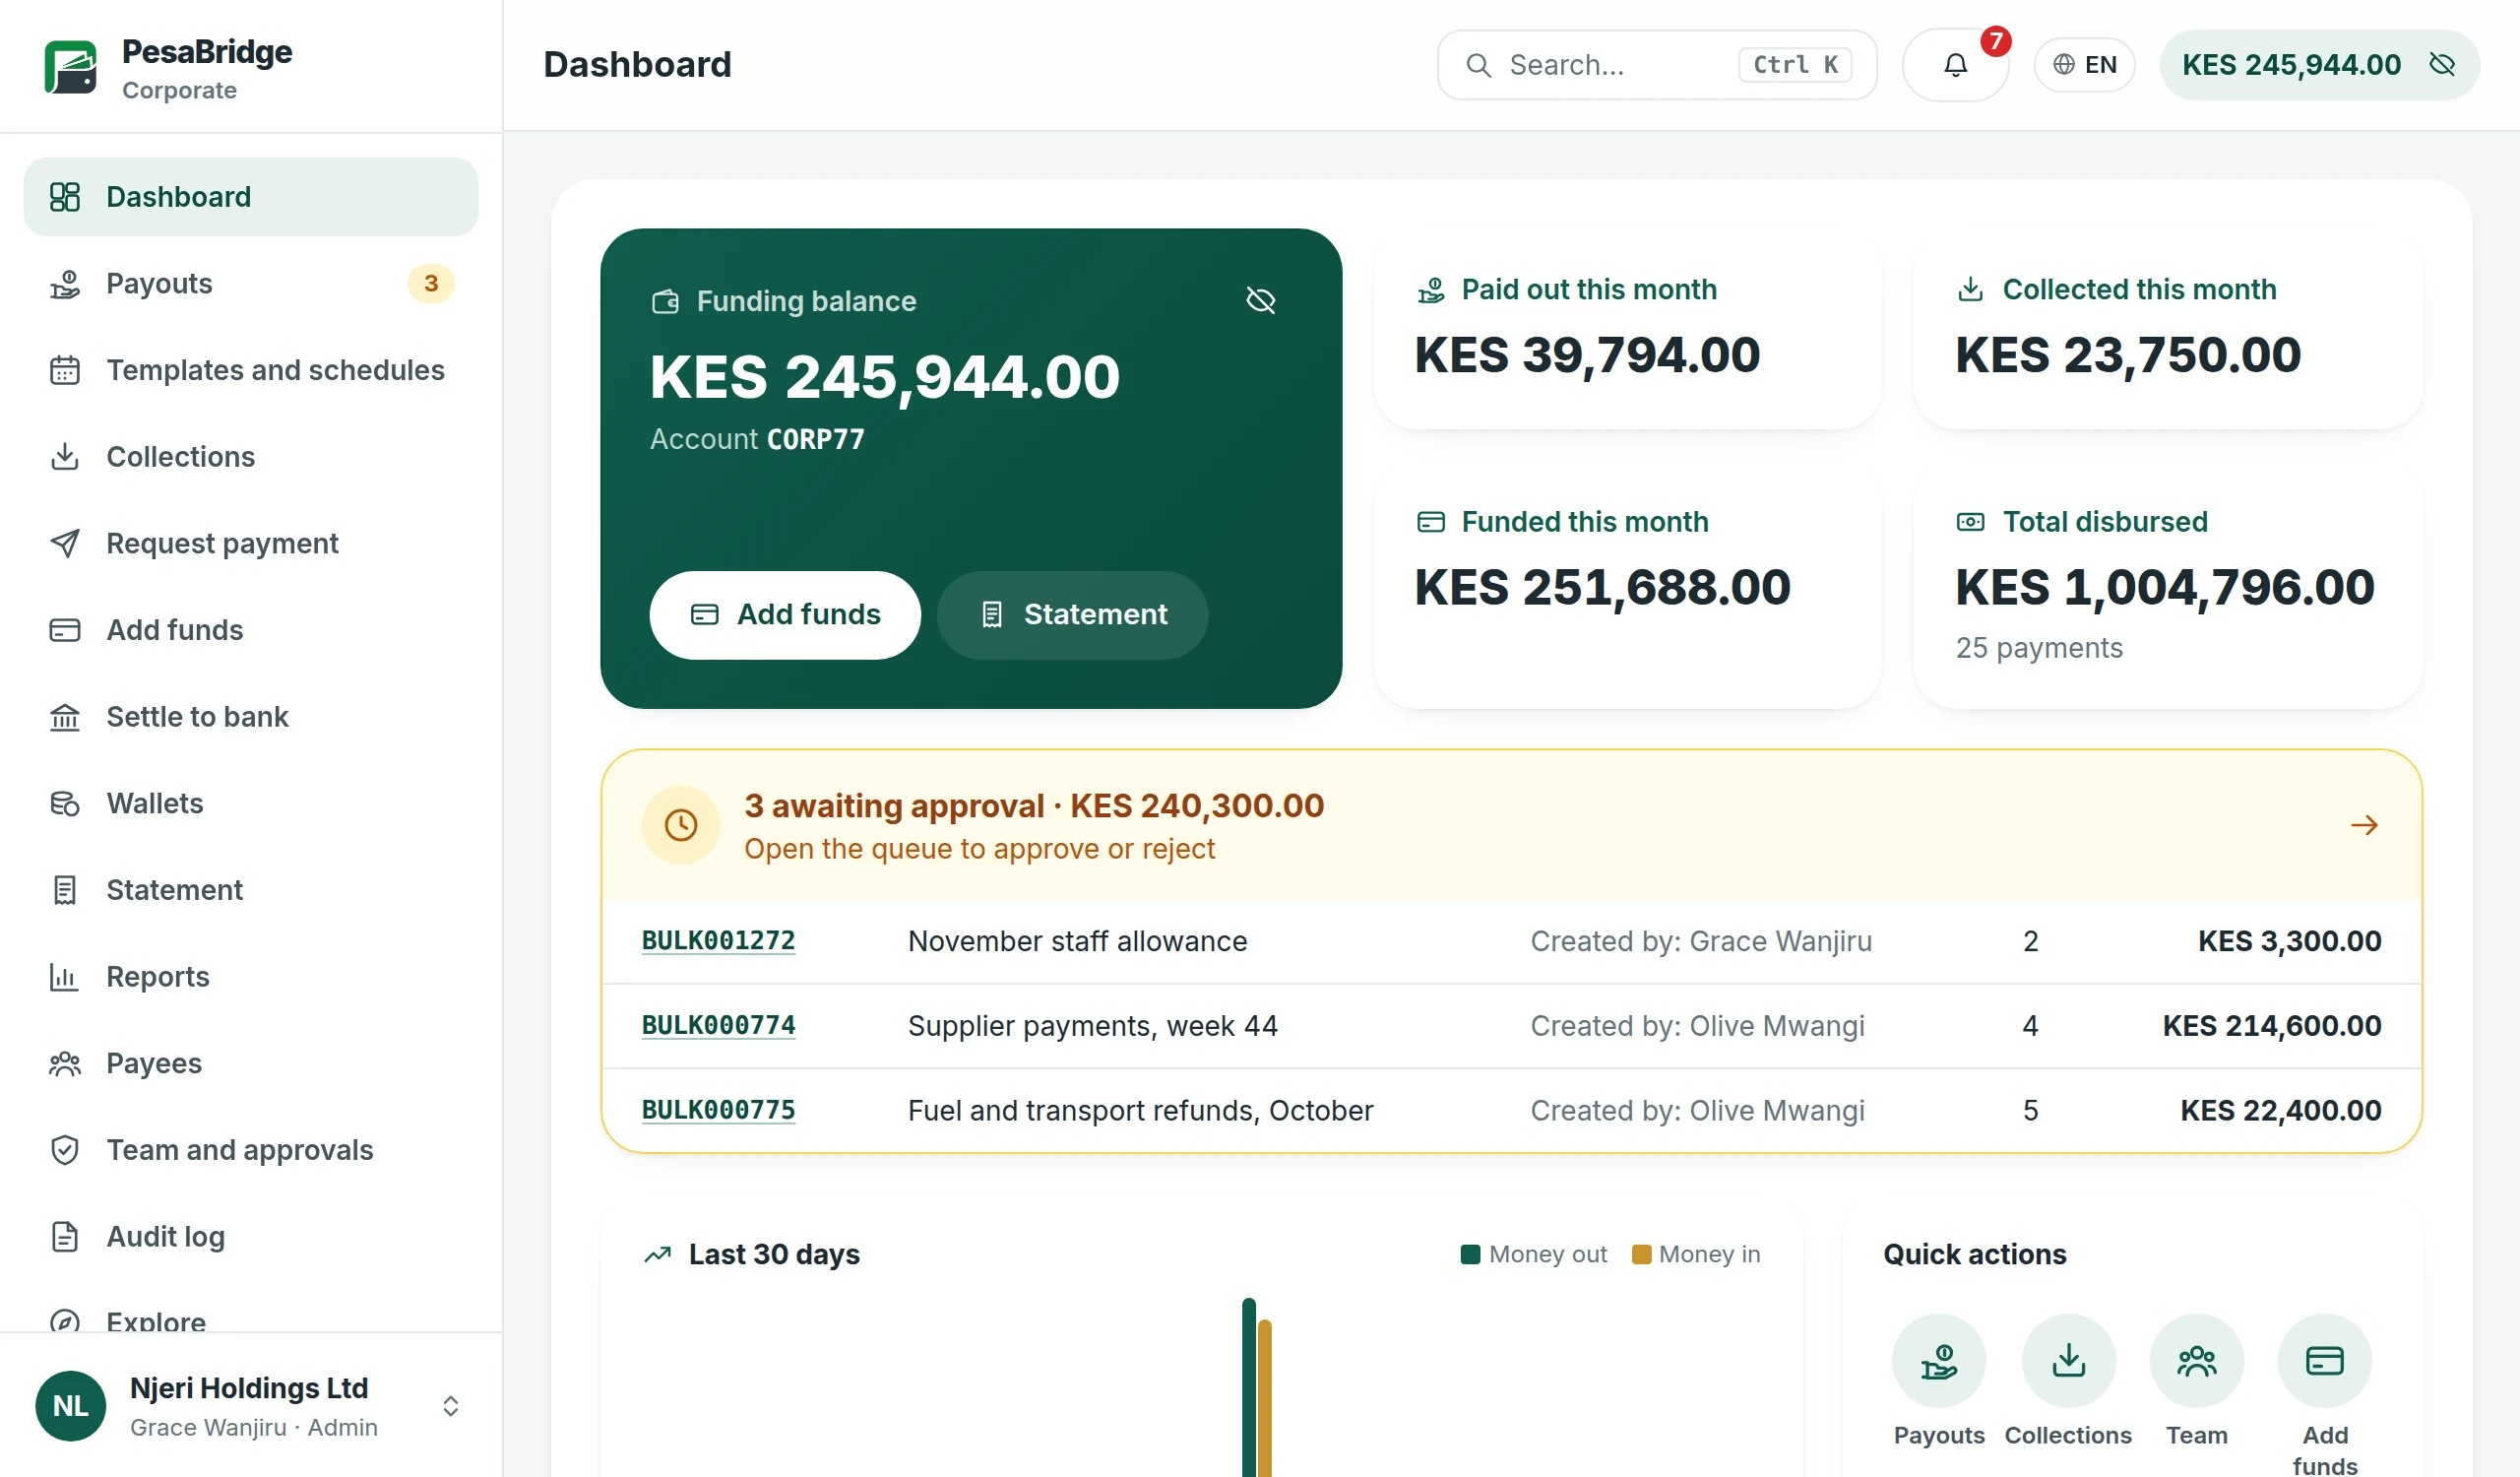
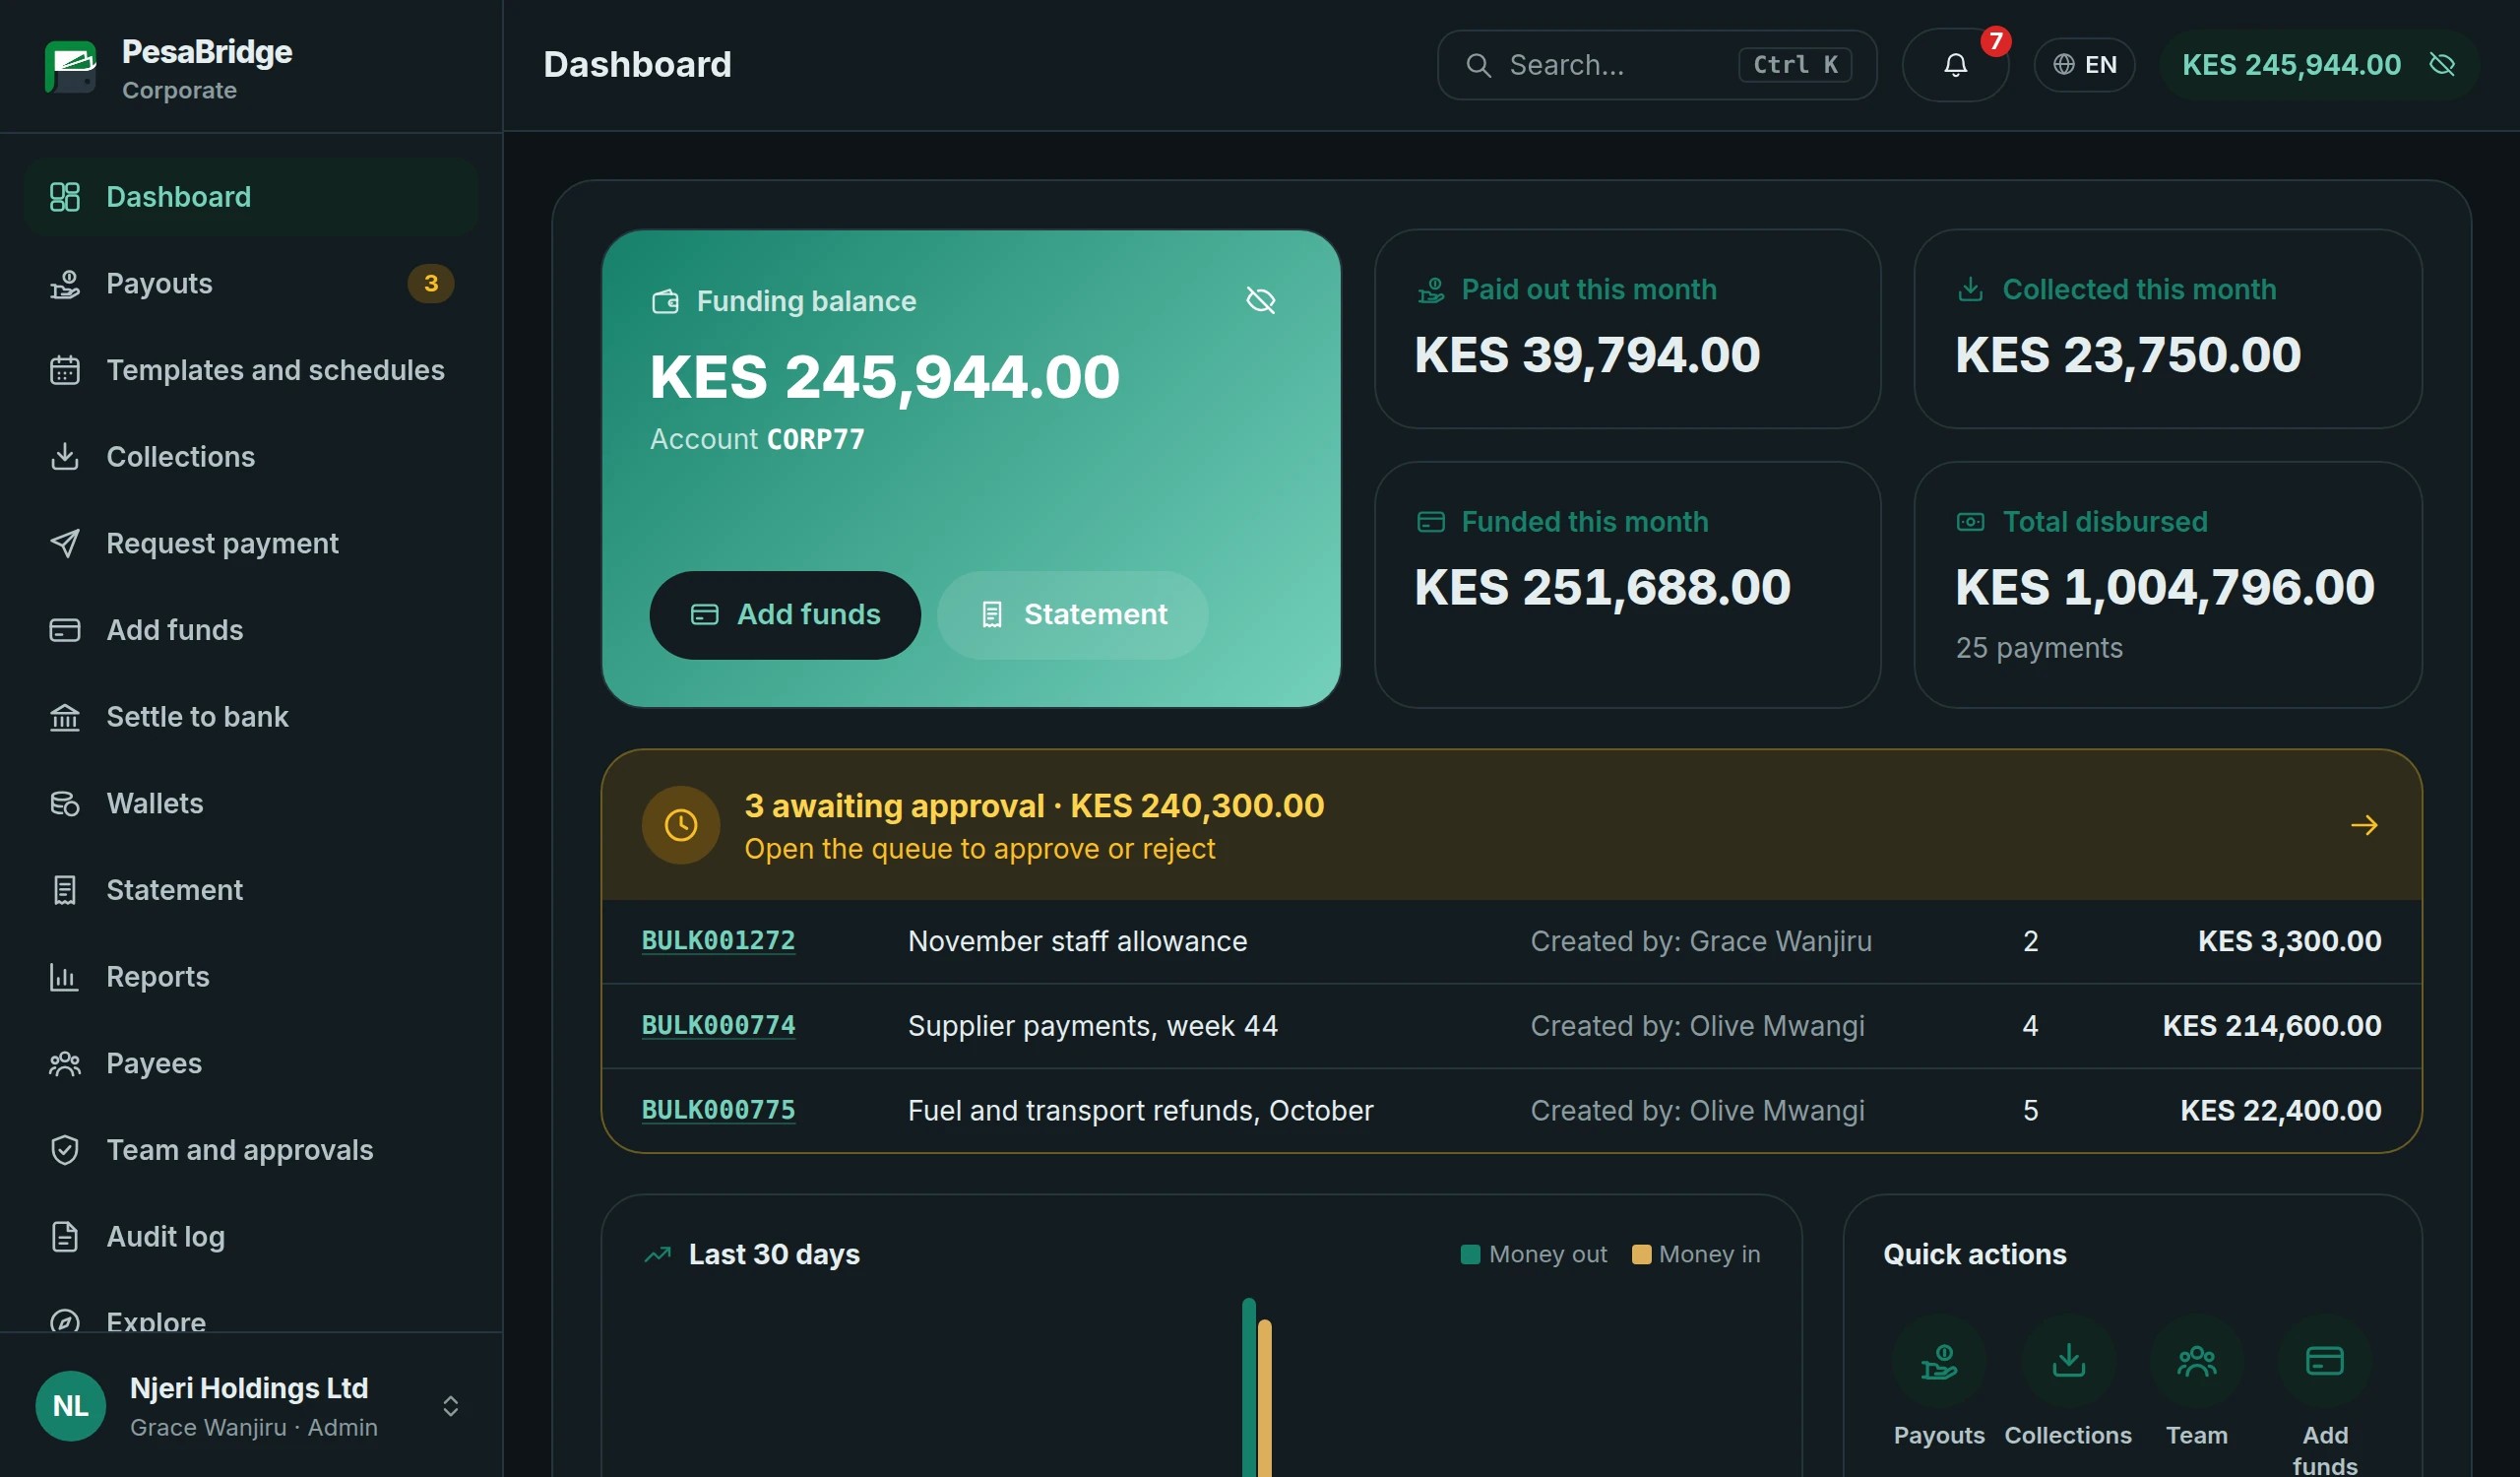
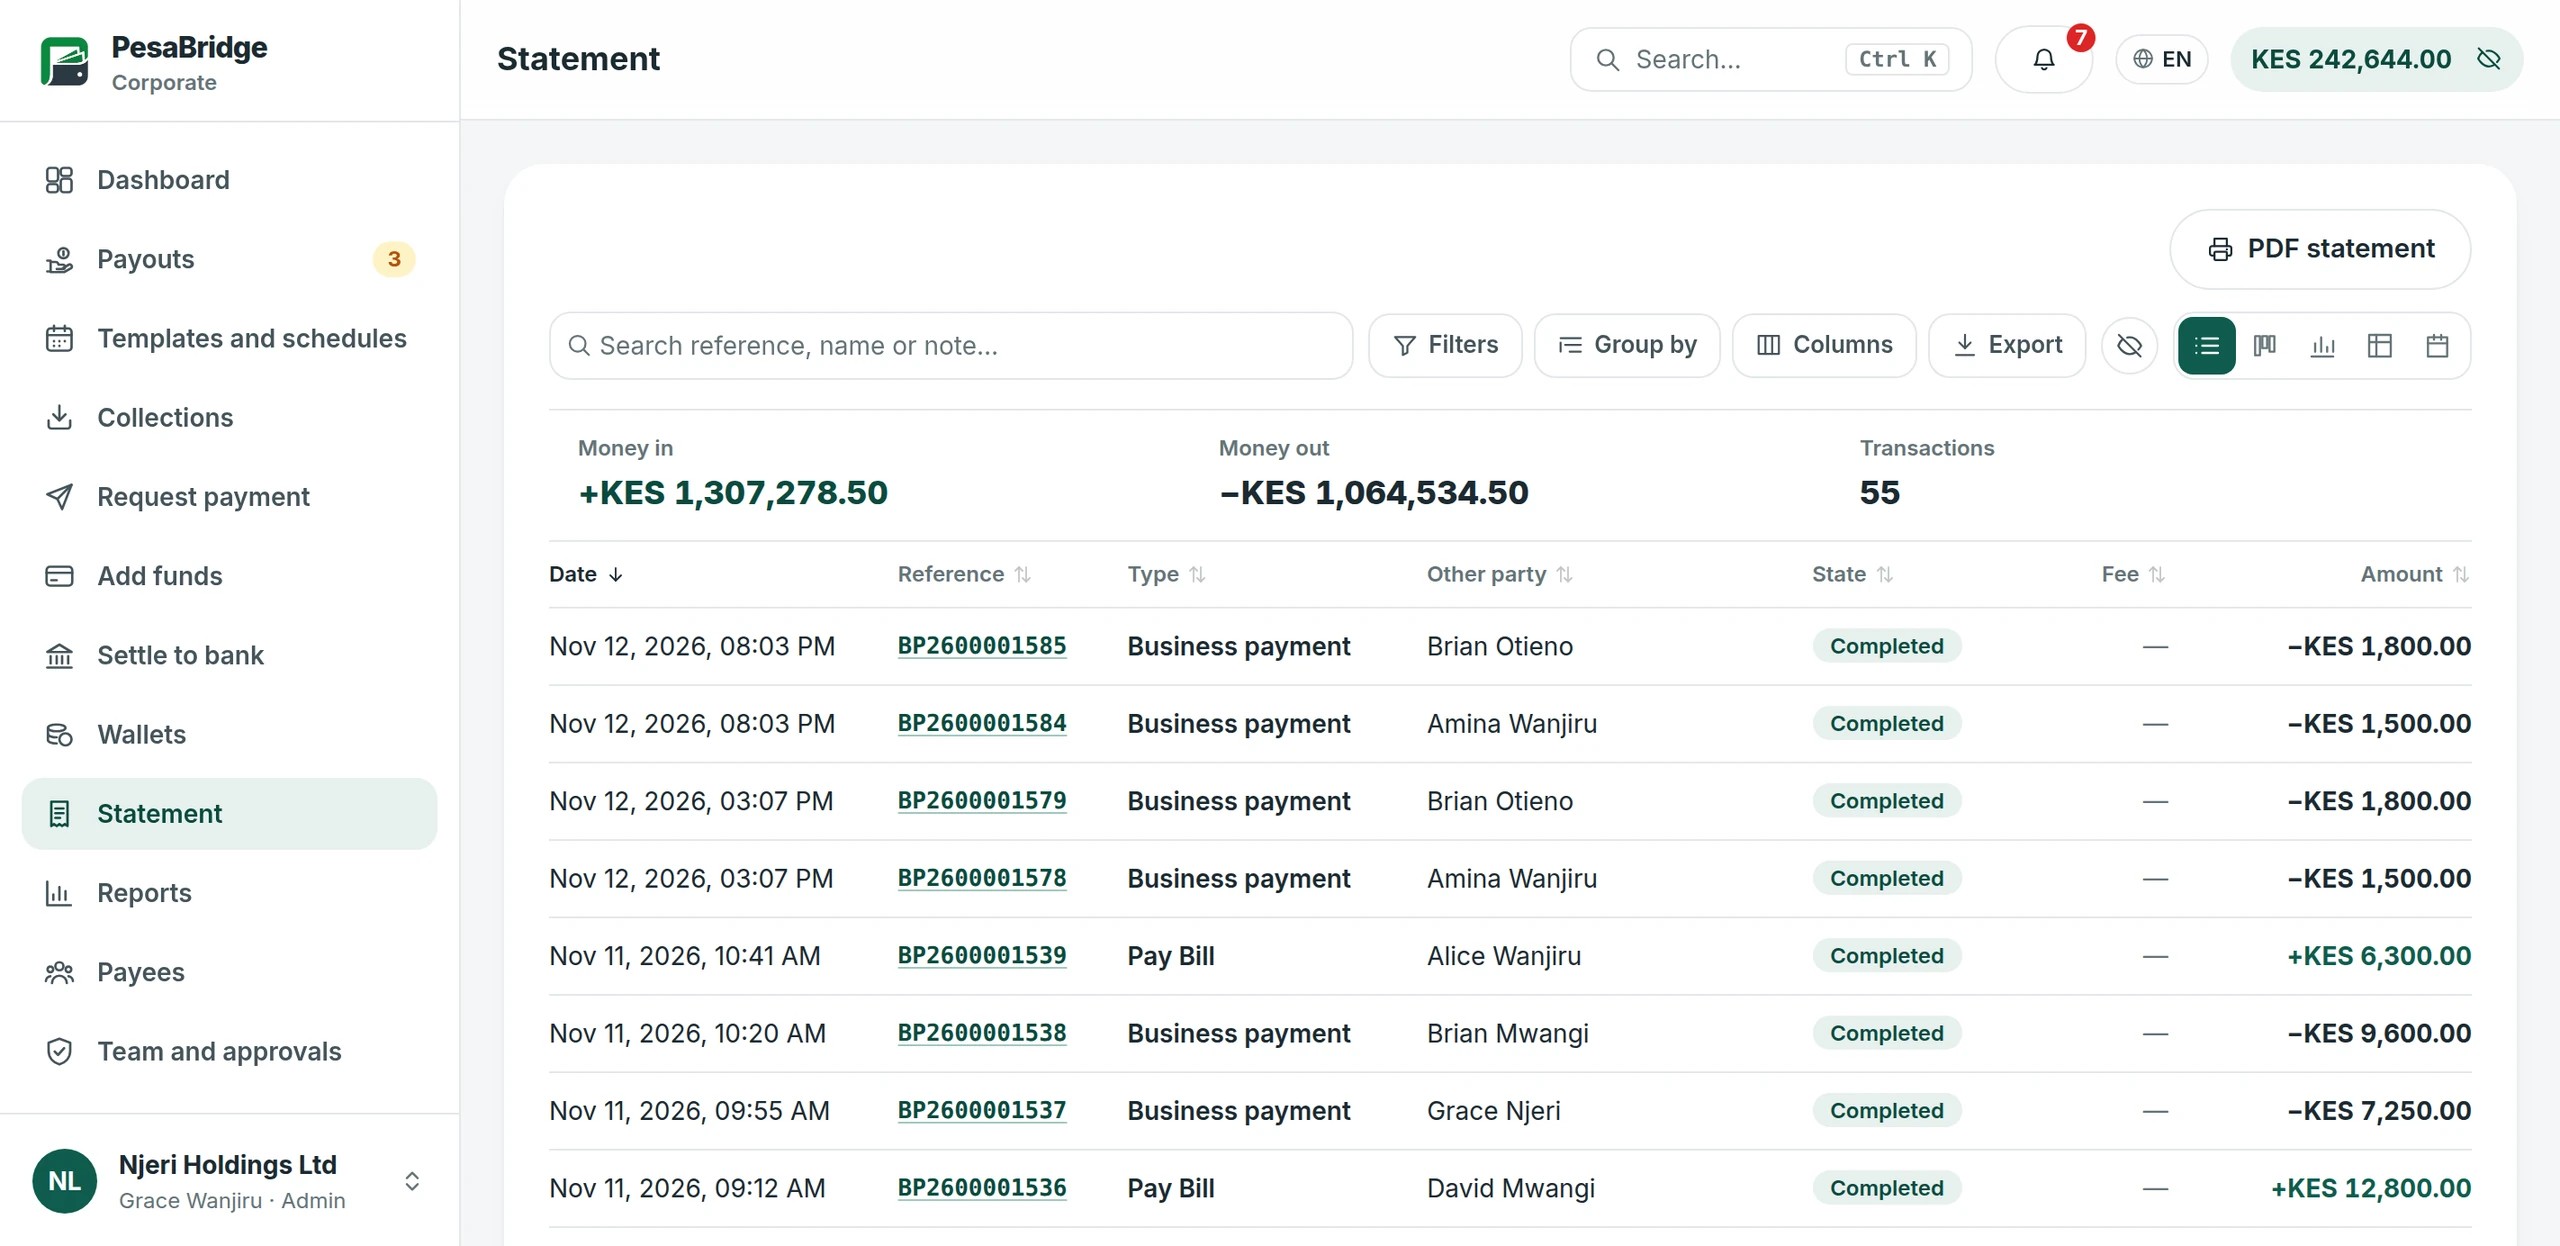
Companies fund their wallet from the bank, pay many people in one batch and collect what they are owed, on the corporate app and the corporate portal.
- Bulk payouts. Pick saved beneficiaries and pay salaries or suppliers in one batch.
- Maker and checker. One person prepares a payout and another approves it, from the portal or the app.
- Fund and collect. Top up the corporate wallet from the bank and receive payments from customers.
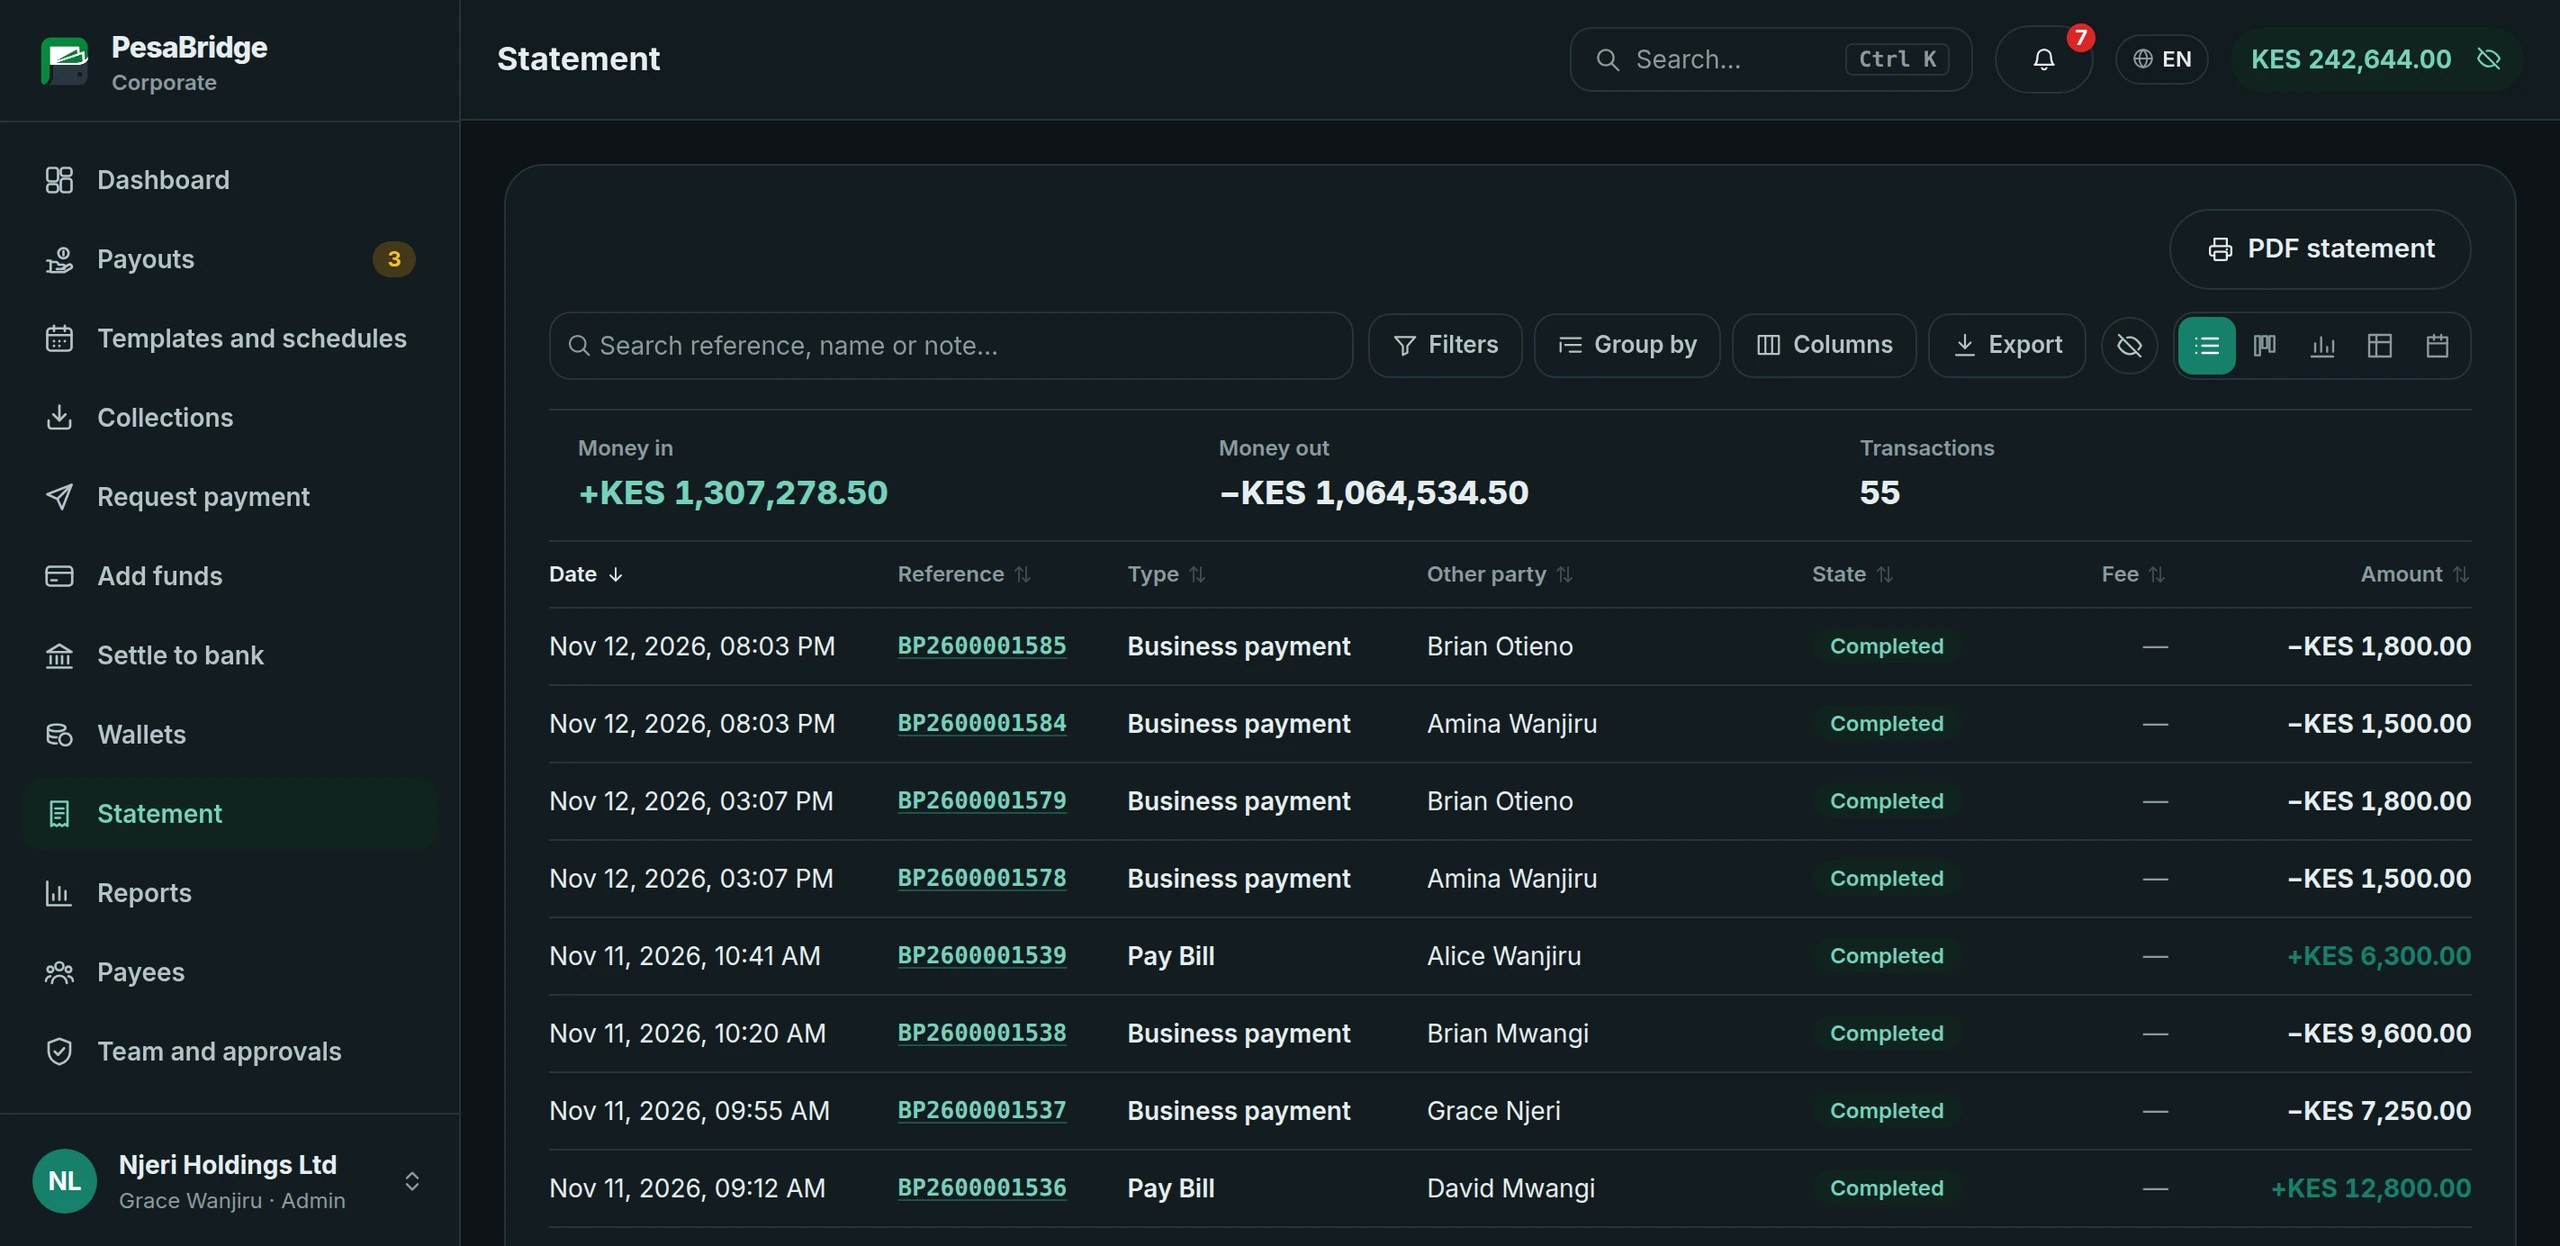
- Statements. Every payout and collection on a statement your finance team can check.
Mini apps
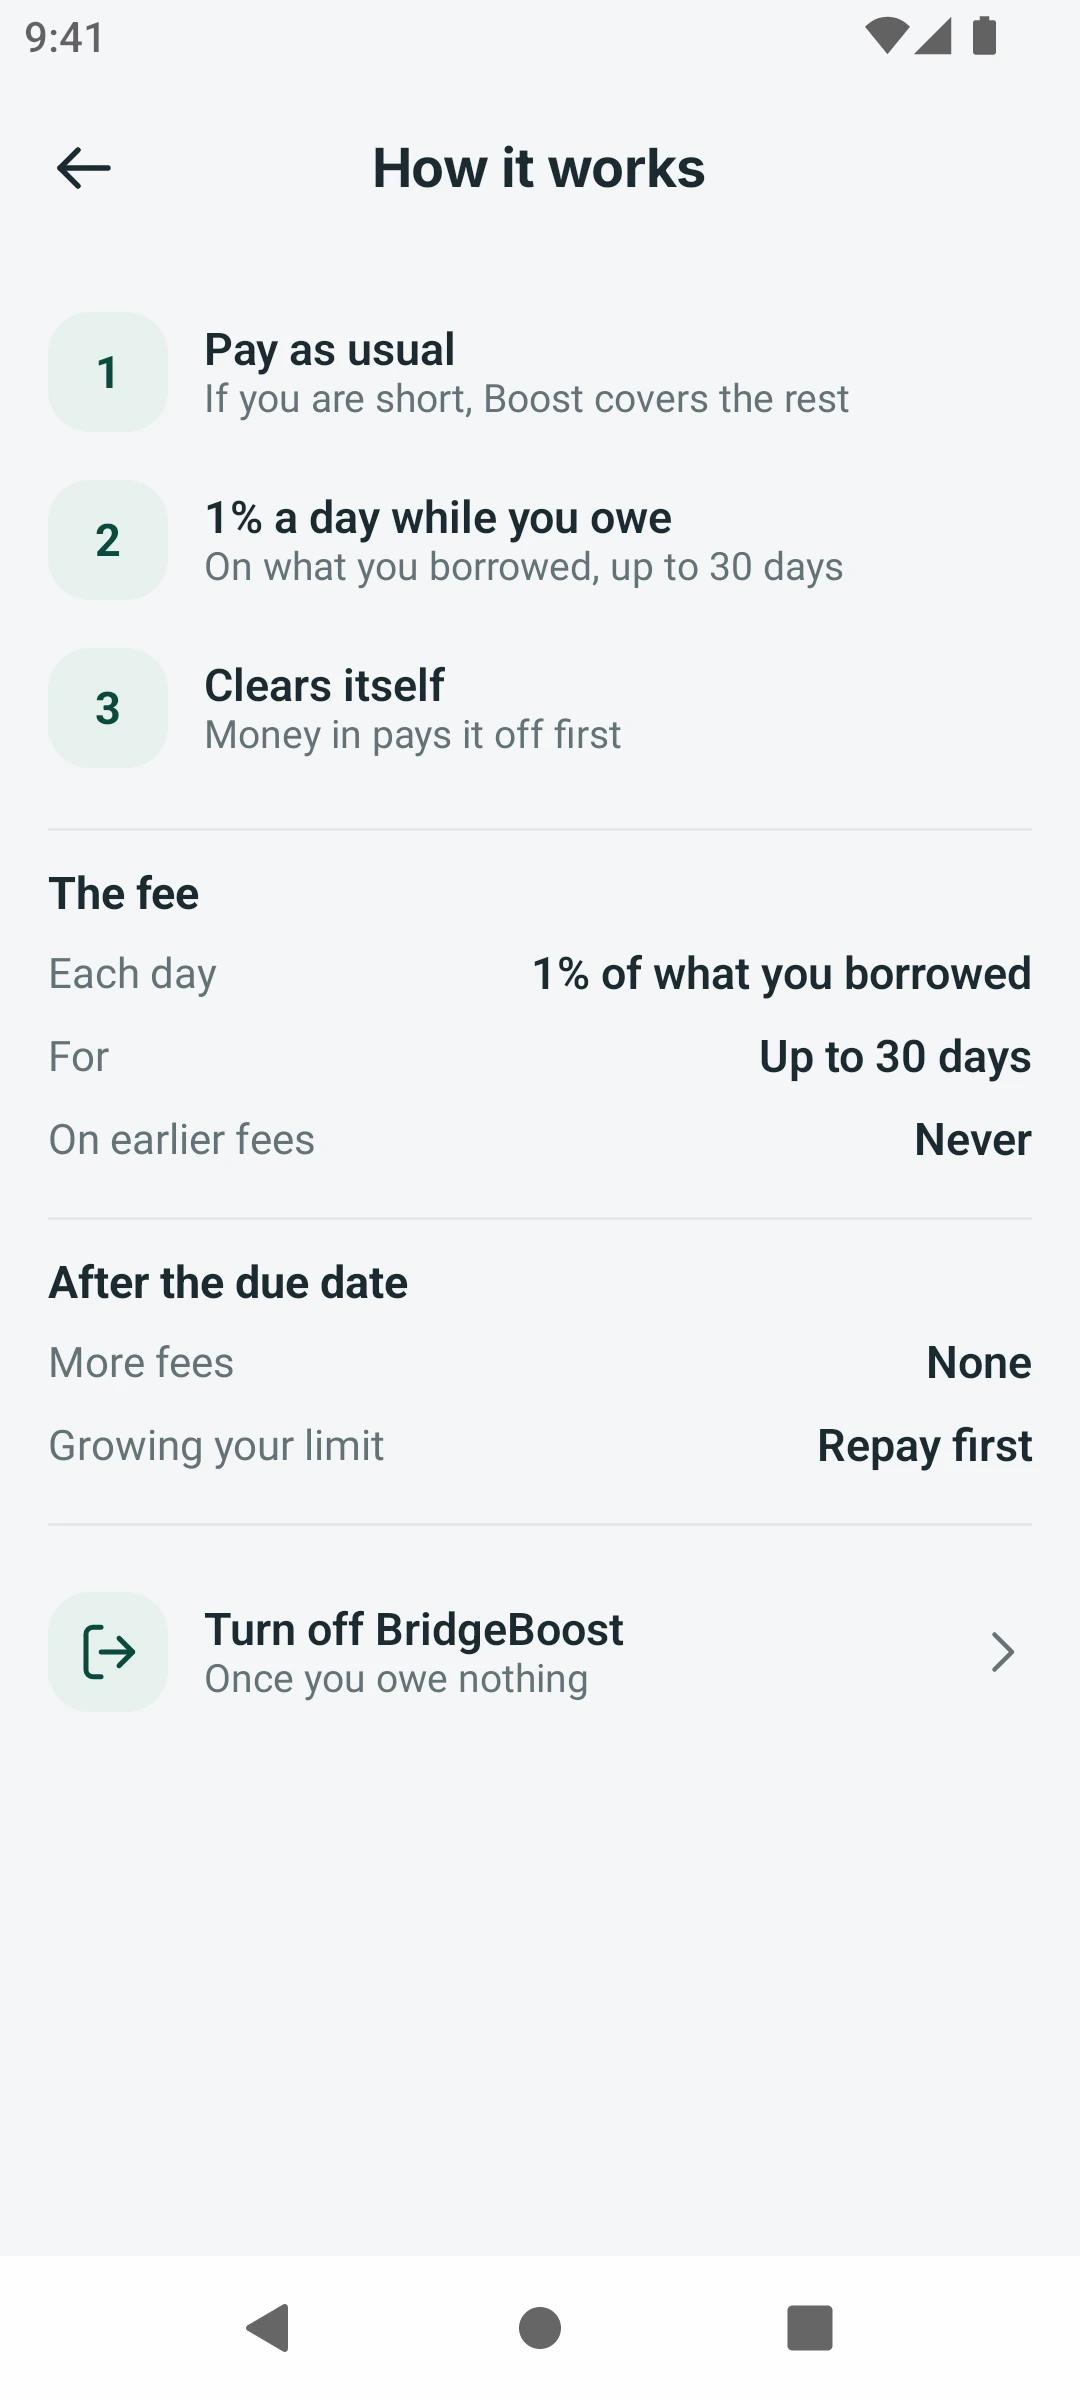
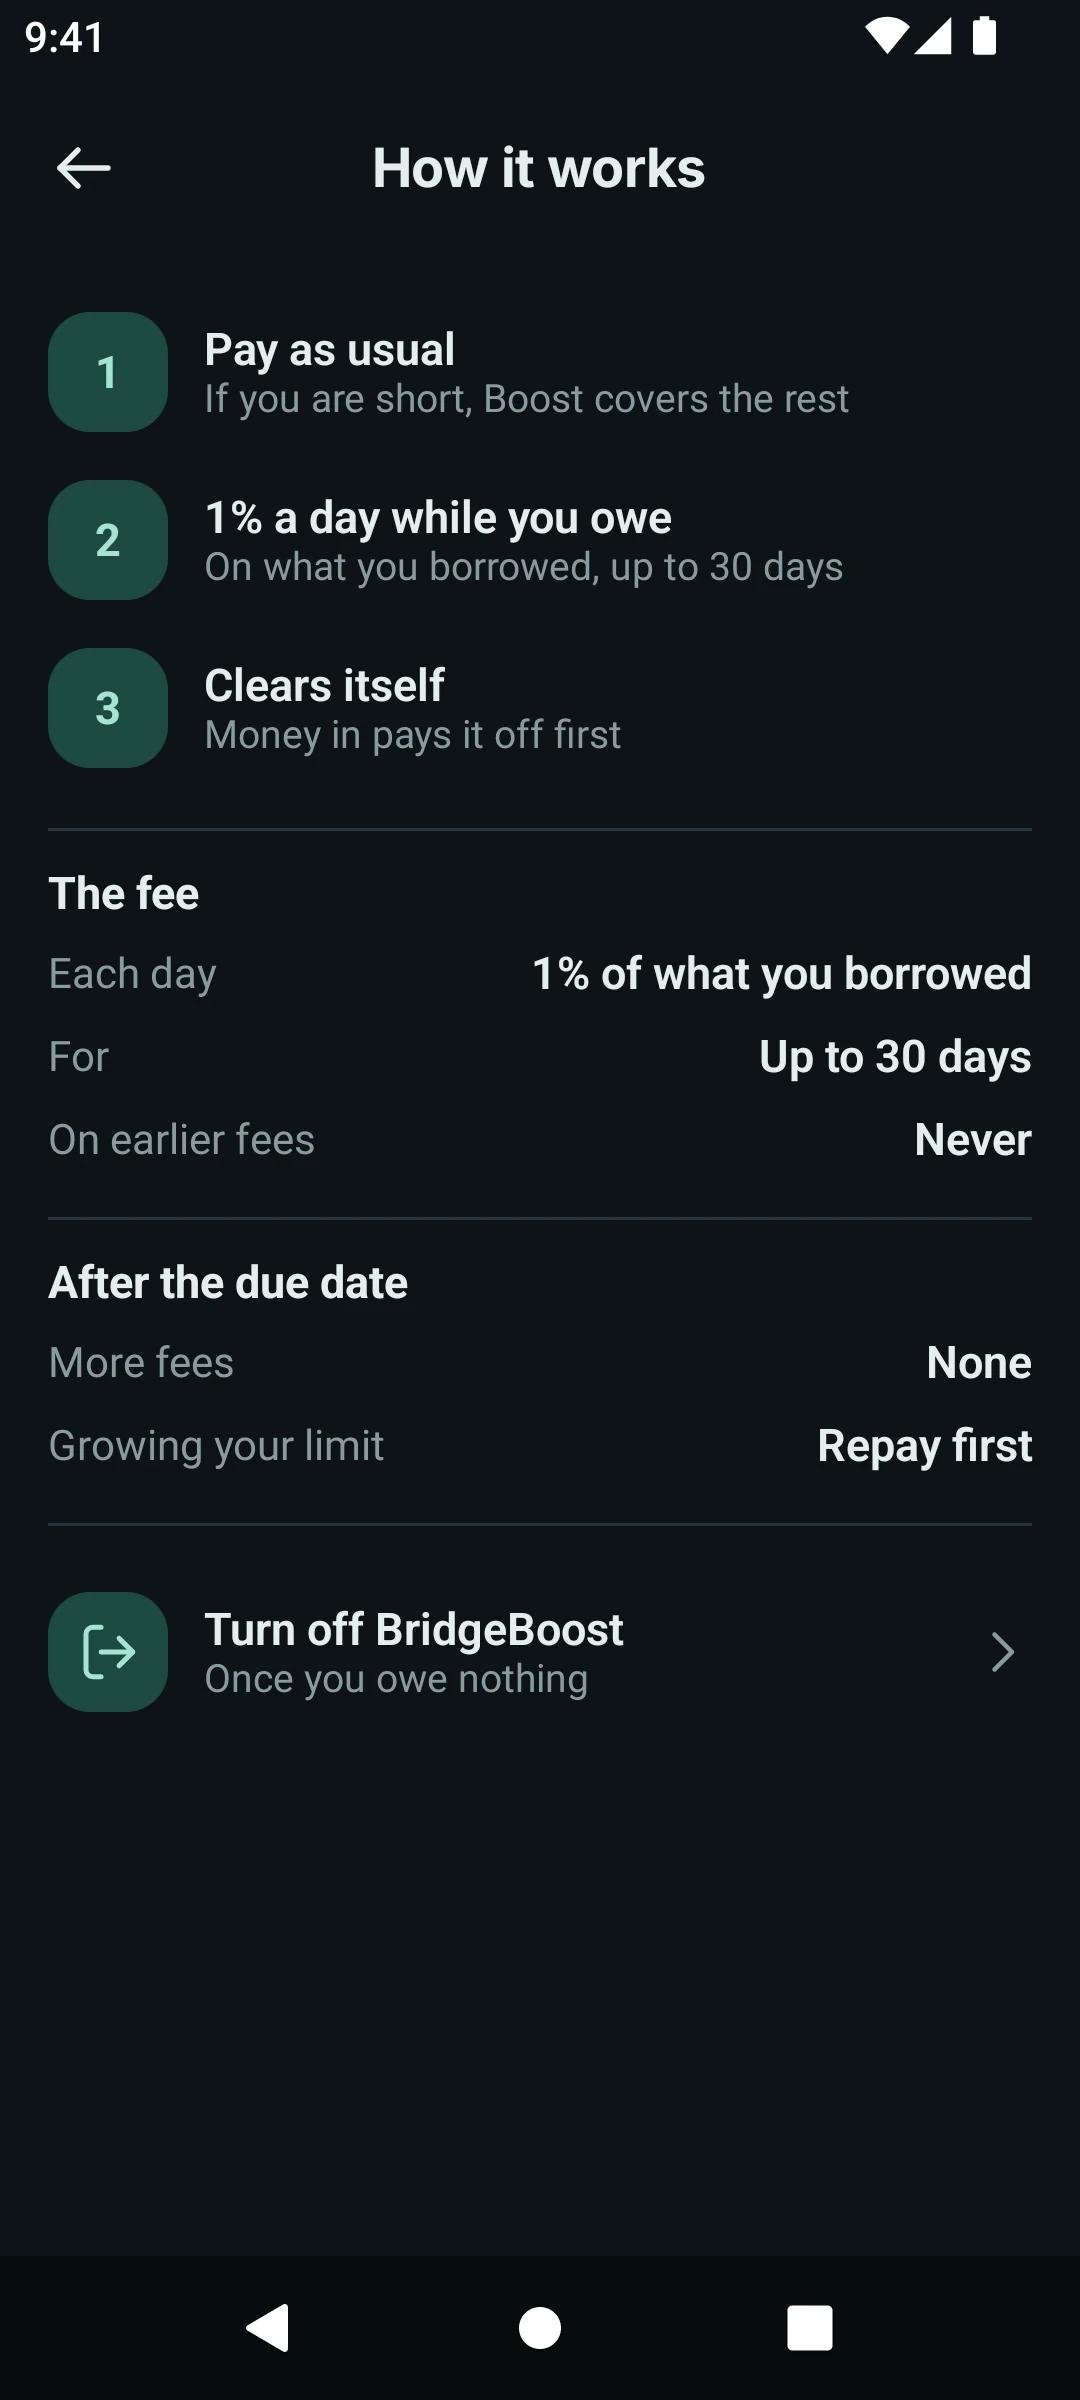
Every service behind the same PIN
Savings, credit, insurance, bundles and partner services open inside the wallet, so customers never juggle ten apps or ten passwords.
At the core
One ledger. Every transaction accounted for.
Every app, agent, till and payout writes to the same double-entry ledger. Postings must balance and cannot be deleted, so your finance team can sign the books.
- Balanced by construction. A deposit debits the agent's float and credits the customer's wallet by the same amount. No code path creates or destroys value.
- Charged once, never twice. Each transaction carries an idempotency key, so a retried request settles one time only.
- One reversal engine. Undo a send, a Pay Bill, an agent deposit or a payout with mirror entries. The original stays on record.
- 27 transaction types, one book. Sends, Pay Bill, agent cash, payouts, loans, savings, fees and commissions all post to the same ledger.
- Accounting that closes. Every settled transaction lands in accounting, with a journal per rail, tax on fees split out per country and a month-end close.
Compliance built in
KYC, limits and audit a regulator accepts
Compliance is not a screen added at the end. Balance, limits and KYC tier are checked before a transaction posts, on every channel, and the rules follow your central bank.
- Checks at sign-up. ID reading, face match and a live-person check, plus sanctions and duplicate checks, through the identity connector.
- Your regulator's limits. 42 central bank profiles for Africa set the daily and monthly limits for each tier and the large-cash report threshold.
- Sanctions and AML. Screening against UN, OFAC, EU, UK and PEP lists, AML rules that flag unusual activity, and goAML export for the financial intelligence unit.
- Two people for sensitive actions. Unfreezing a wallet, resetting a PIN or issuing float needs a second approver, and nobody approves their own request.
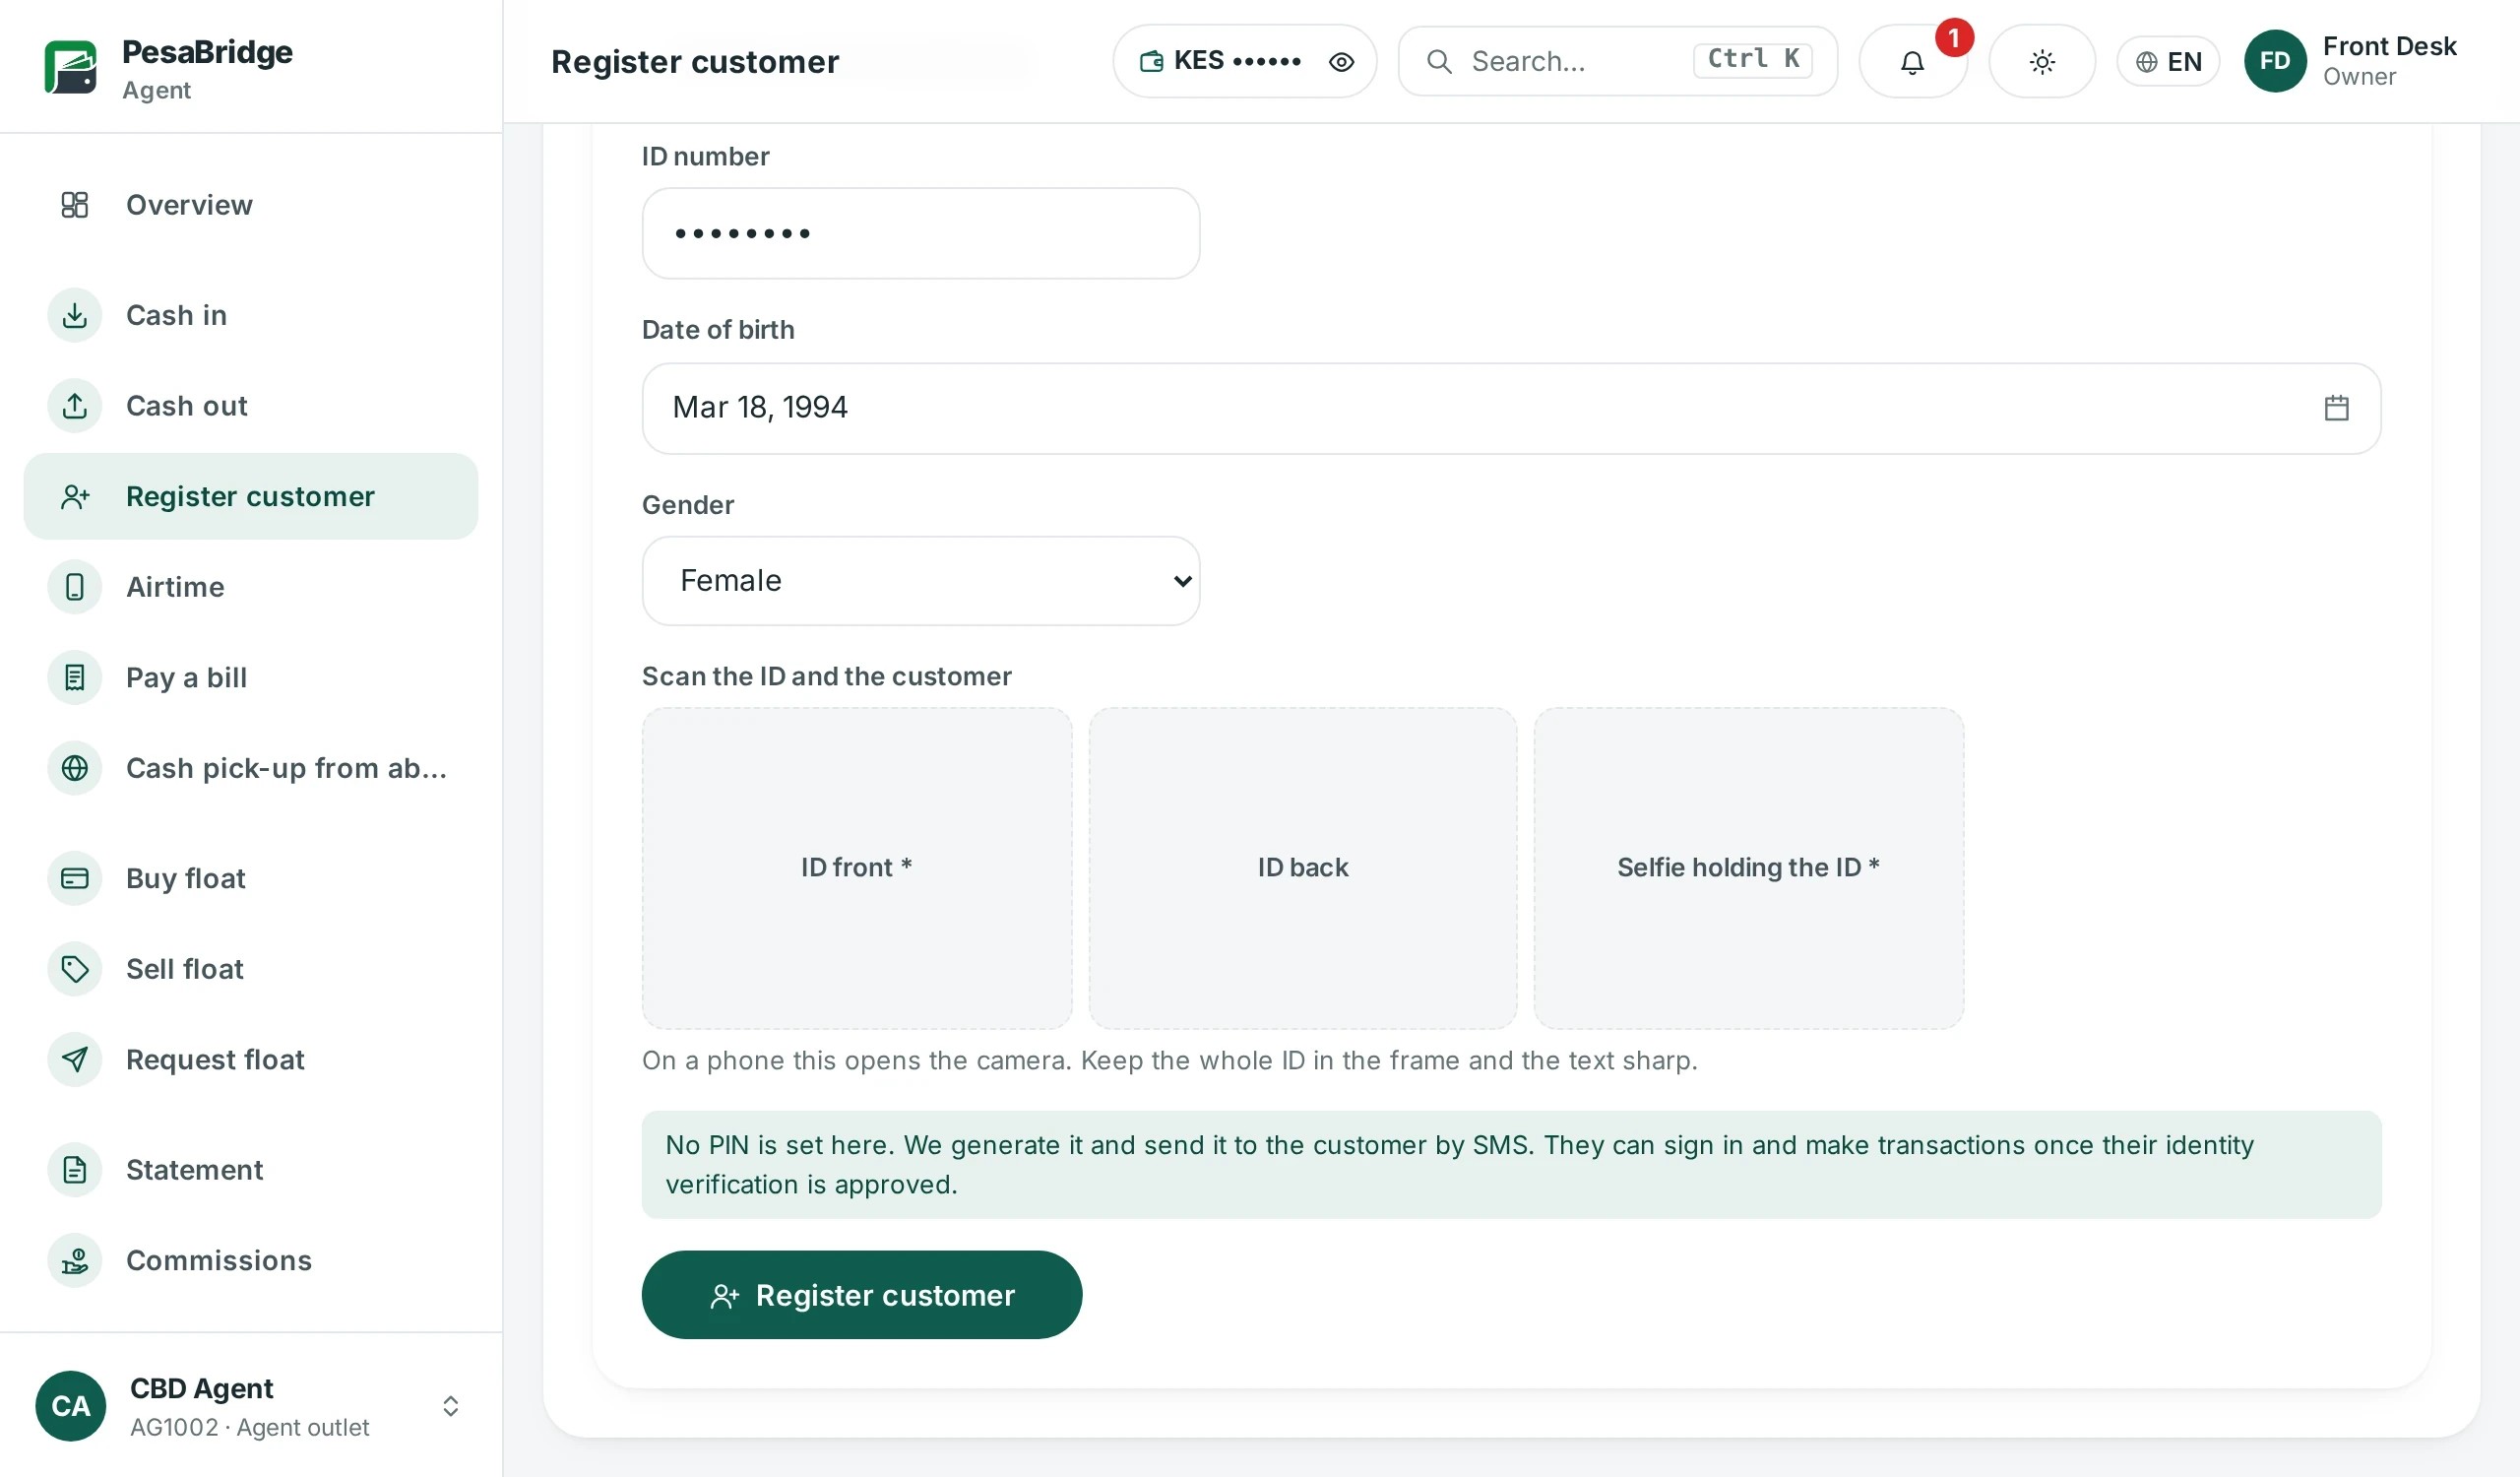
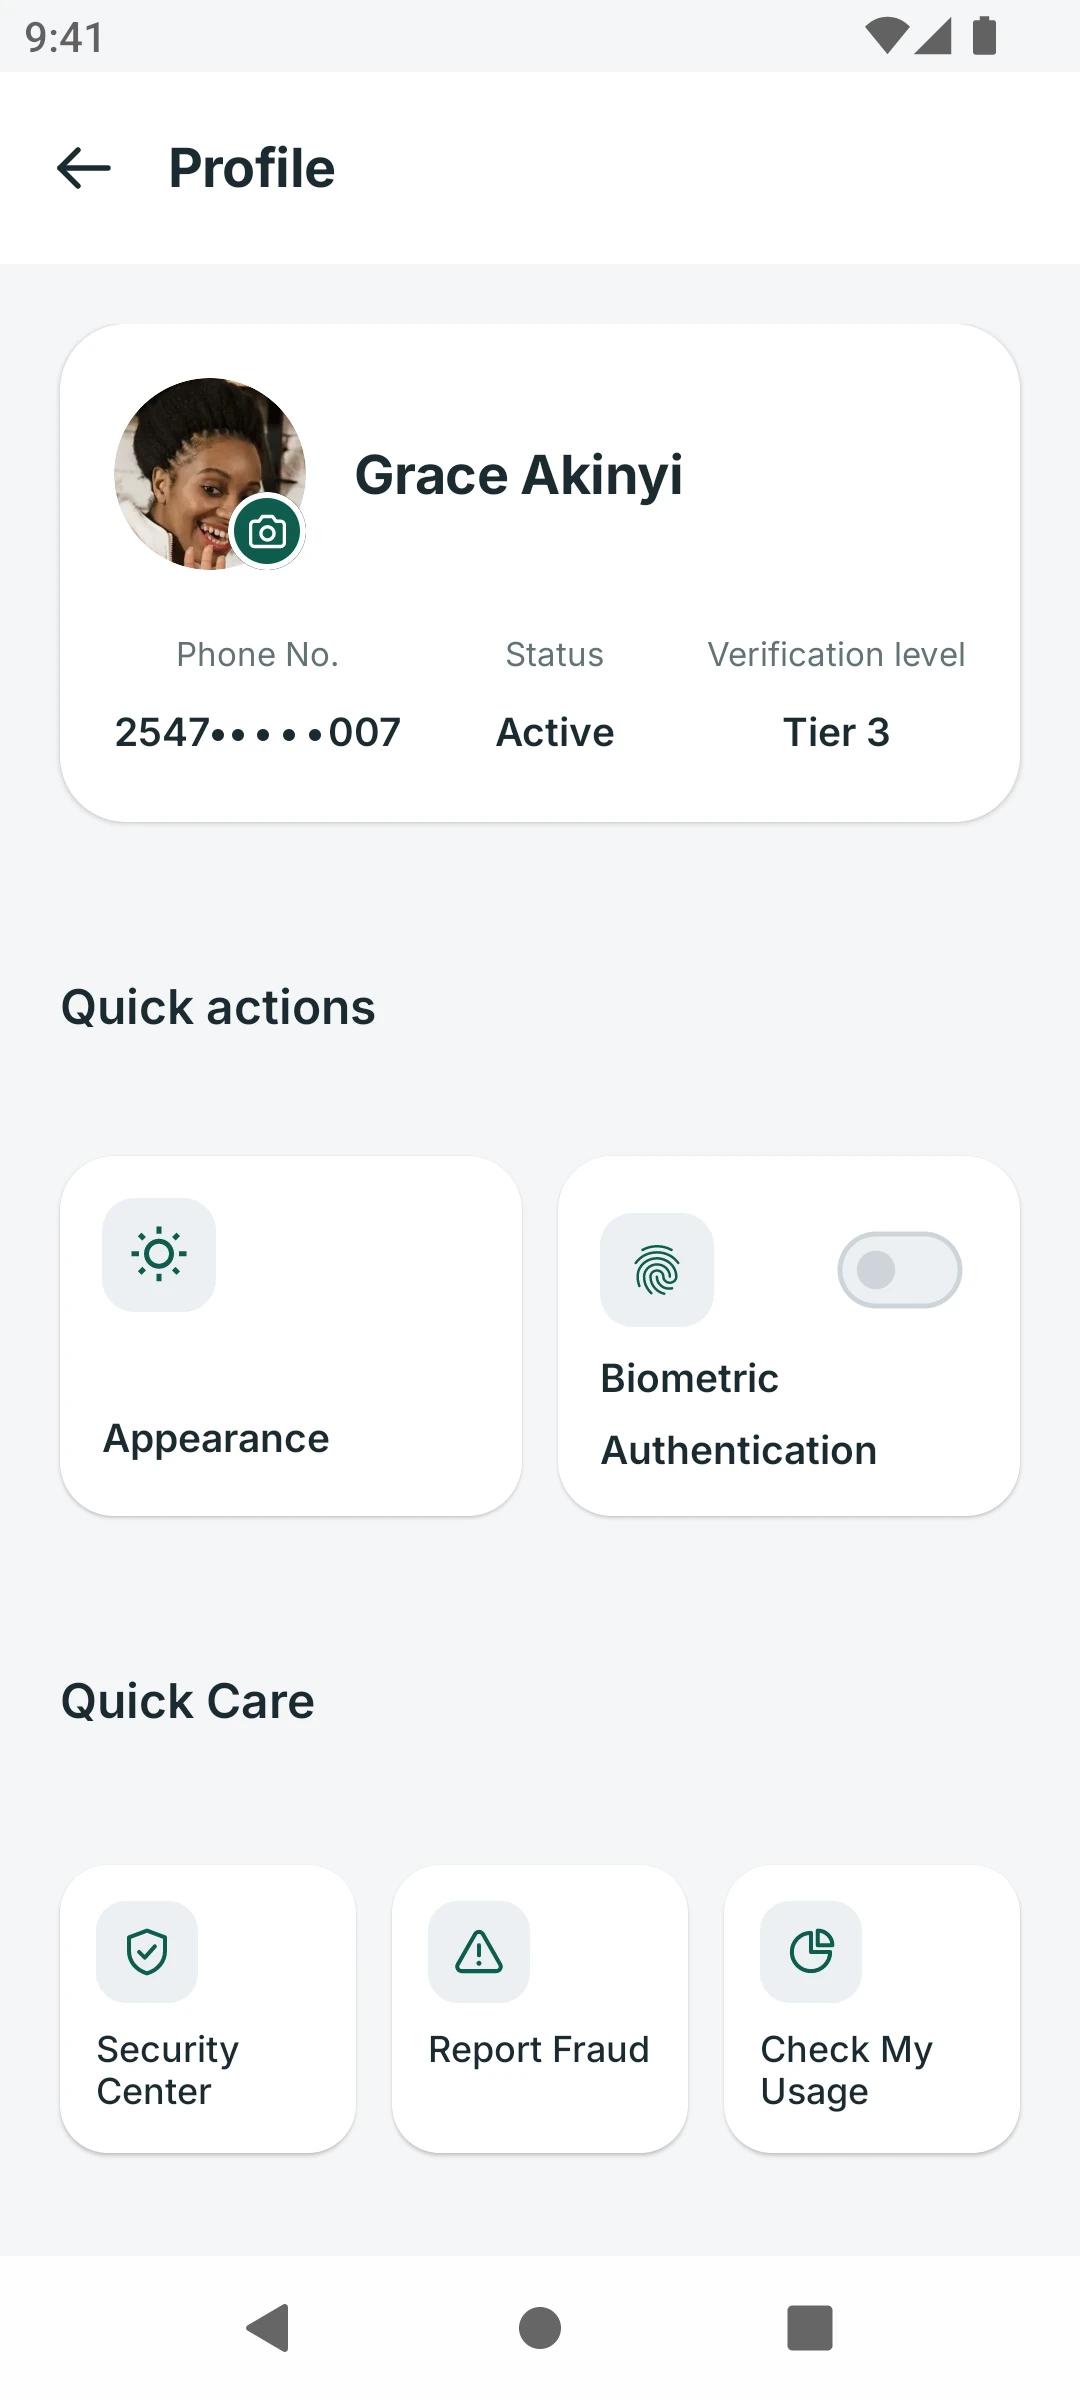
Tier 1 · Basic
A phone number and basic details, low limits.
Tier 2 · Verified
ID checked, higher daily and monthly limits.
Tier 3 · Enhanced
Full checks, the highest limits your regulator allows.
White-label
Your name on every app, portal and shortcode
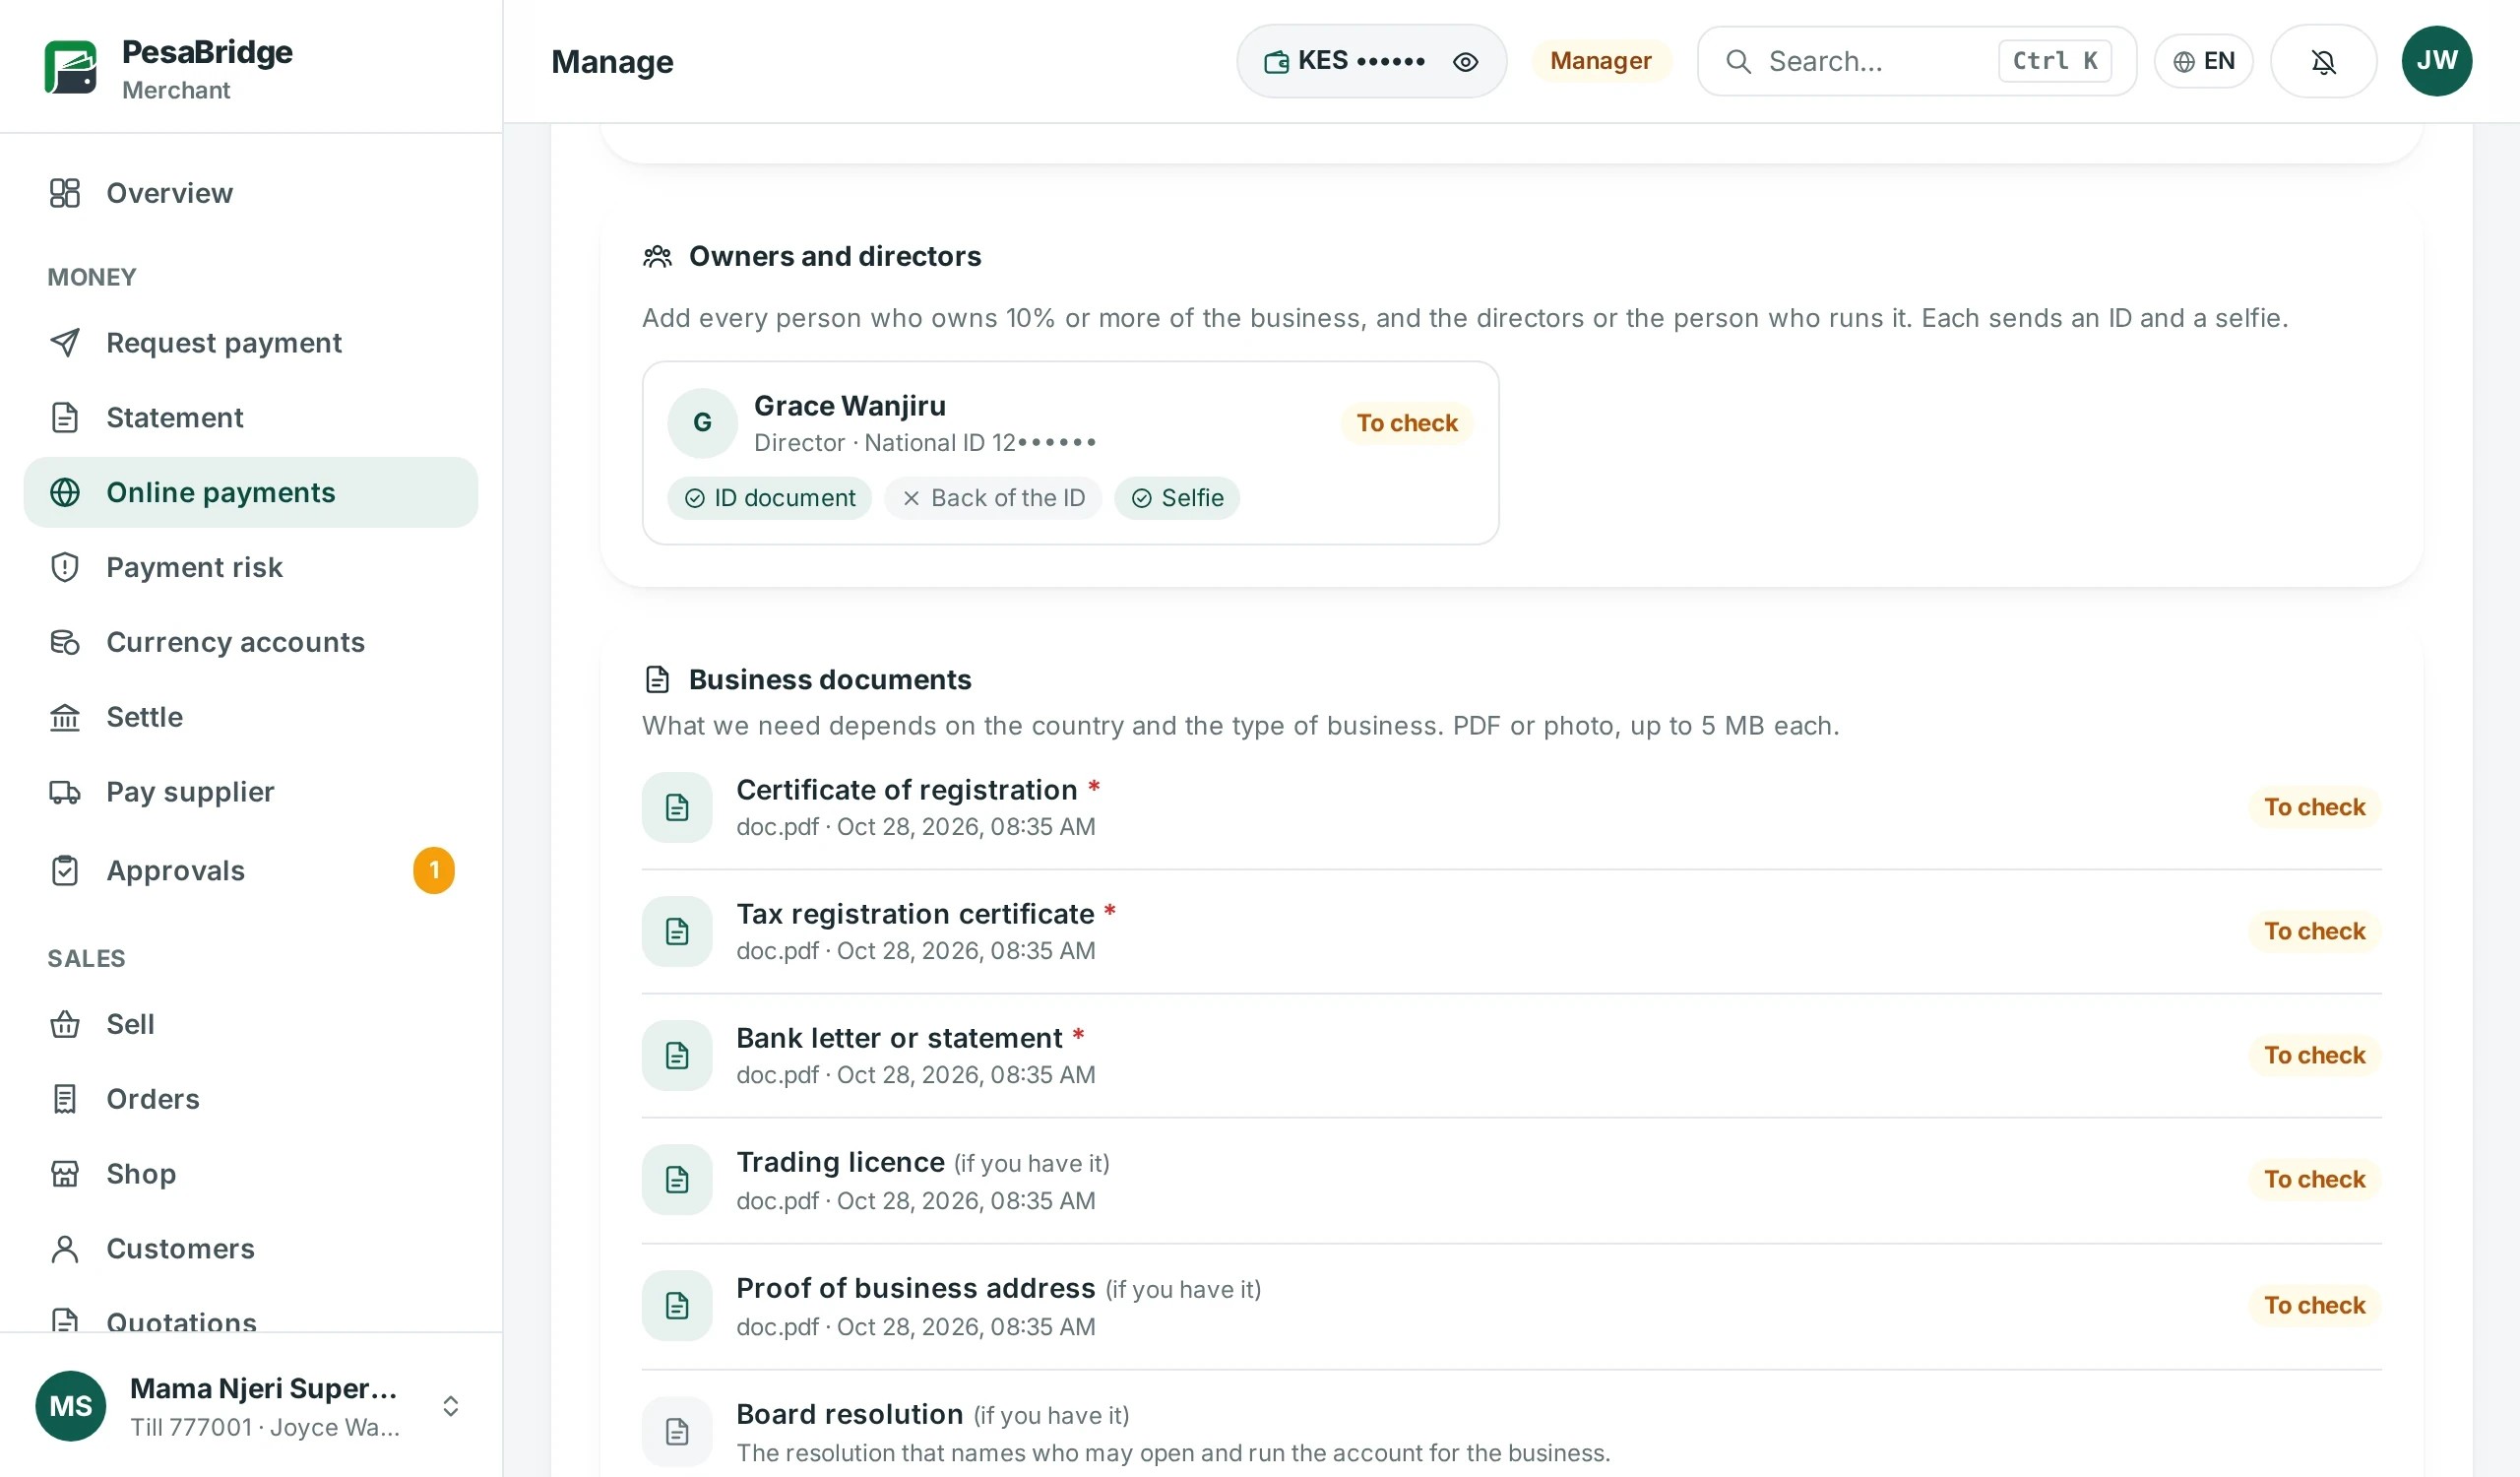
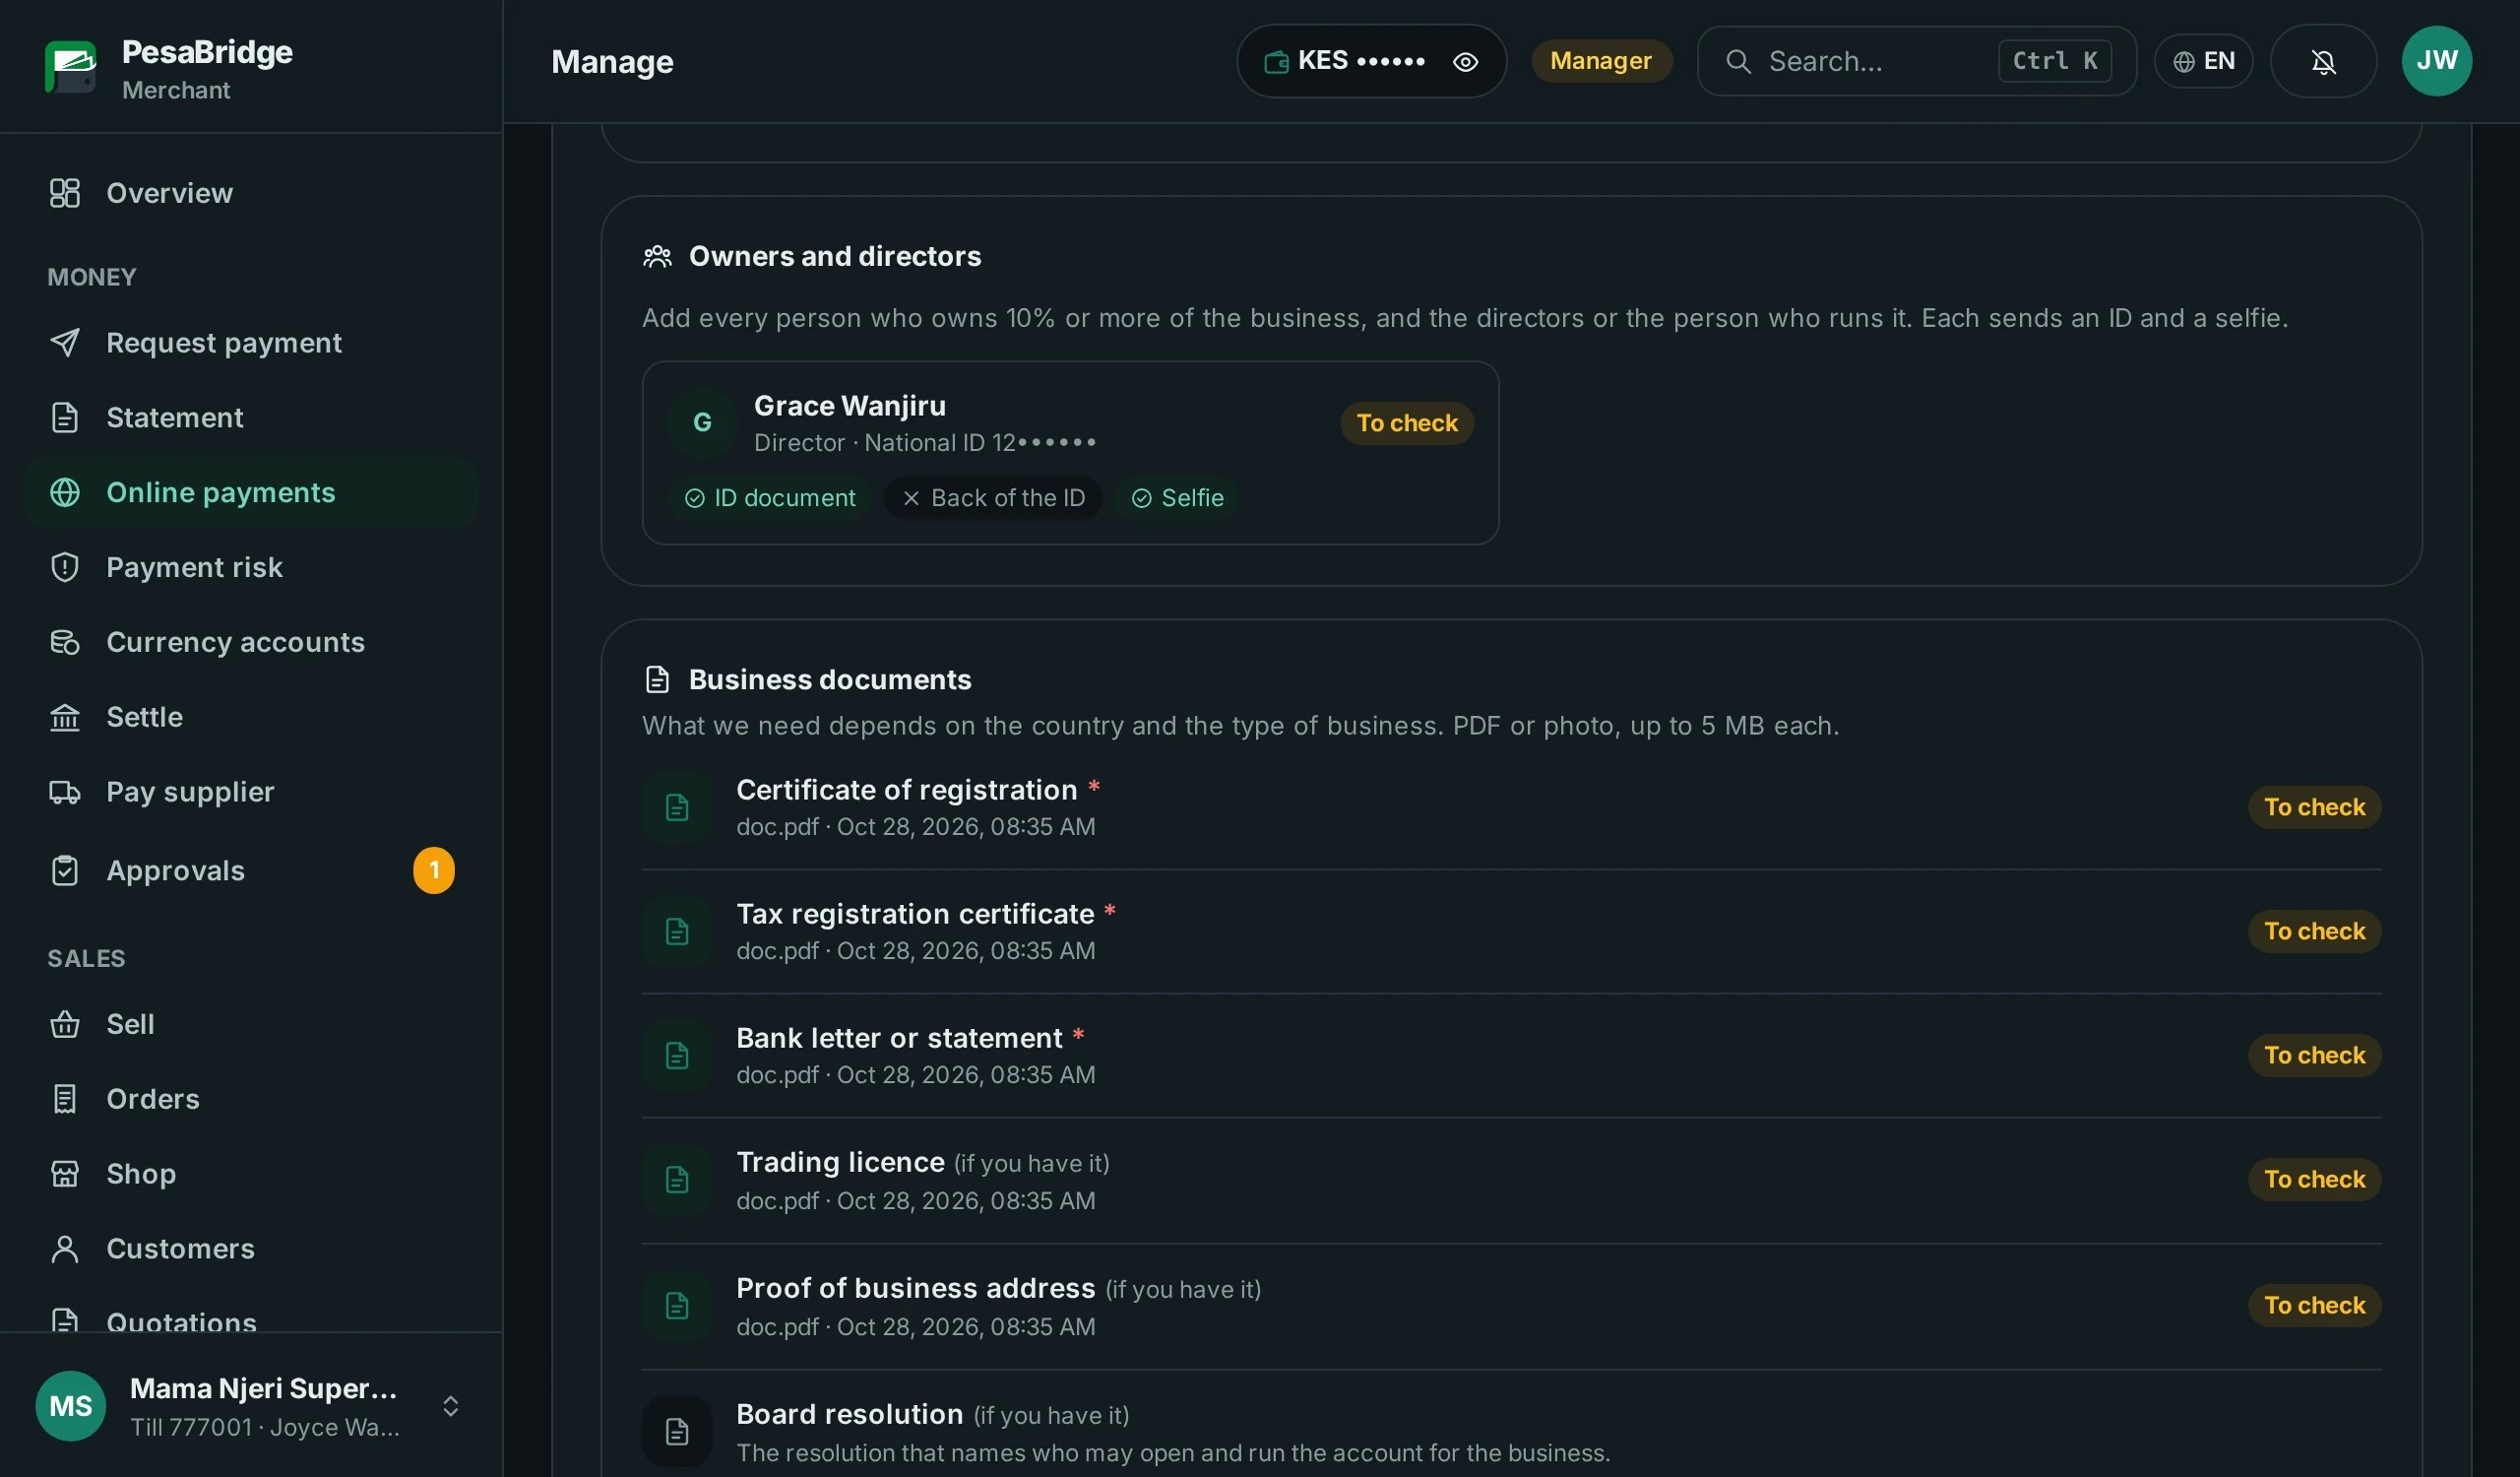
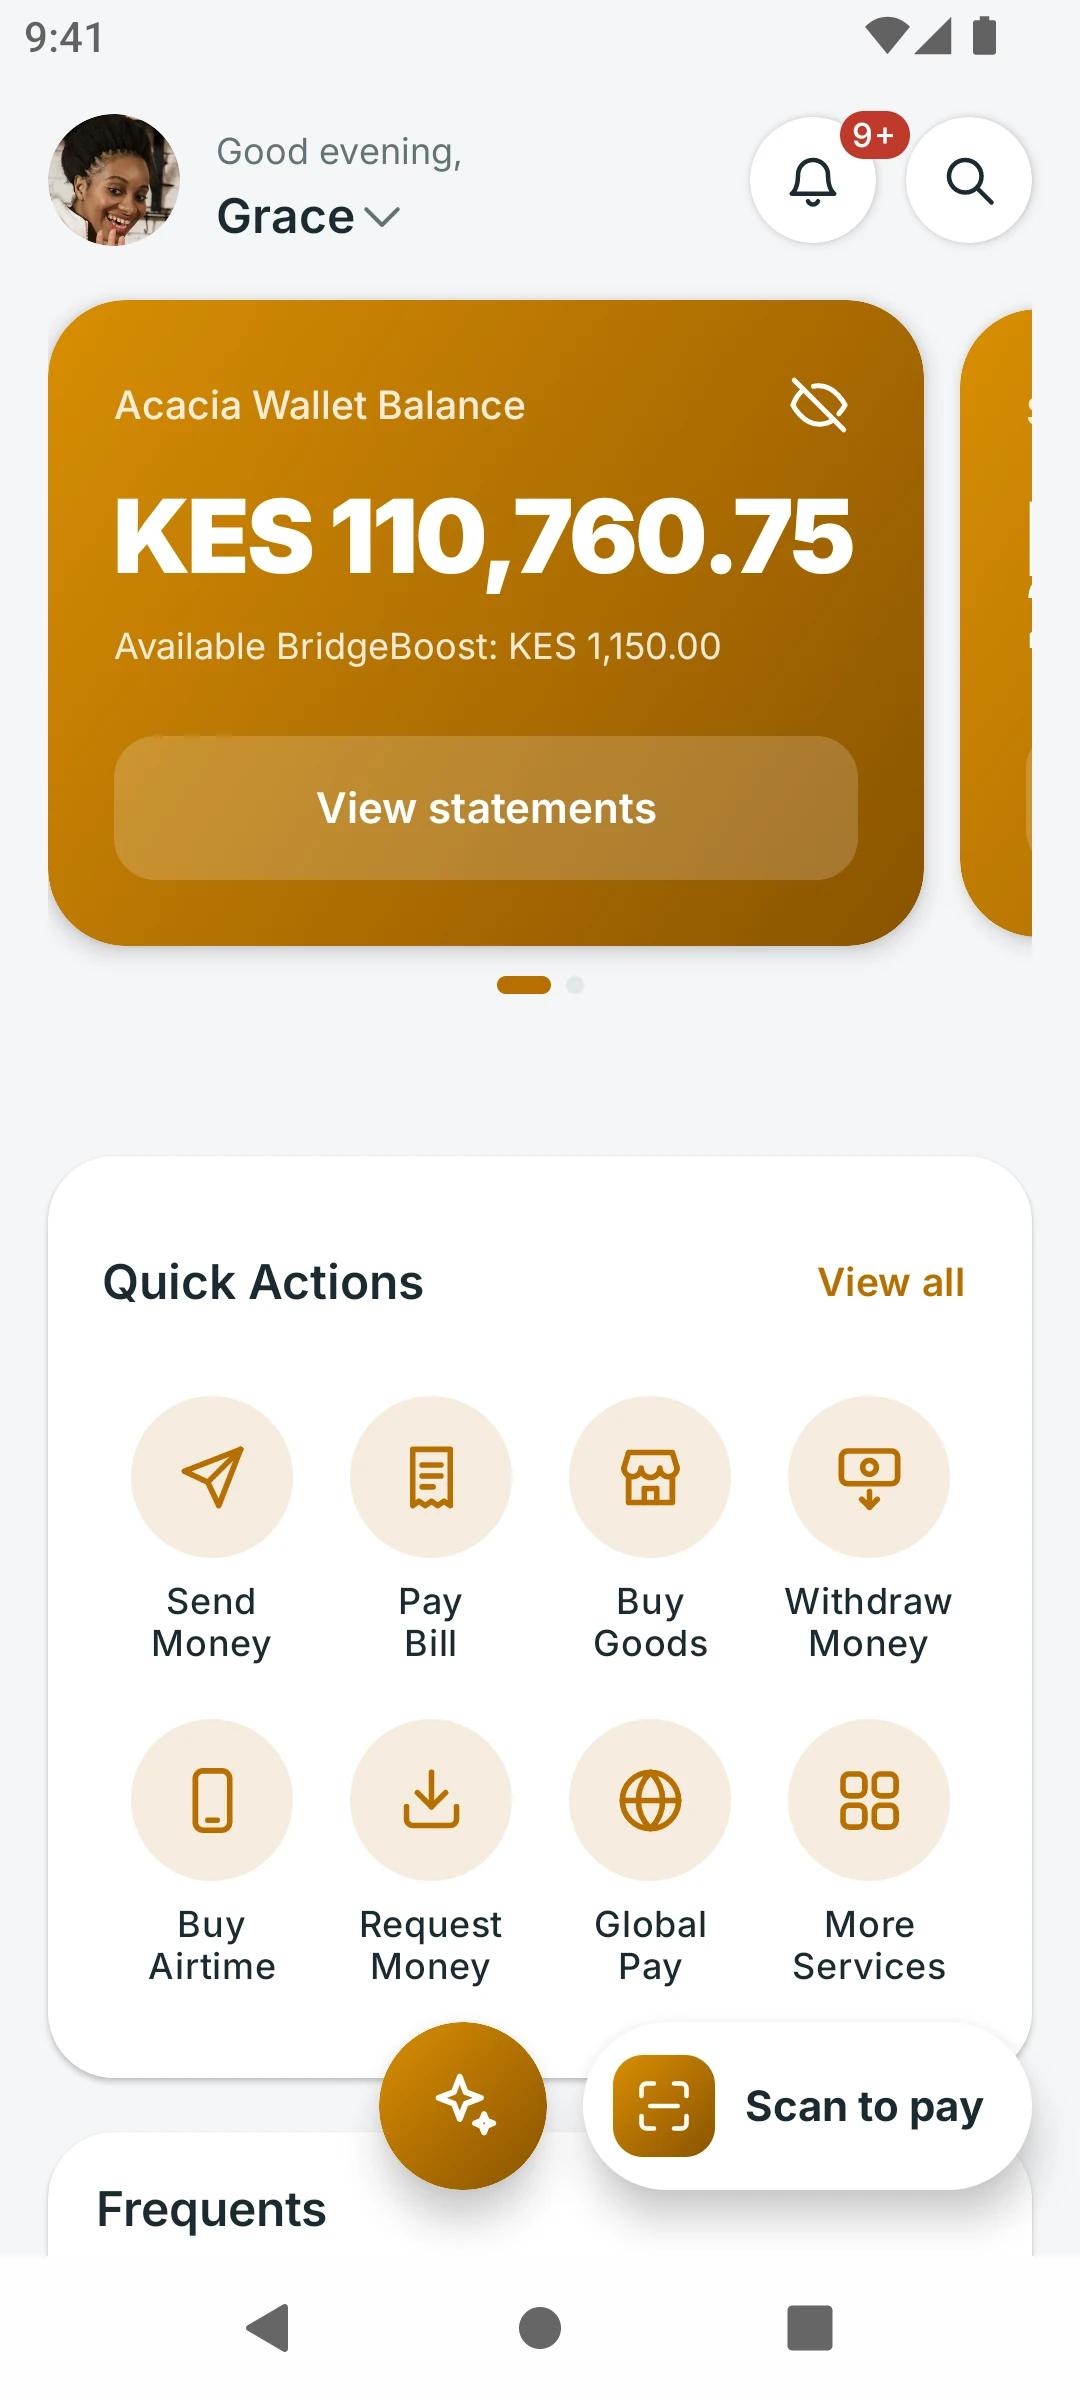
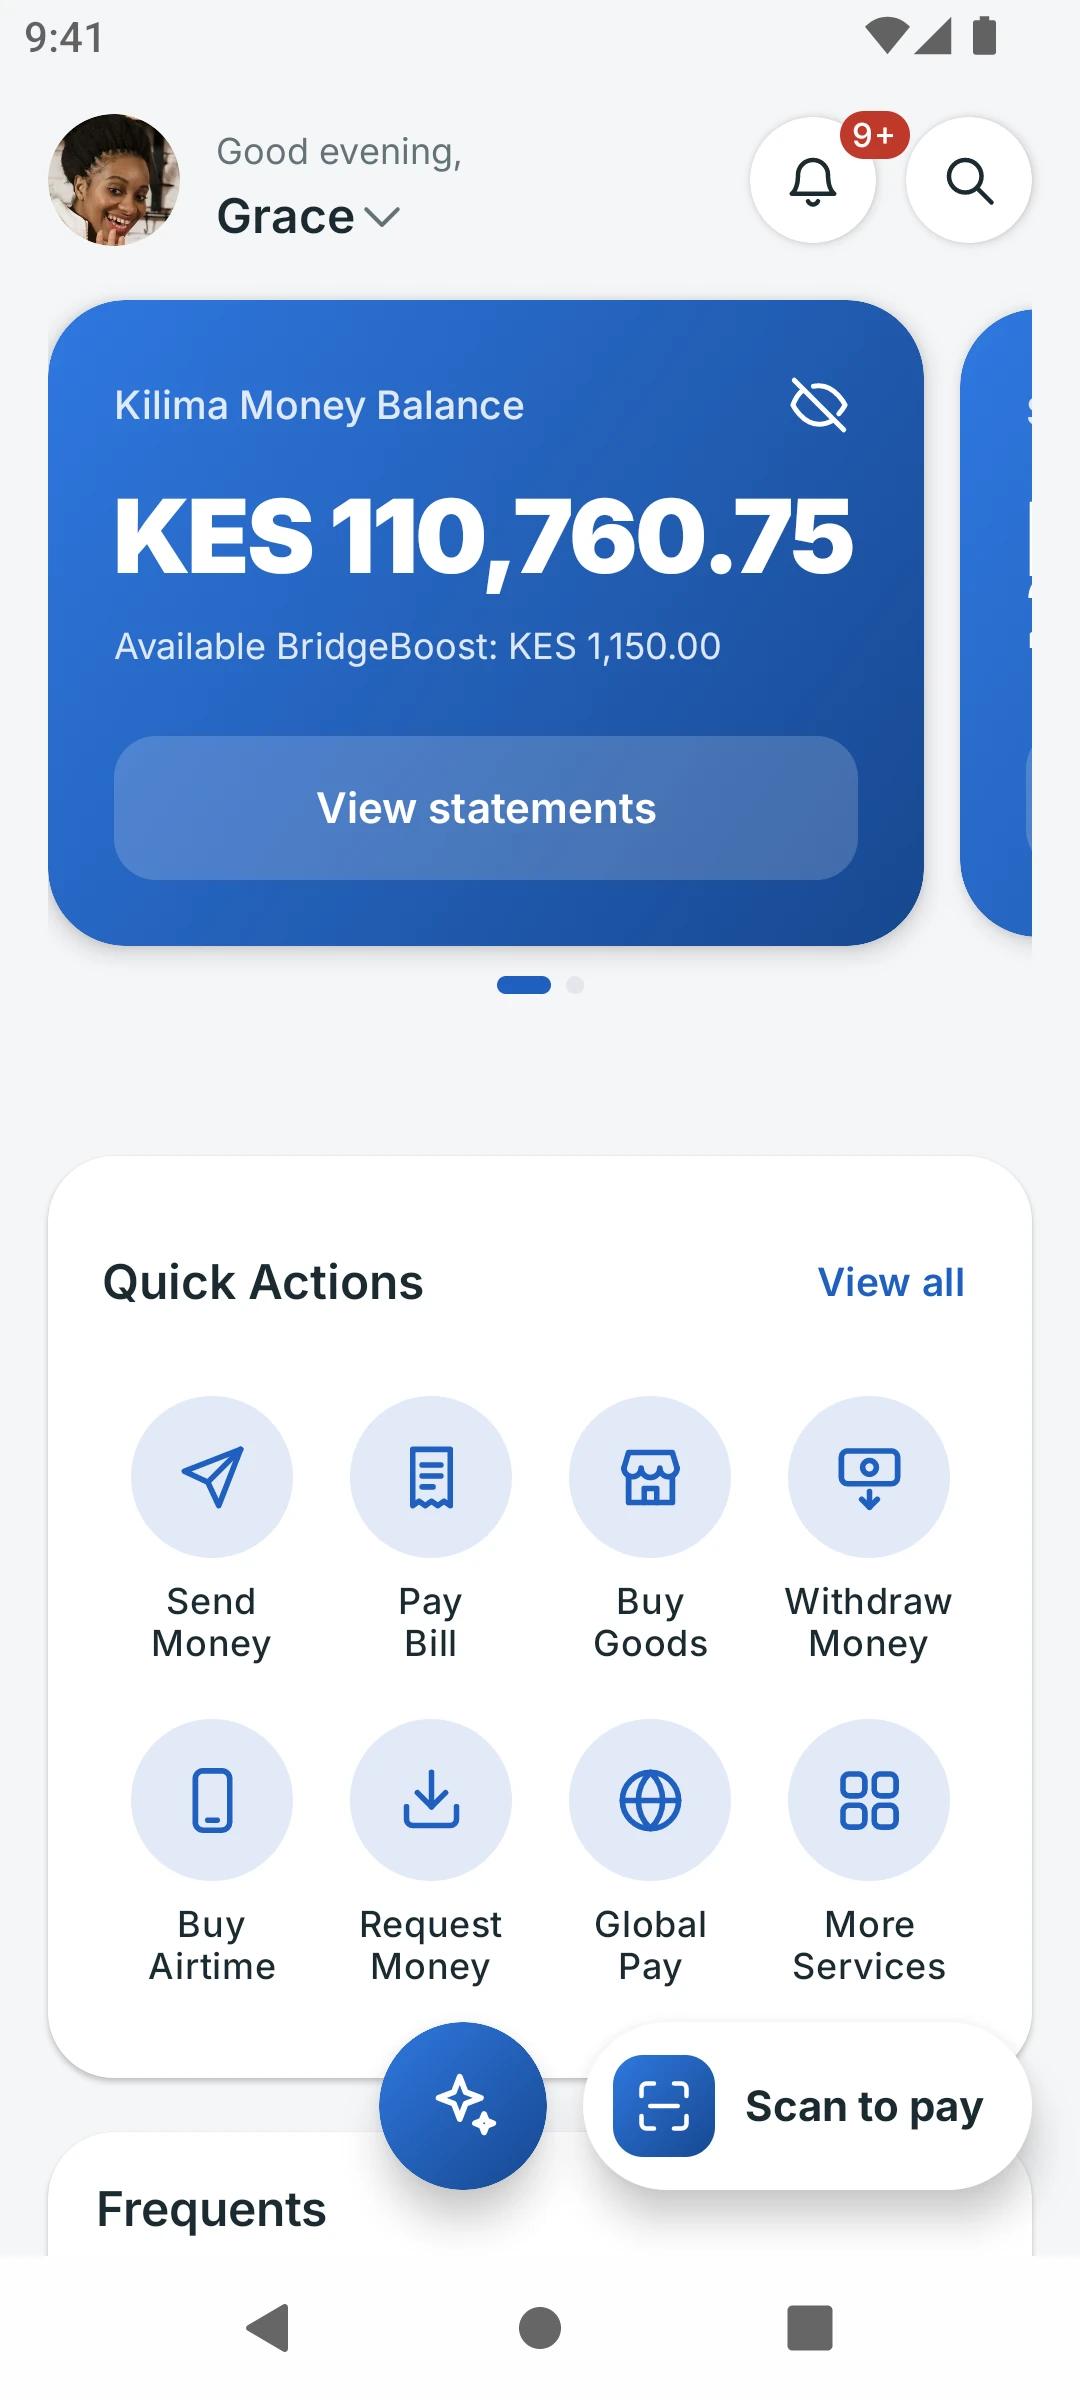
Customers never see PesaBridge. Your name, tagline, logos and colours are served to the apps and portals when they open, so you can change them without a new app release.
- Your name and logo. On the customer, agent, business, counter and corporate apps and the six web portals.
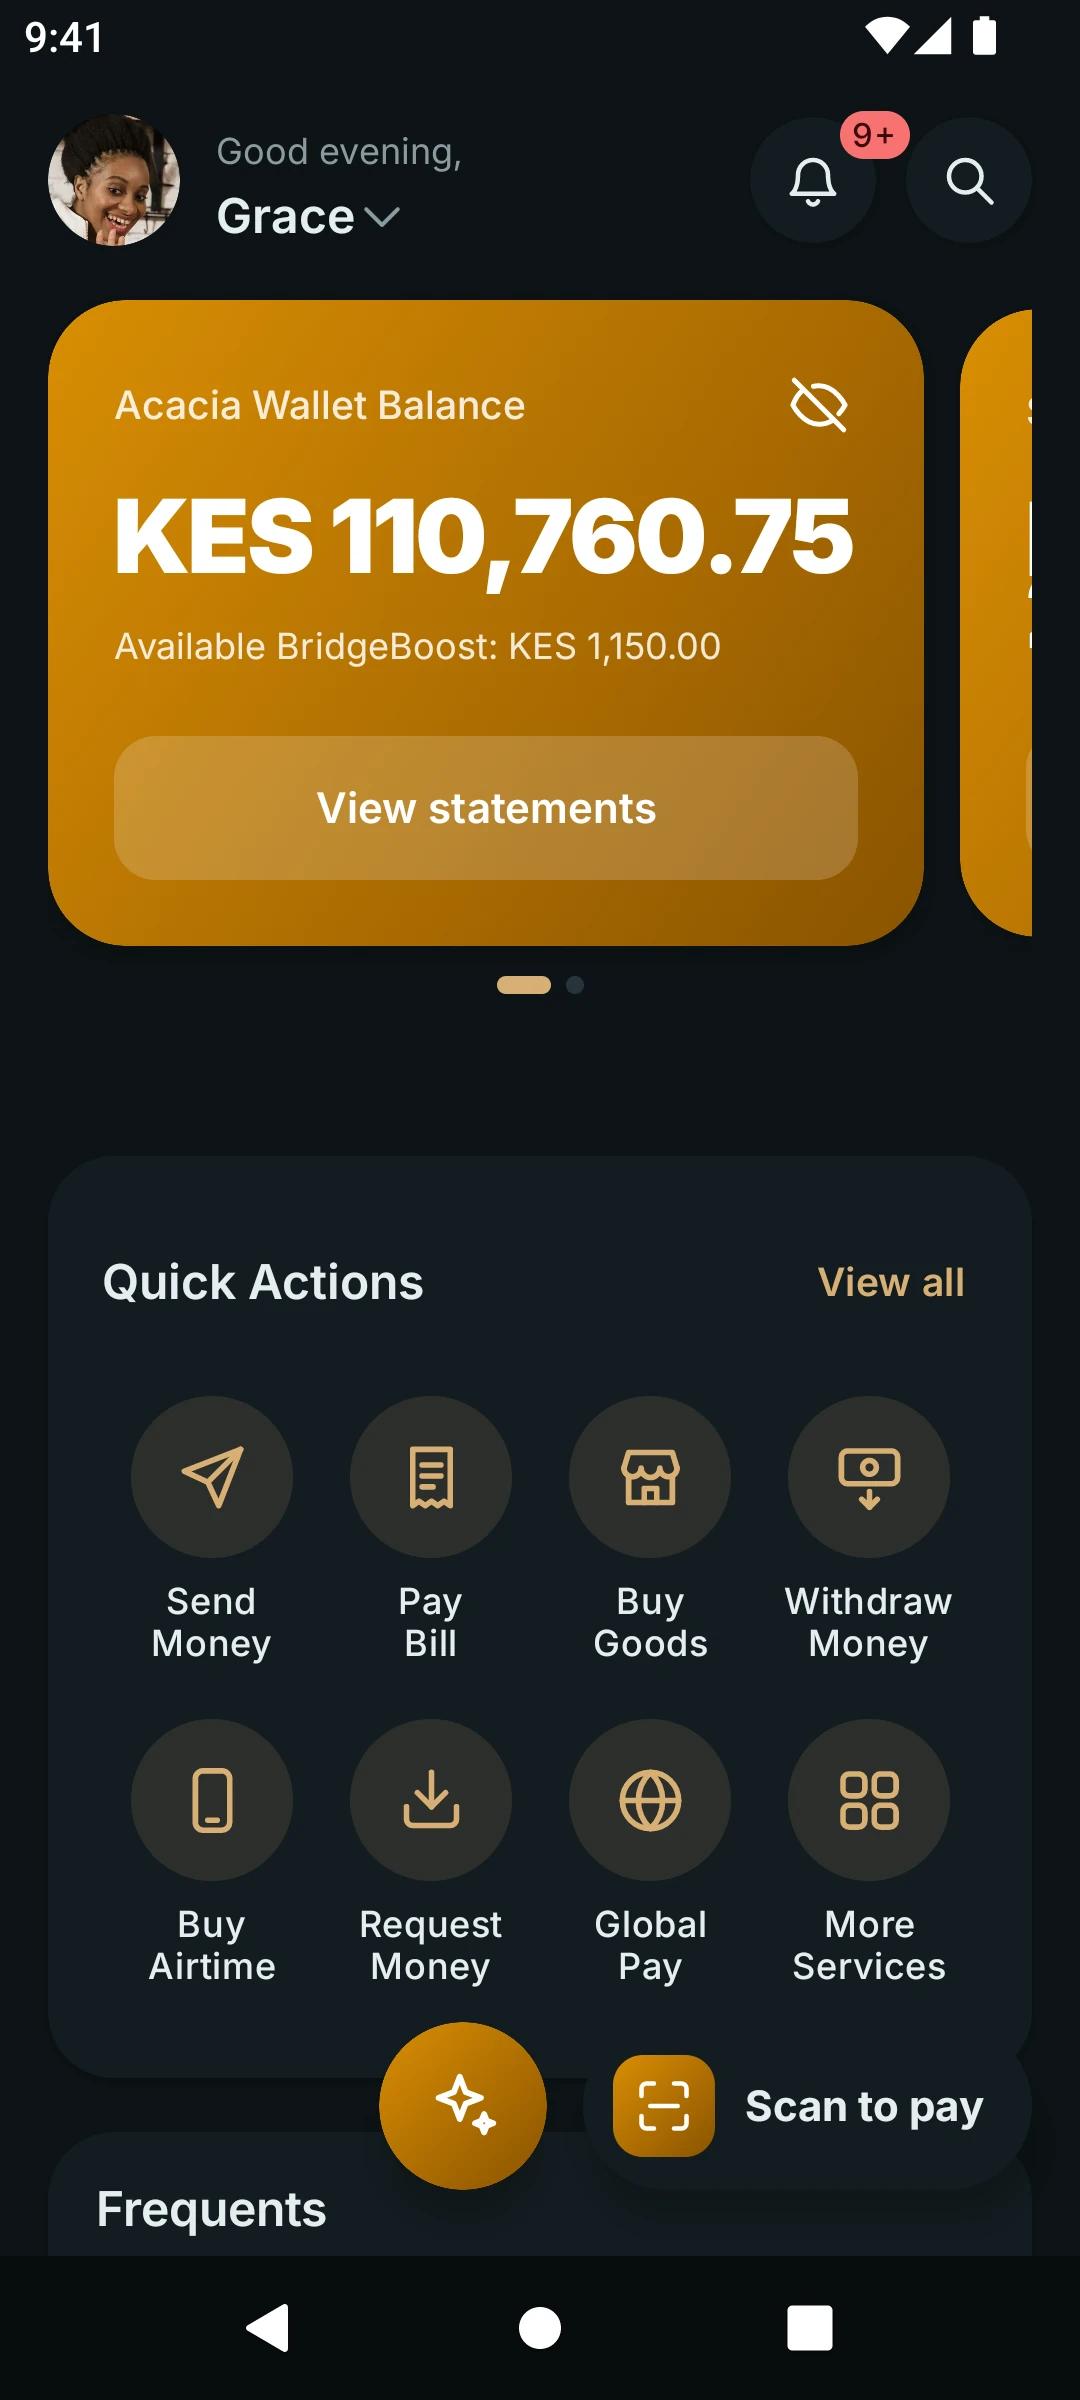
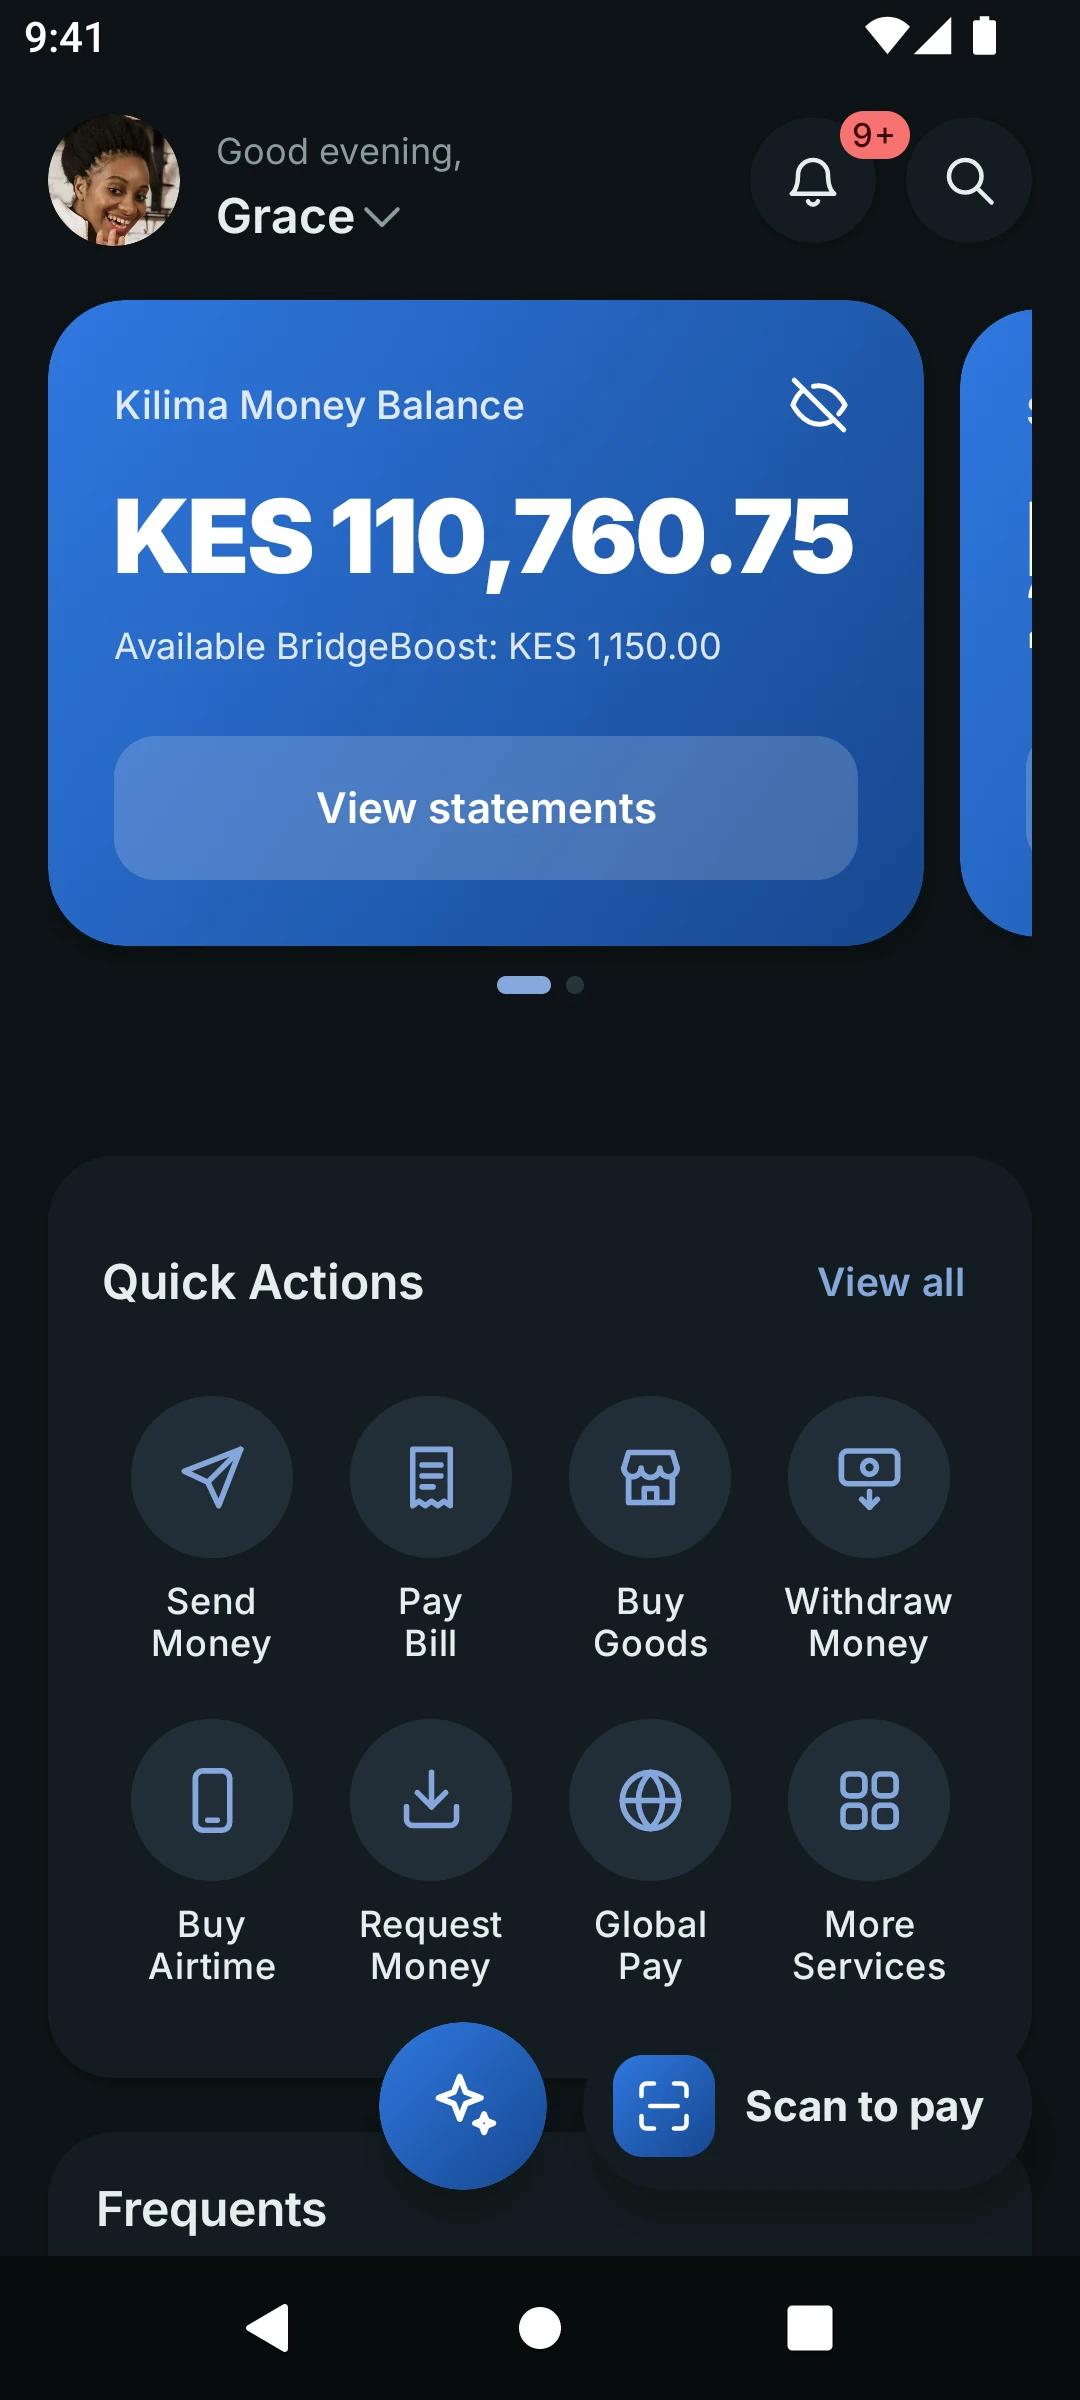
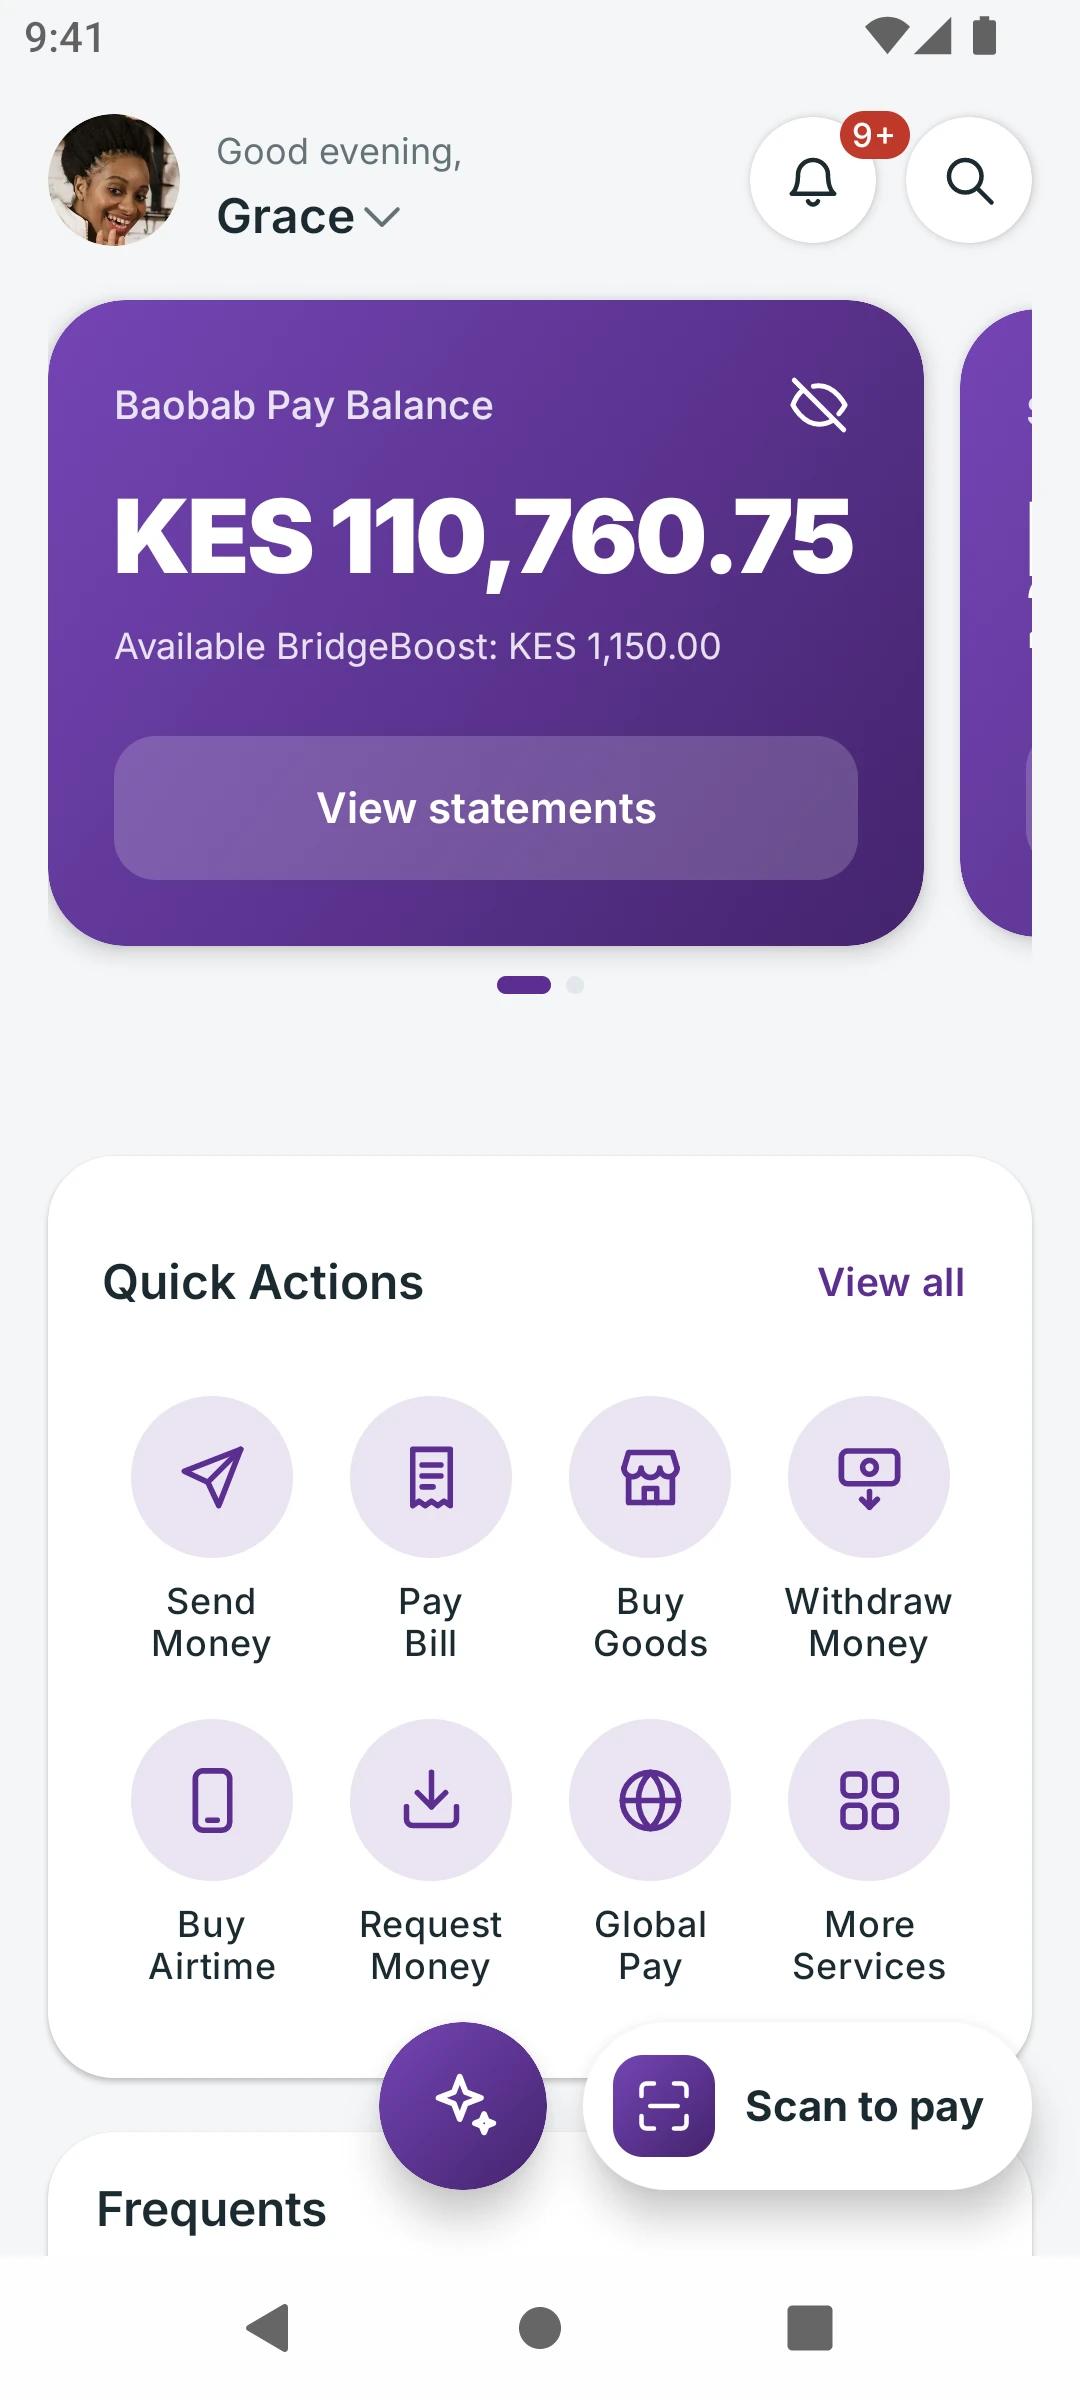
- Your colours. Every screen, button and chart takes your palette, in light and dark.
- Your currency and languages. Your currency, and apps and portals in up to 12 languages.
- Your mini apps. Switch each mini app on or off for your market, or mark it as coming soon.
- Your store listings. We build the Android and iOS apps under your own app id and store name, for your developer accounts.
- Acacia WalletYour name. Your colours. Your logo.
- Kilima MoneyYour name. Your colours. Your logo.
- Baobab PayYour name. Your colours. Your logo.
Every phone
No smartphone? No data? Still a customer.
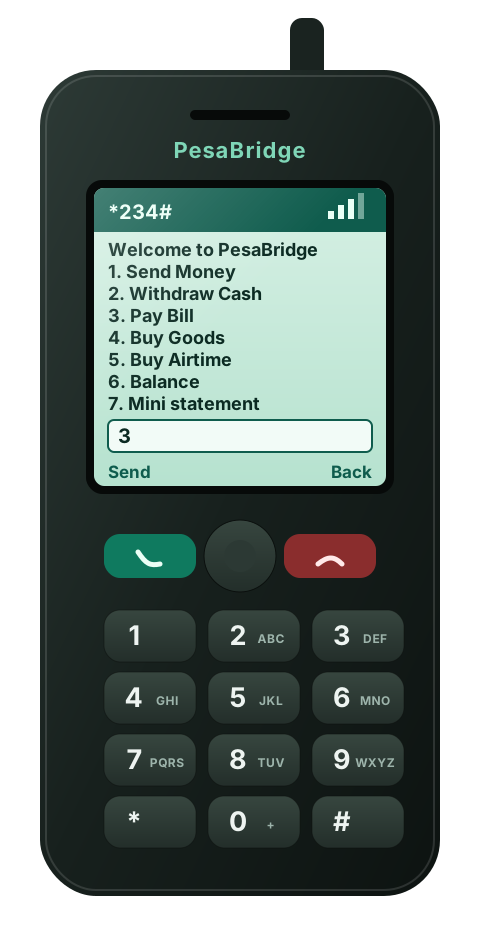
A wallet that only ships as an app leaves most of a market out. Your USSD shortcode gives every phone the everyday wallet, on the same balance as the apps. Your USSD aggregator connects to one endpoint.
- The everyday menu. Send money, withdraw cash, Pay Bill, Buy Goods, buy airtime, balance and mini statement.
- PIN-protected. Every payment over USSD is confirmed with the customer's PIN.
- One balance. Money sent over USSD lands in the same wallet the app shows.
- In your customers' language. Menus in English, French or Arabic, chosen from the menu itself.
Back office
Run the whole business from one back office
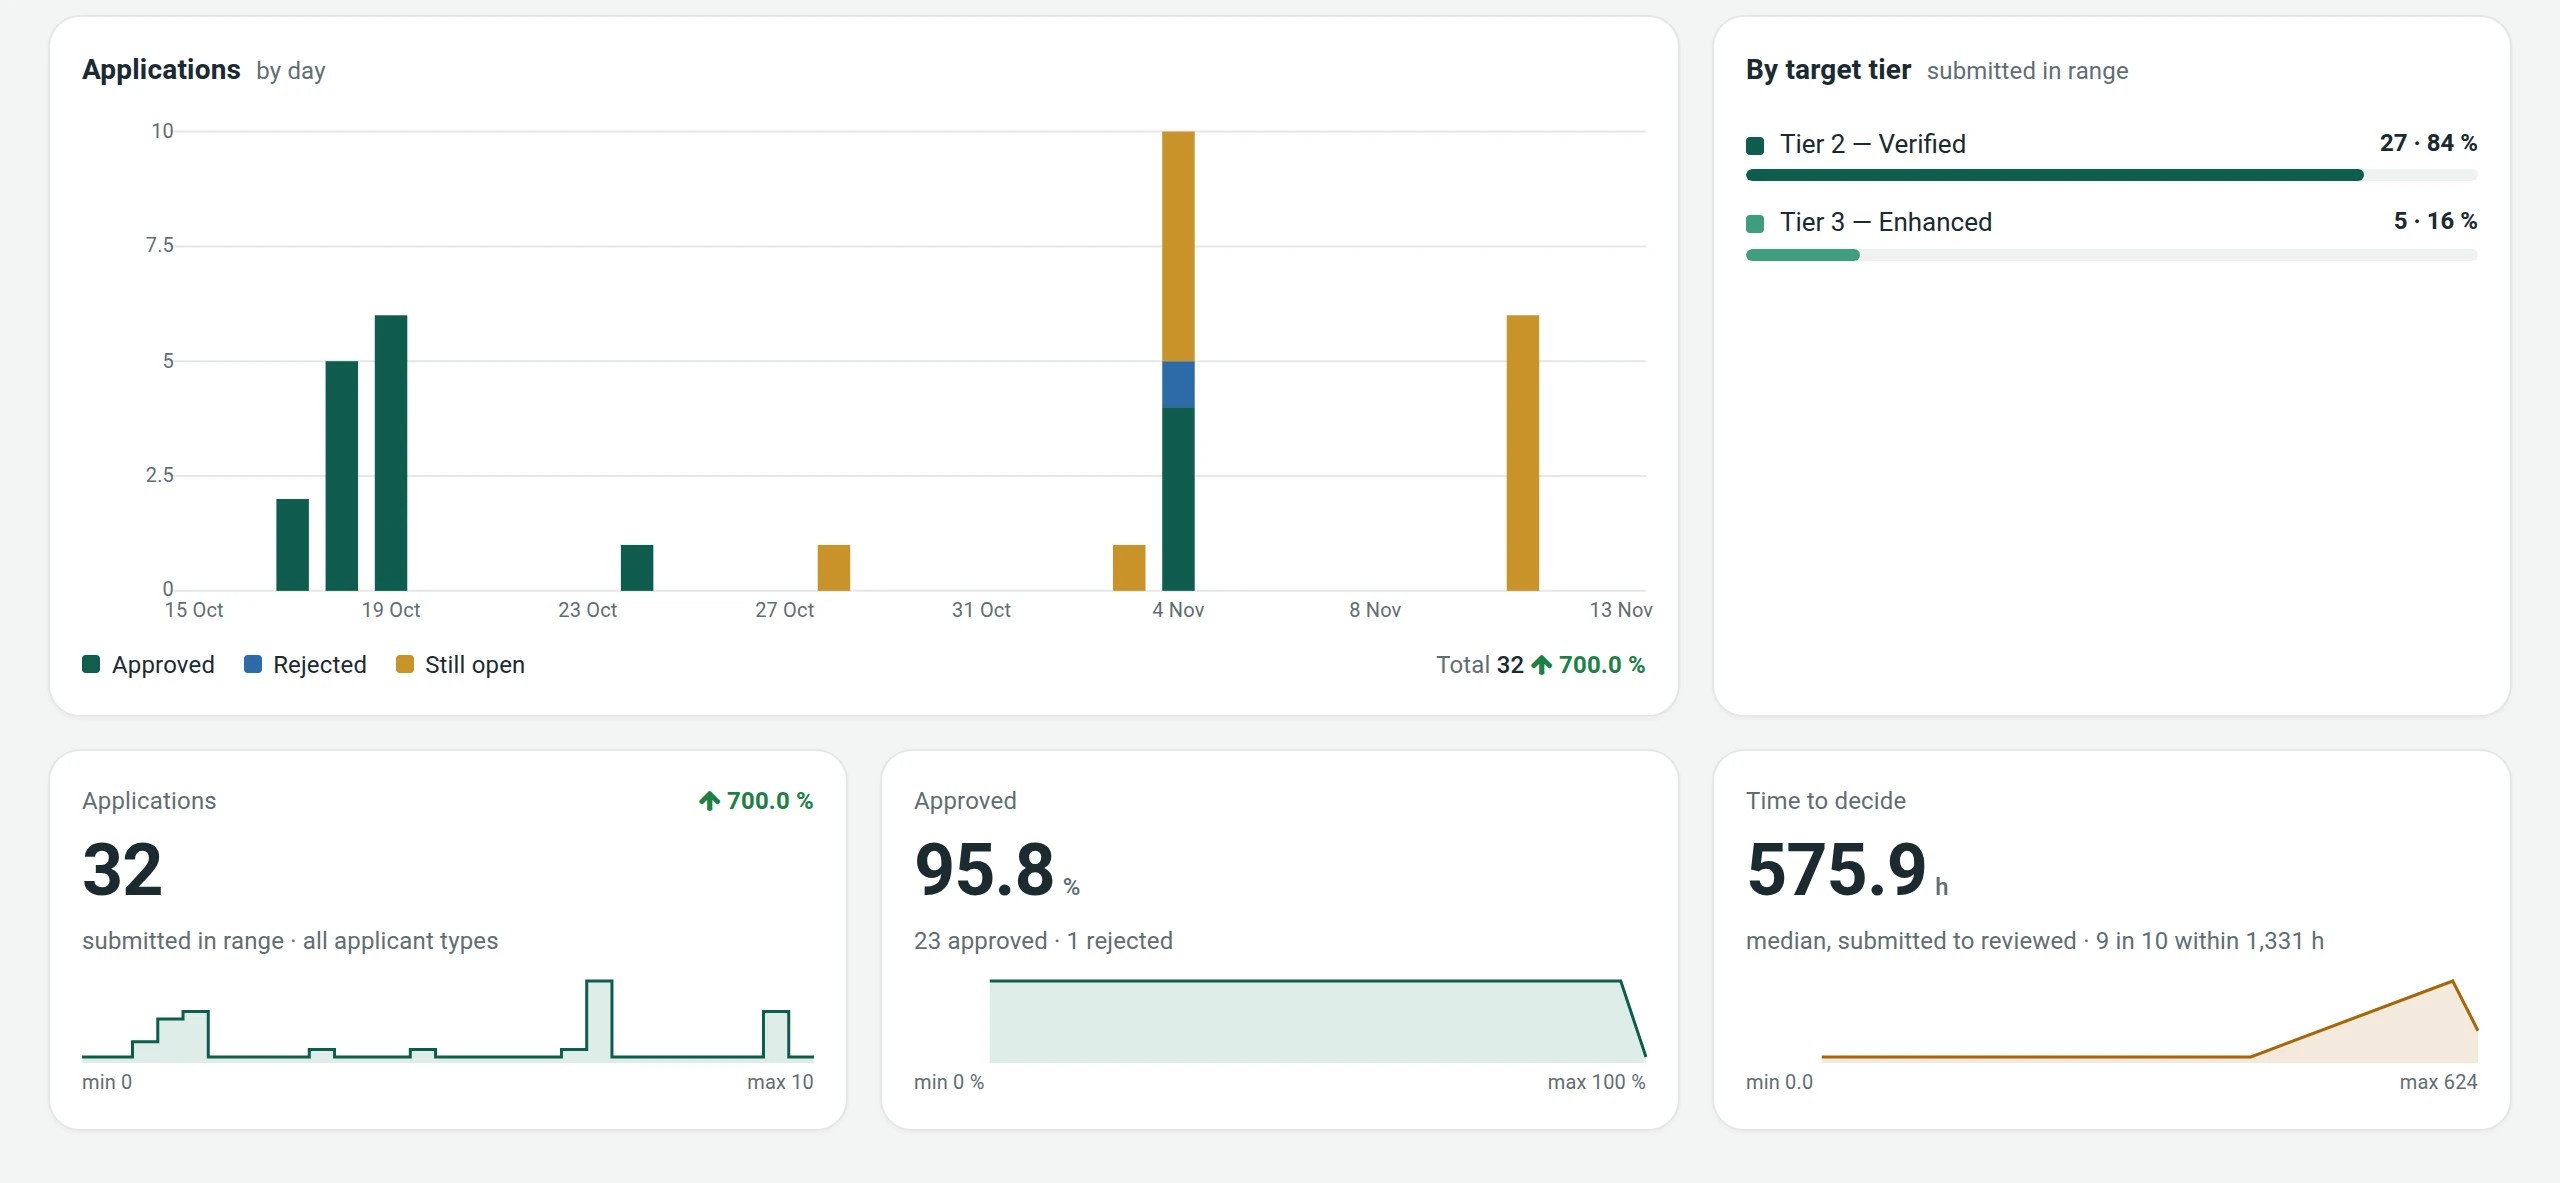
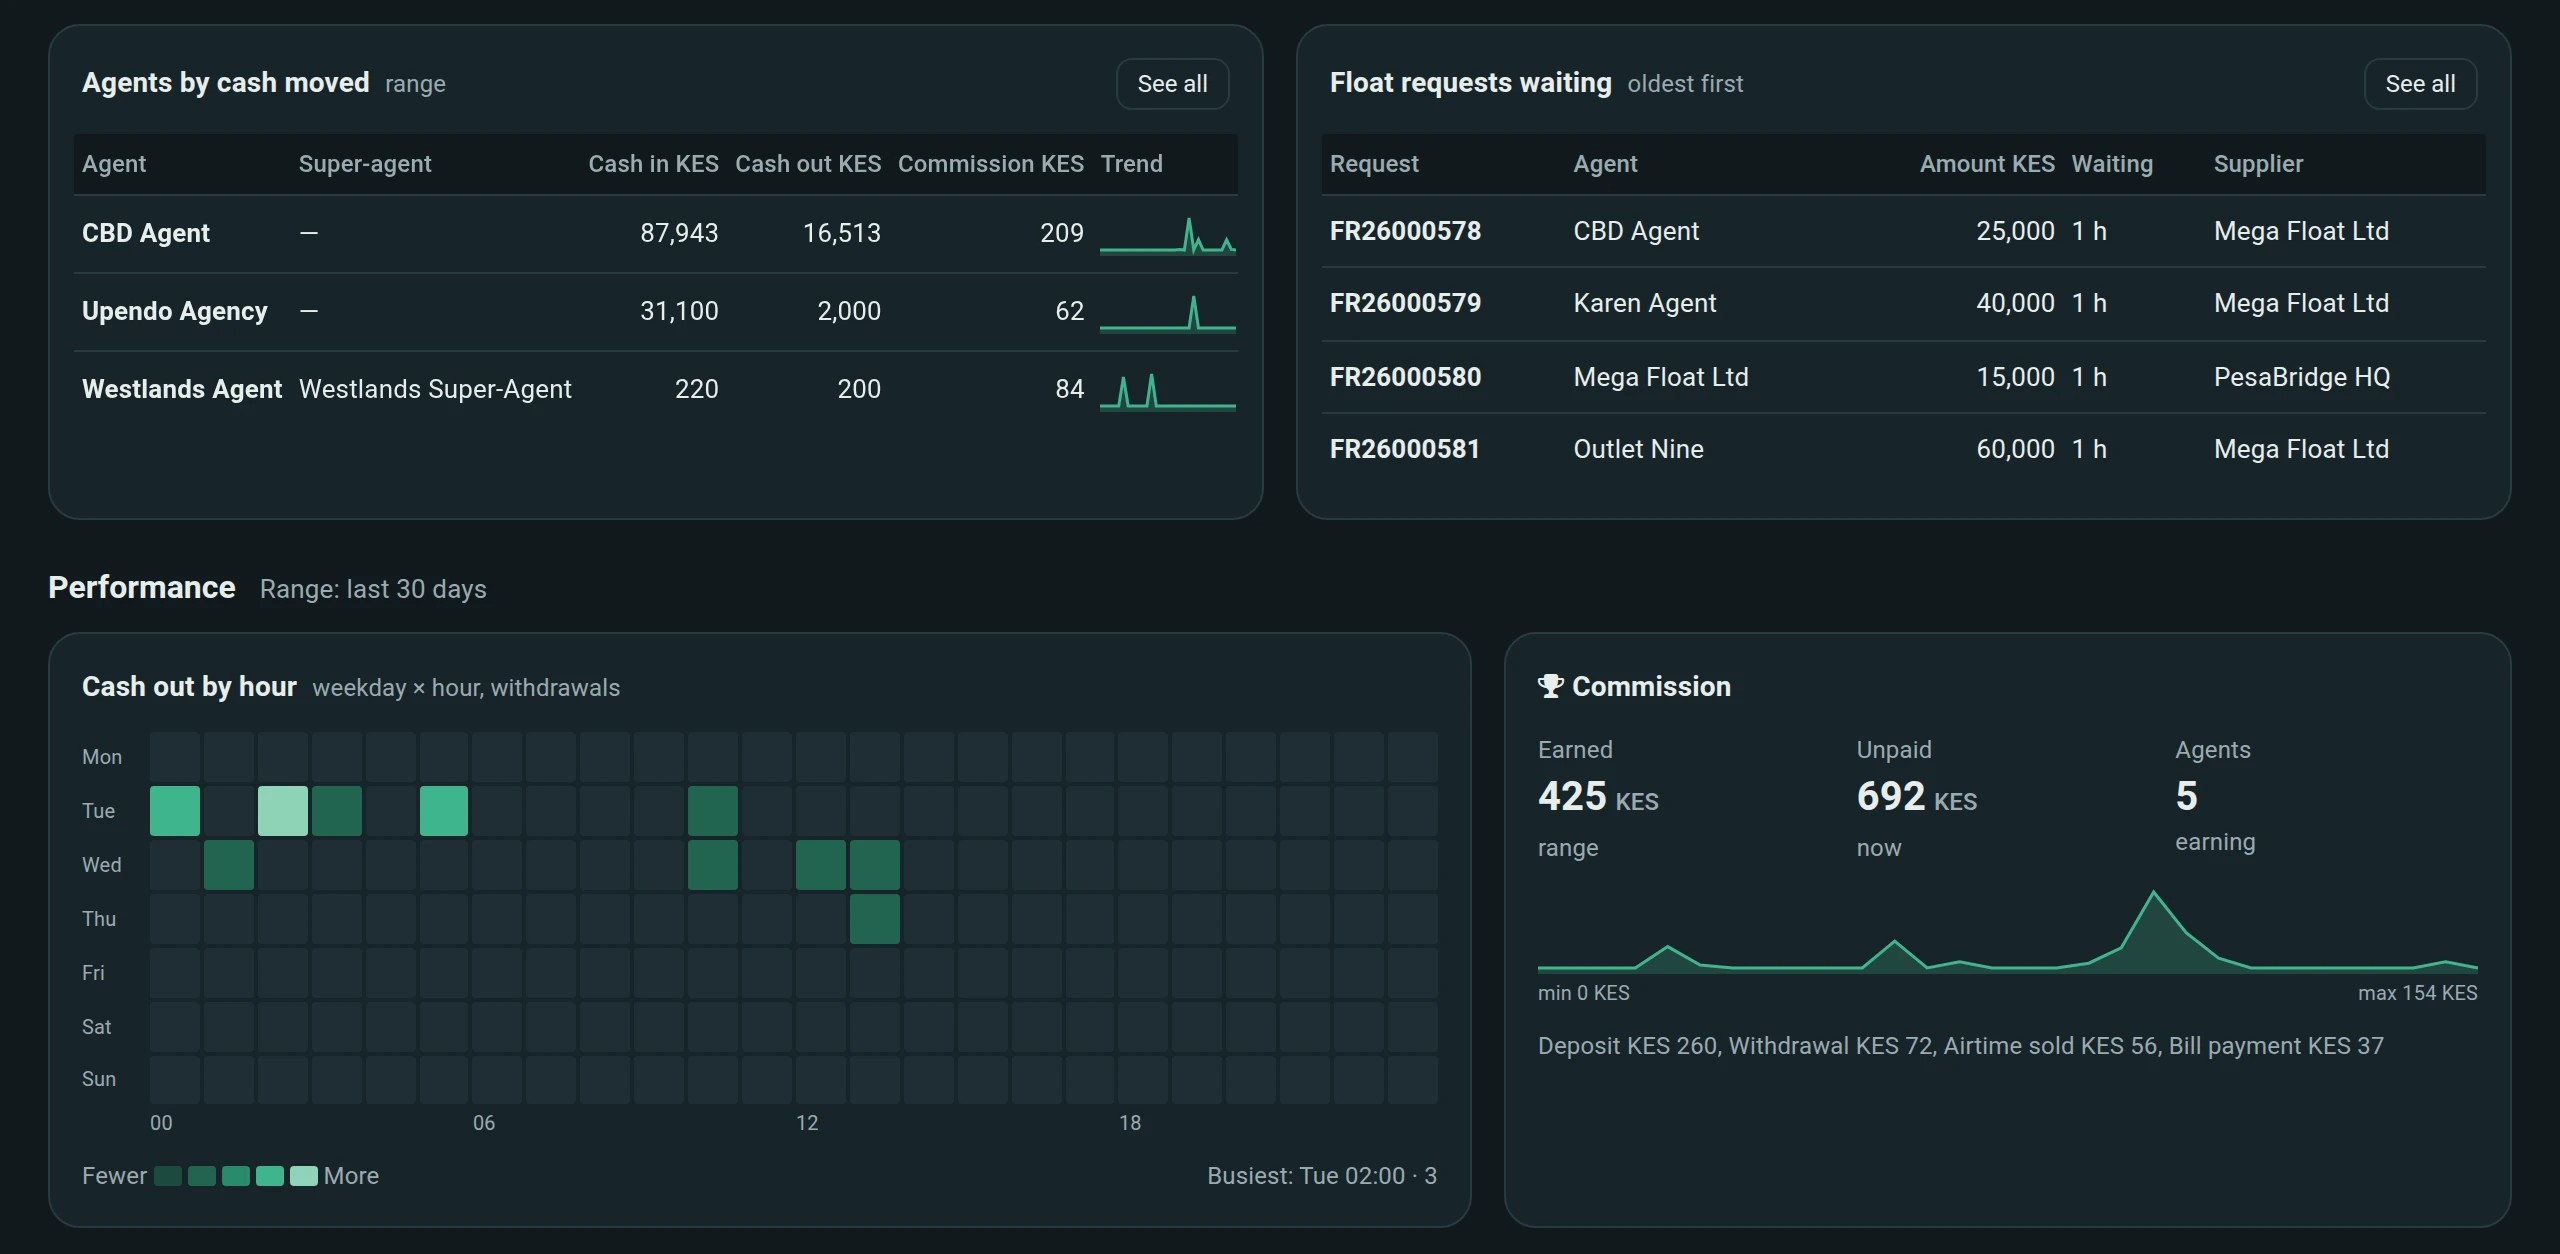
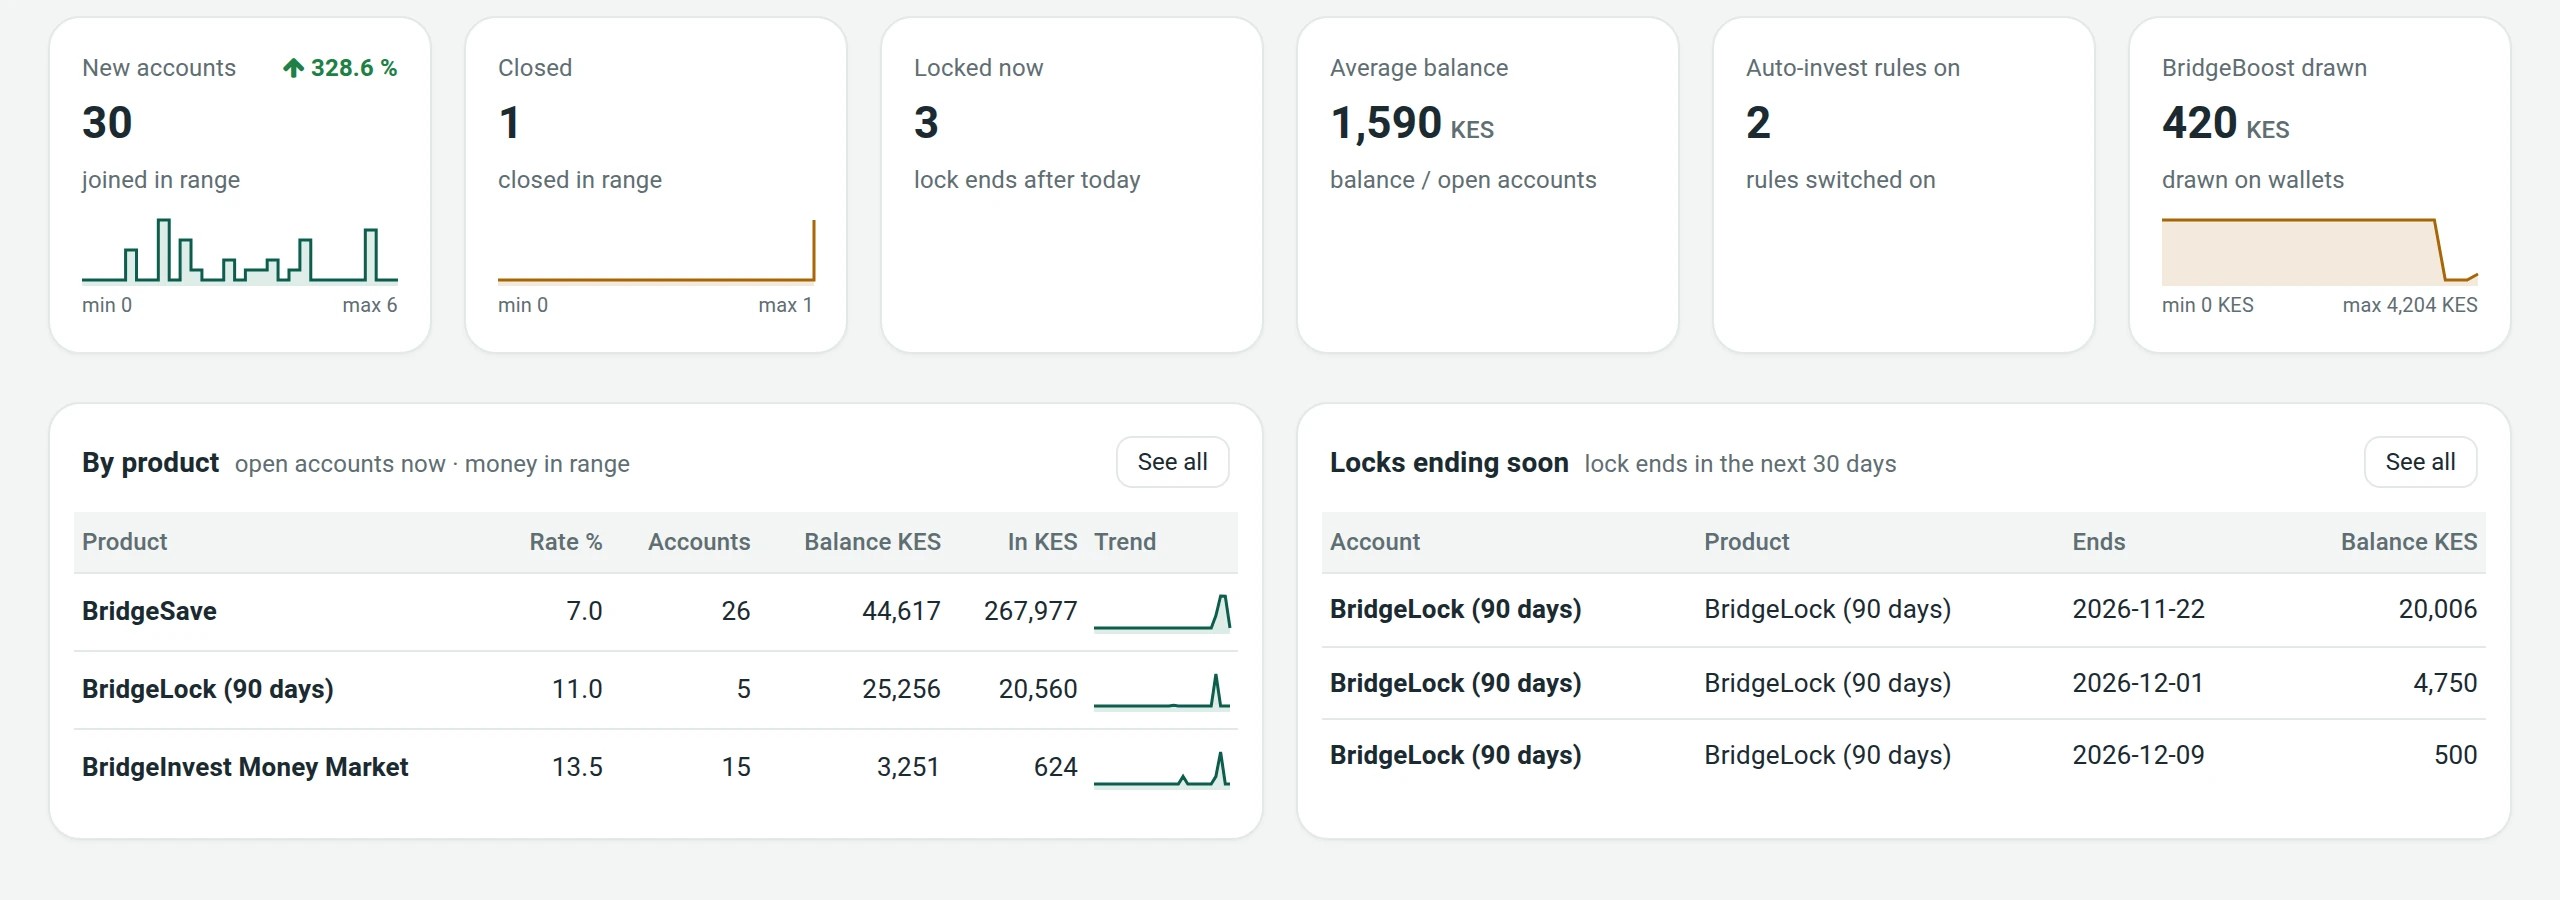
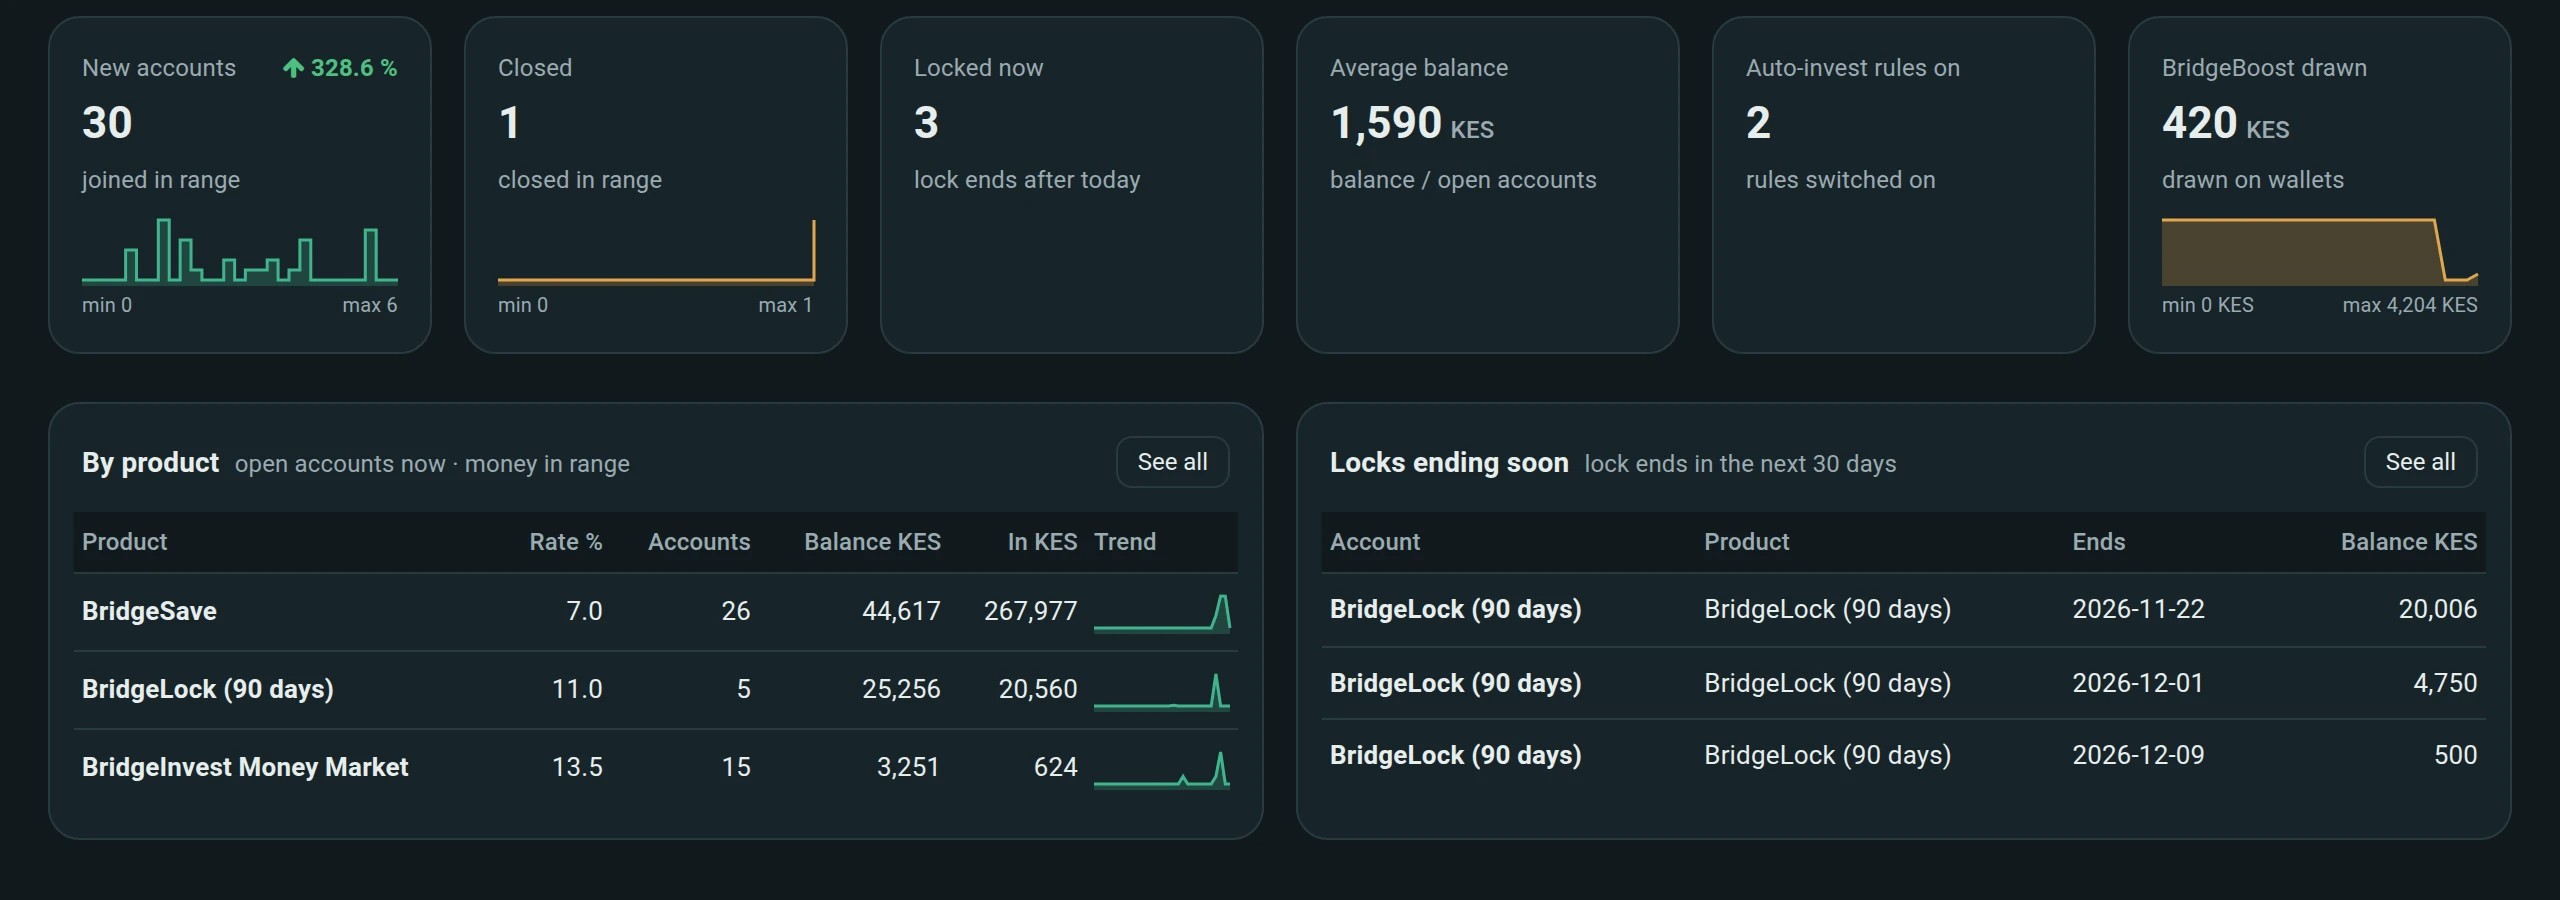
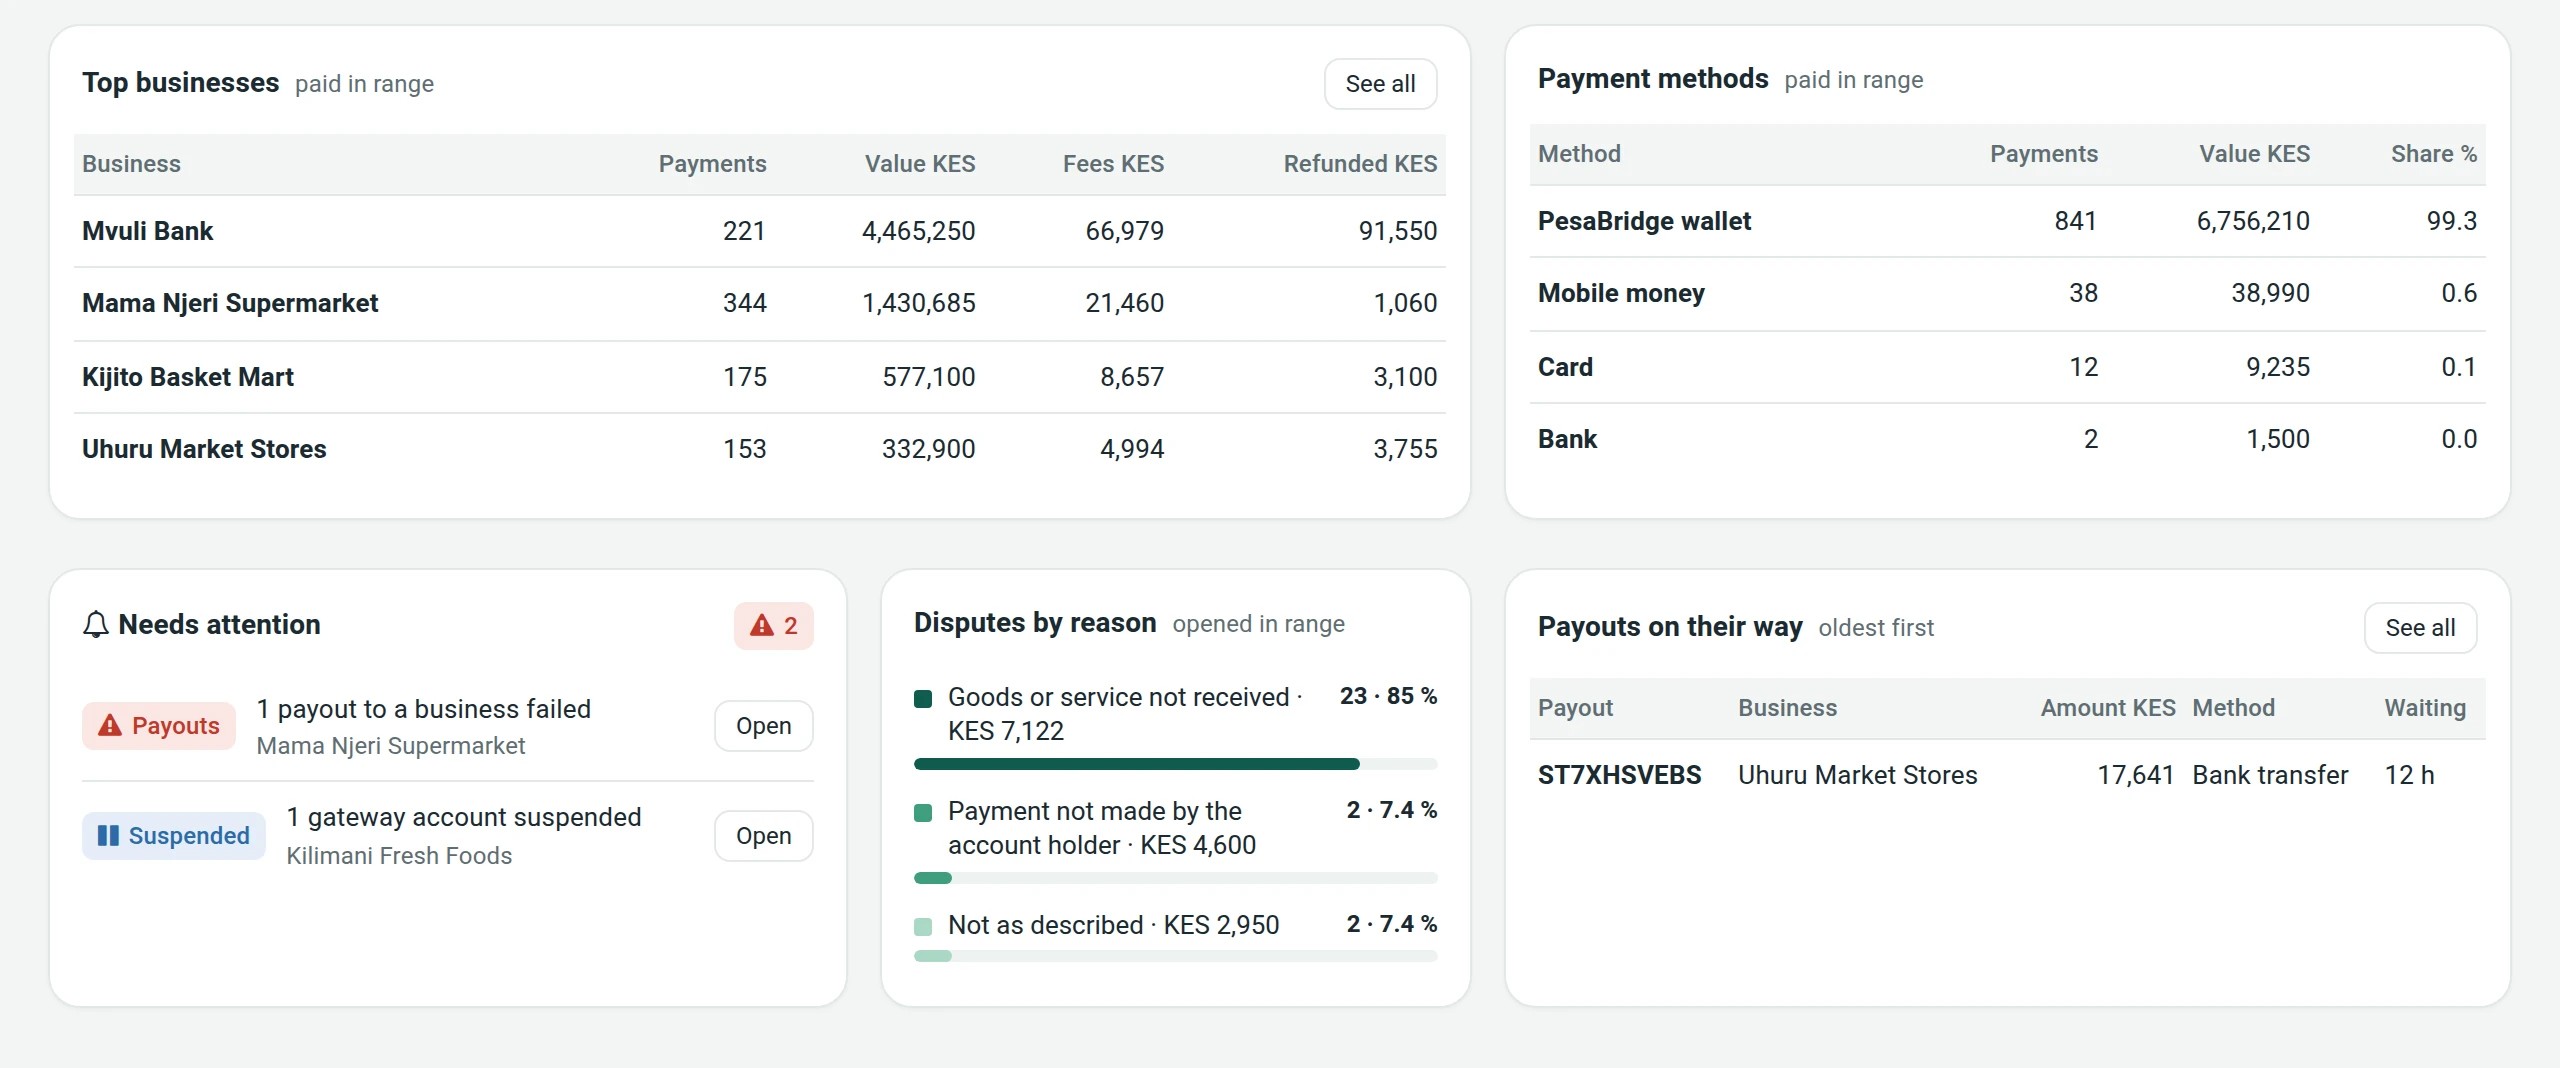
Operations, finance, compliance and risk teams work in one back office, with a dashboard for each product and one navigation for all of them.
- A dashboard per product. Gateway, international, KYC, loans, savings, insurance, corporate, agent network, treasury and P&L.
- Today at a glance. Customer, agent and merchant counts, today's volume and value, balances, float health and revenue.
- Maker and checker. Float, commission payouts and treasury movements need a second approver, and two above the threshold you set.
- Roles and access. Each team member sees the menus their role allows, and features are switched on in Settings.
- Support tools. Freeze a wallet, force a PIN reset, suspend an agent and track complaints with tickets.
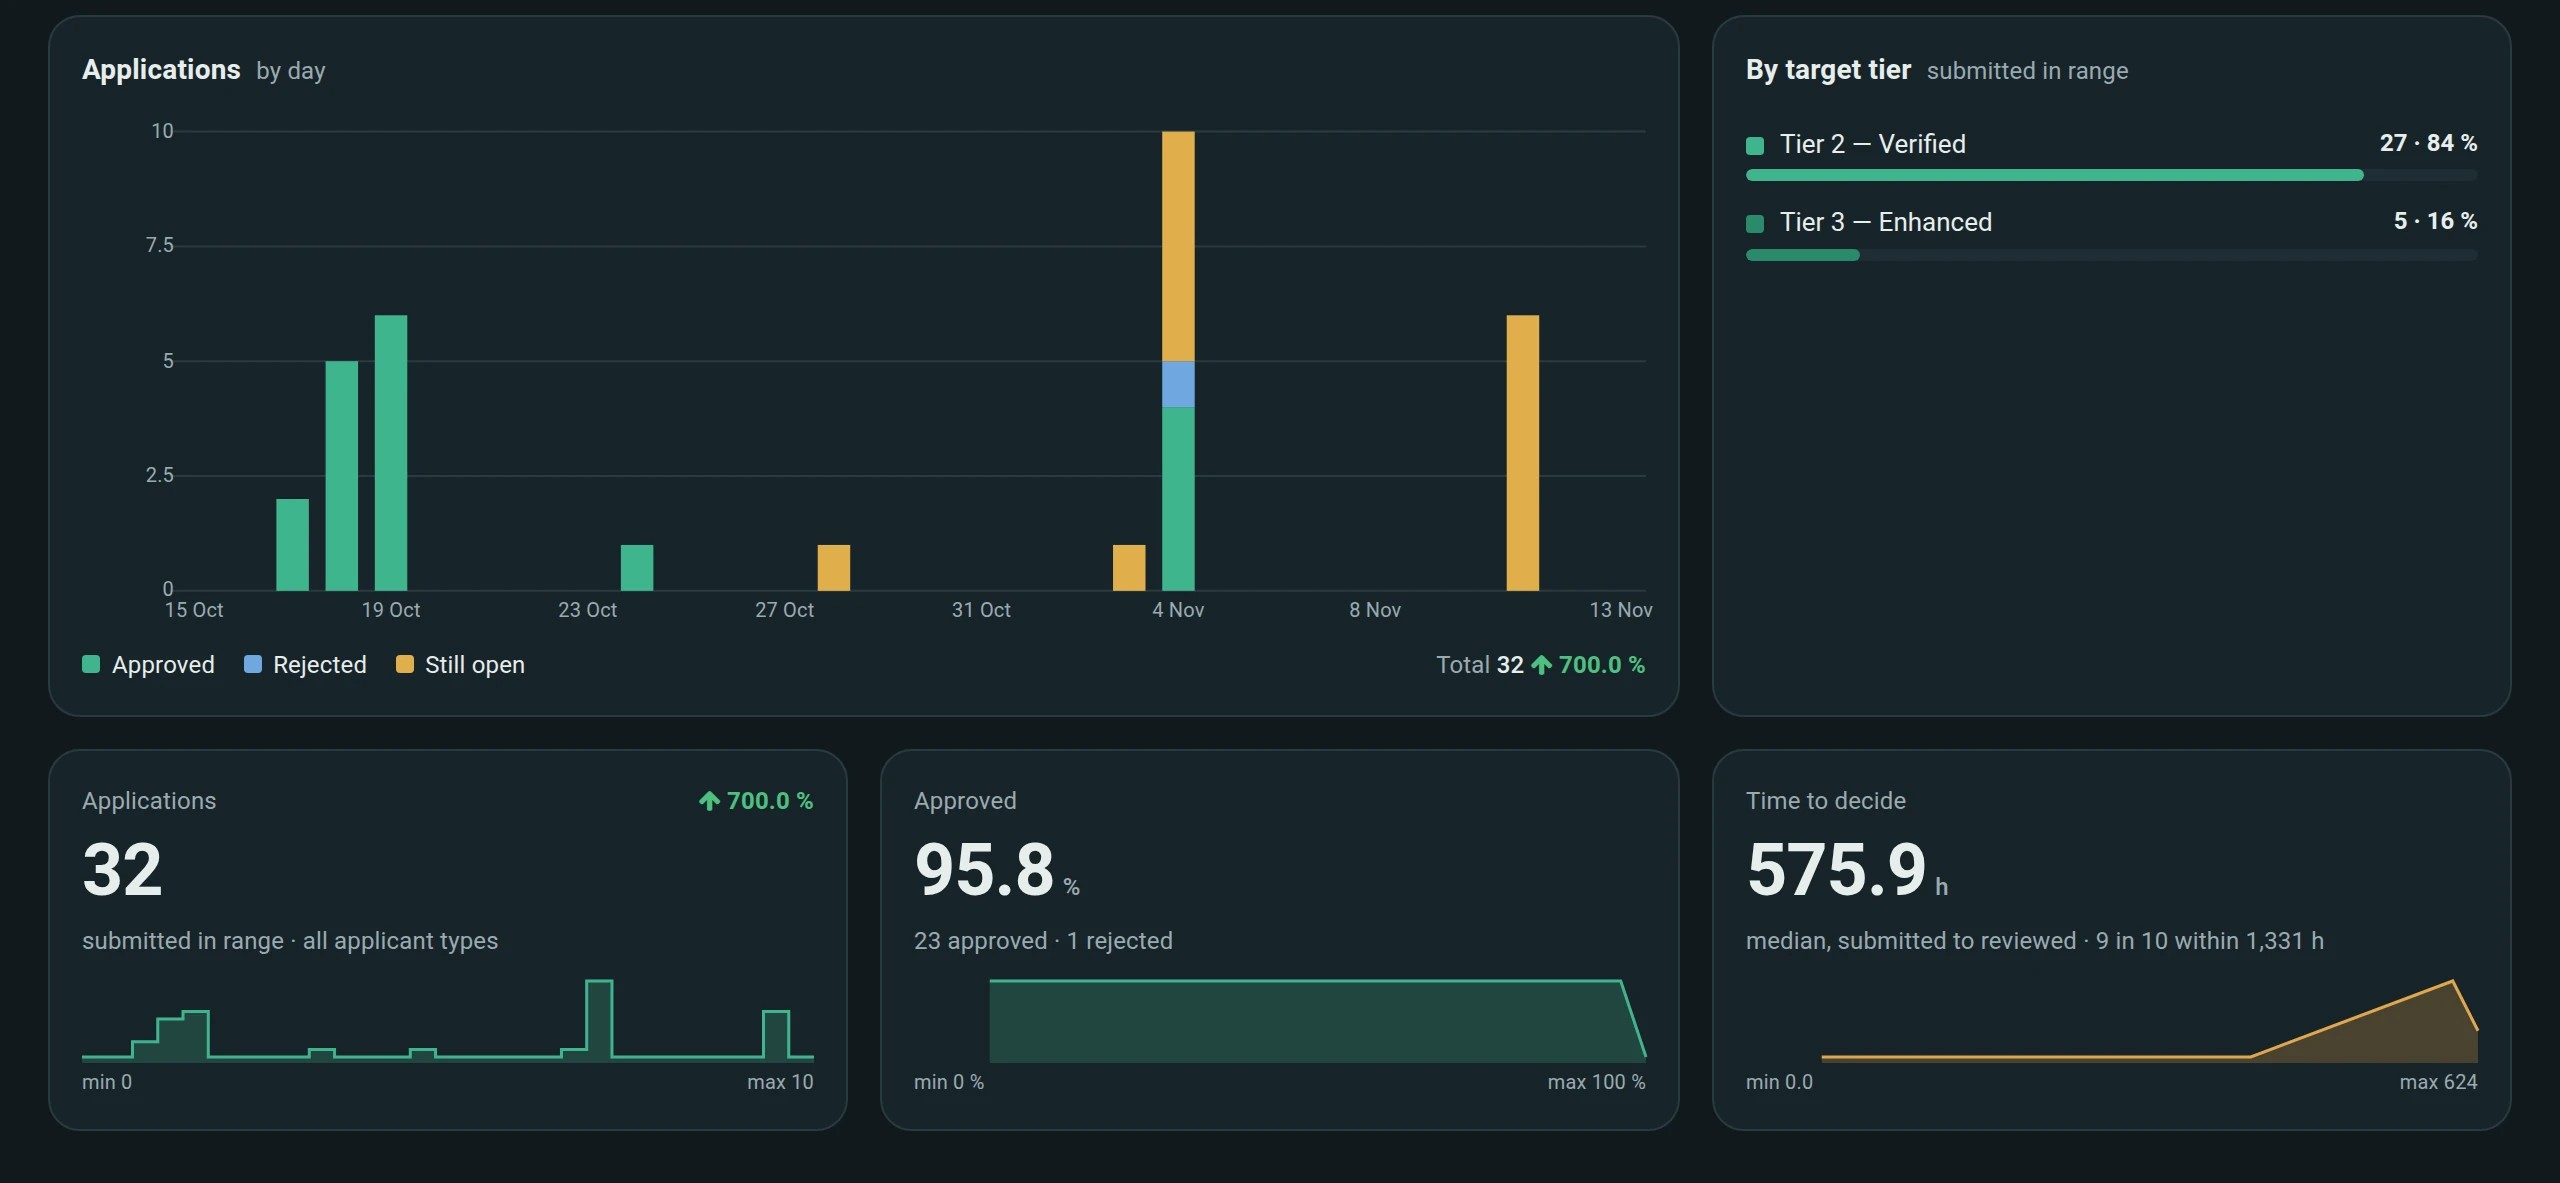
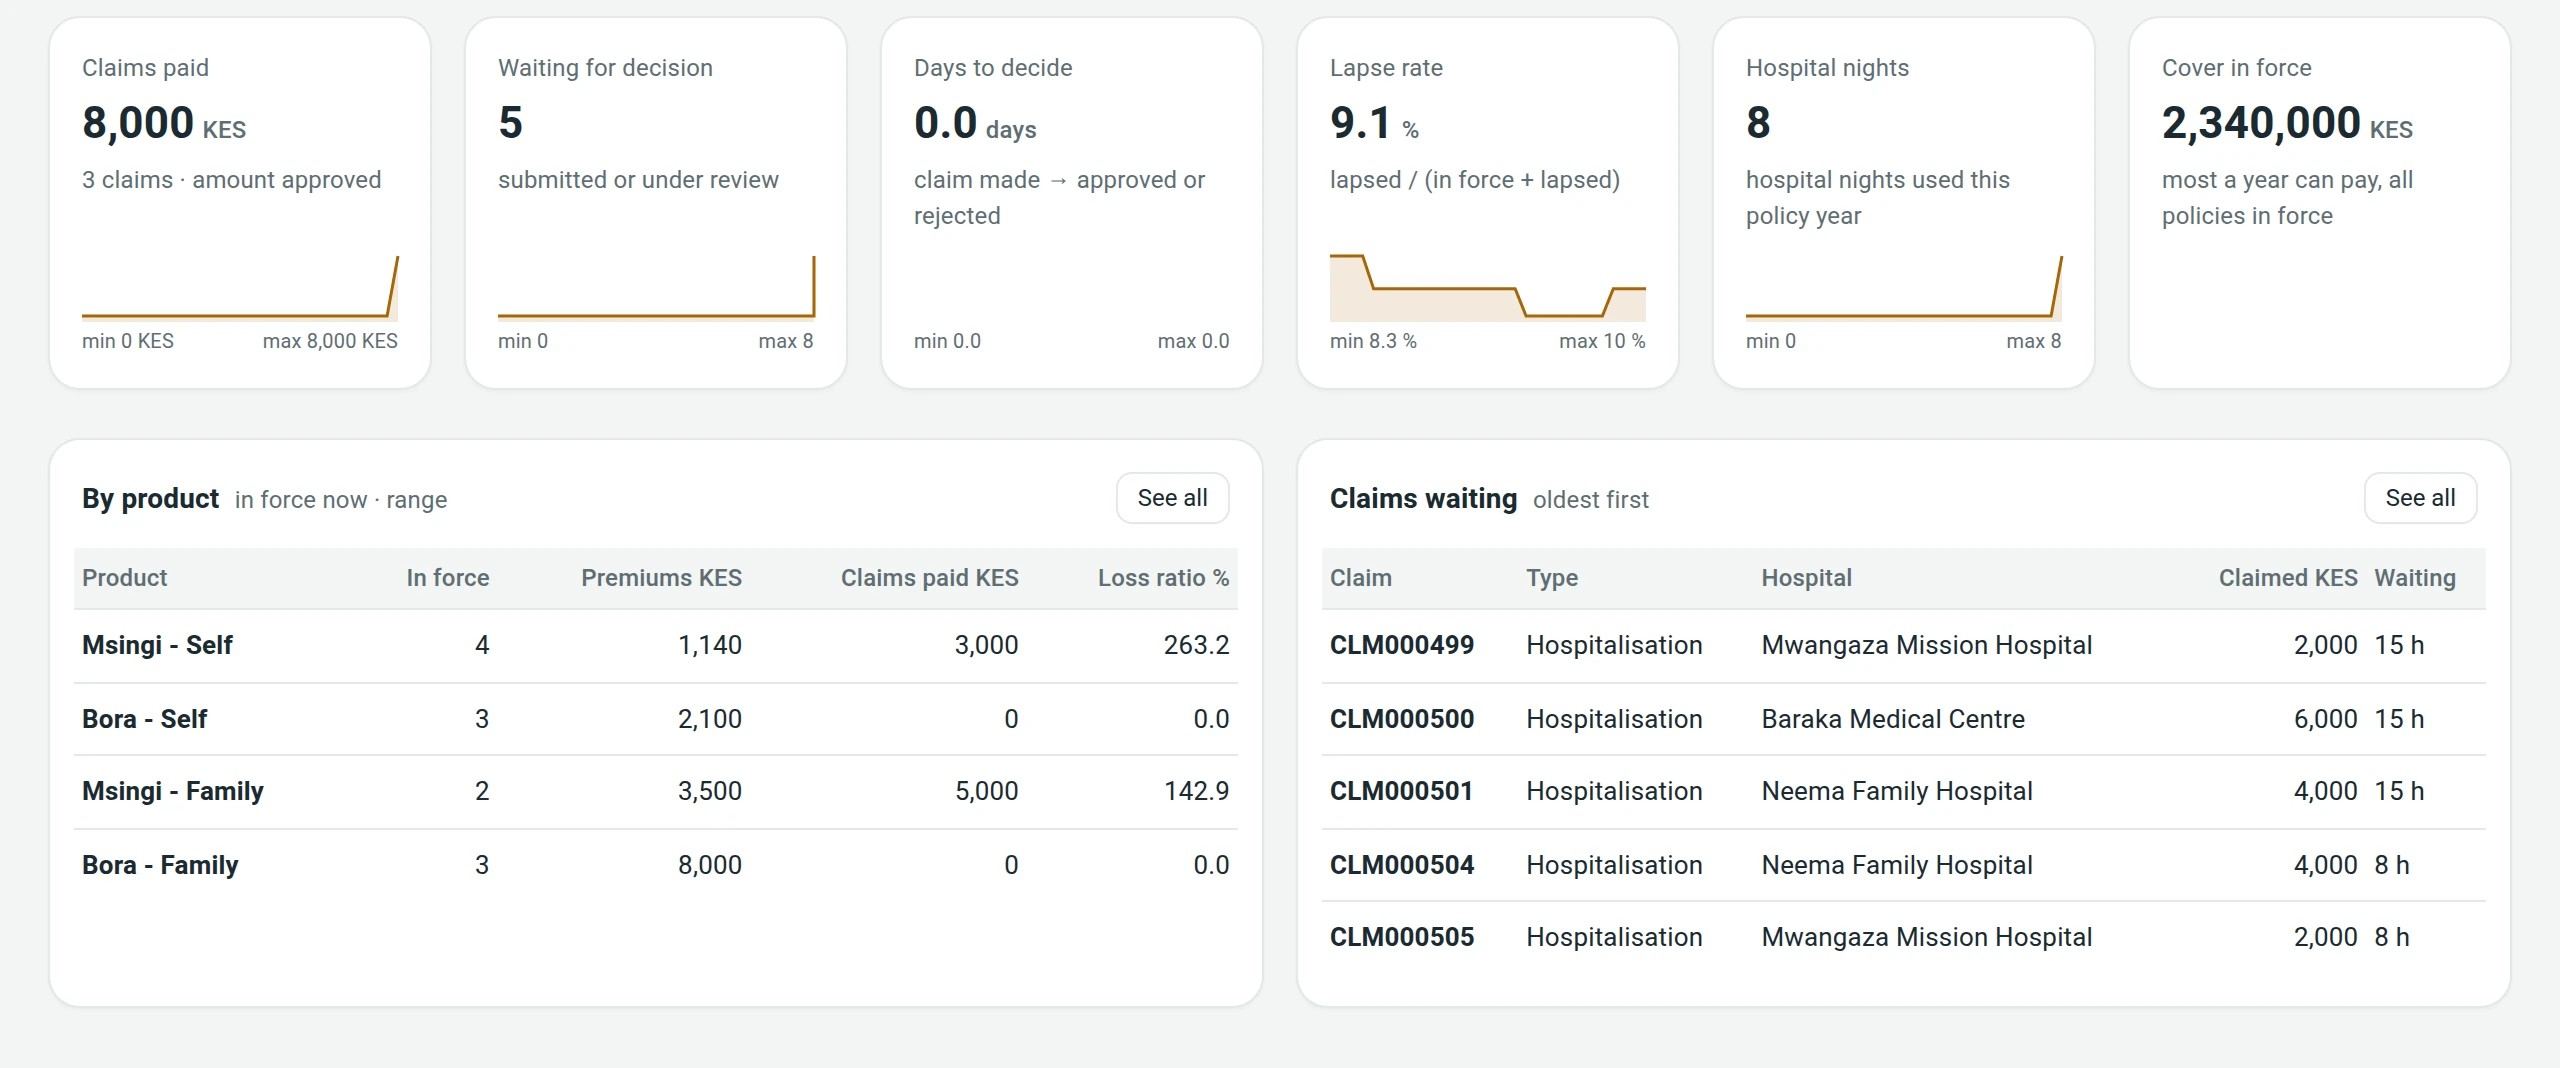
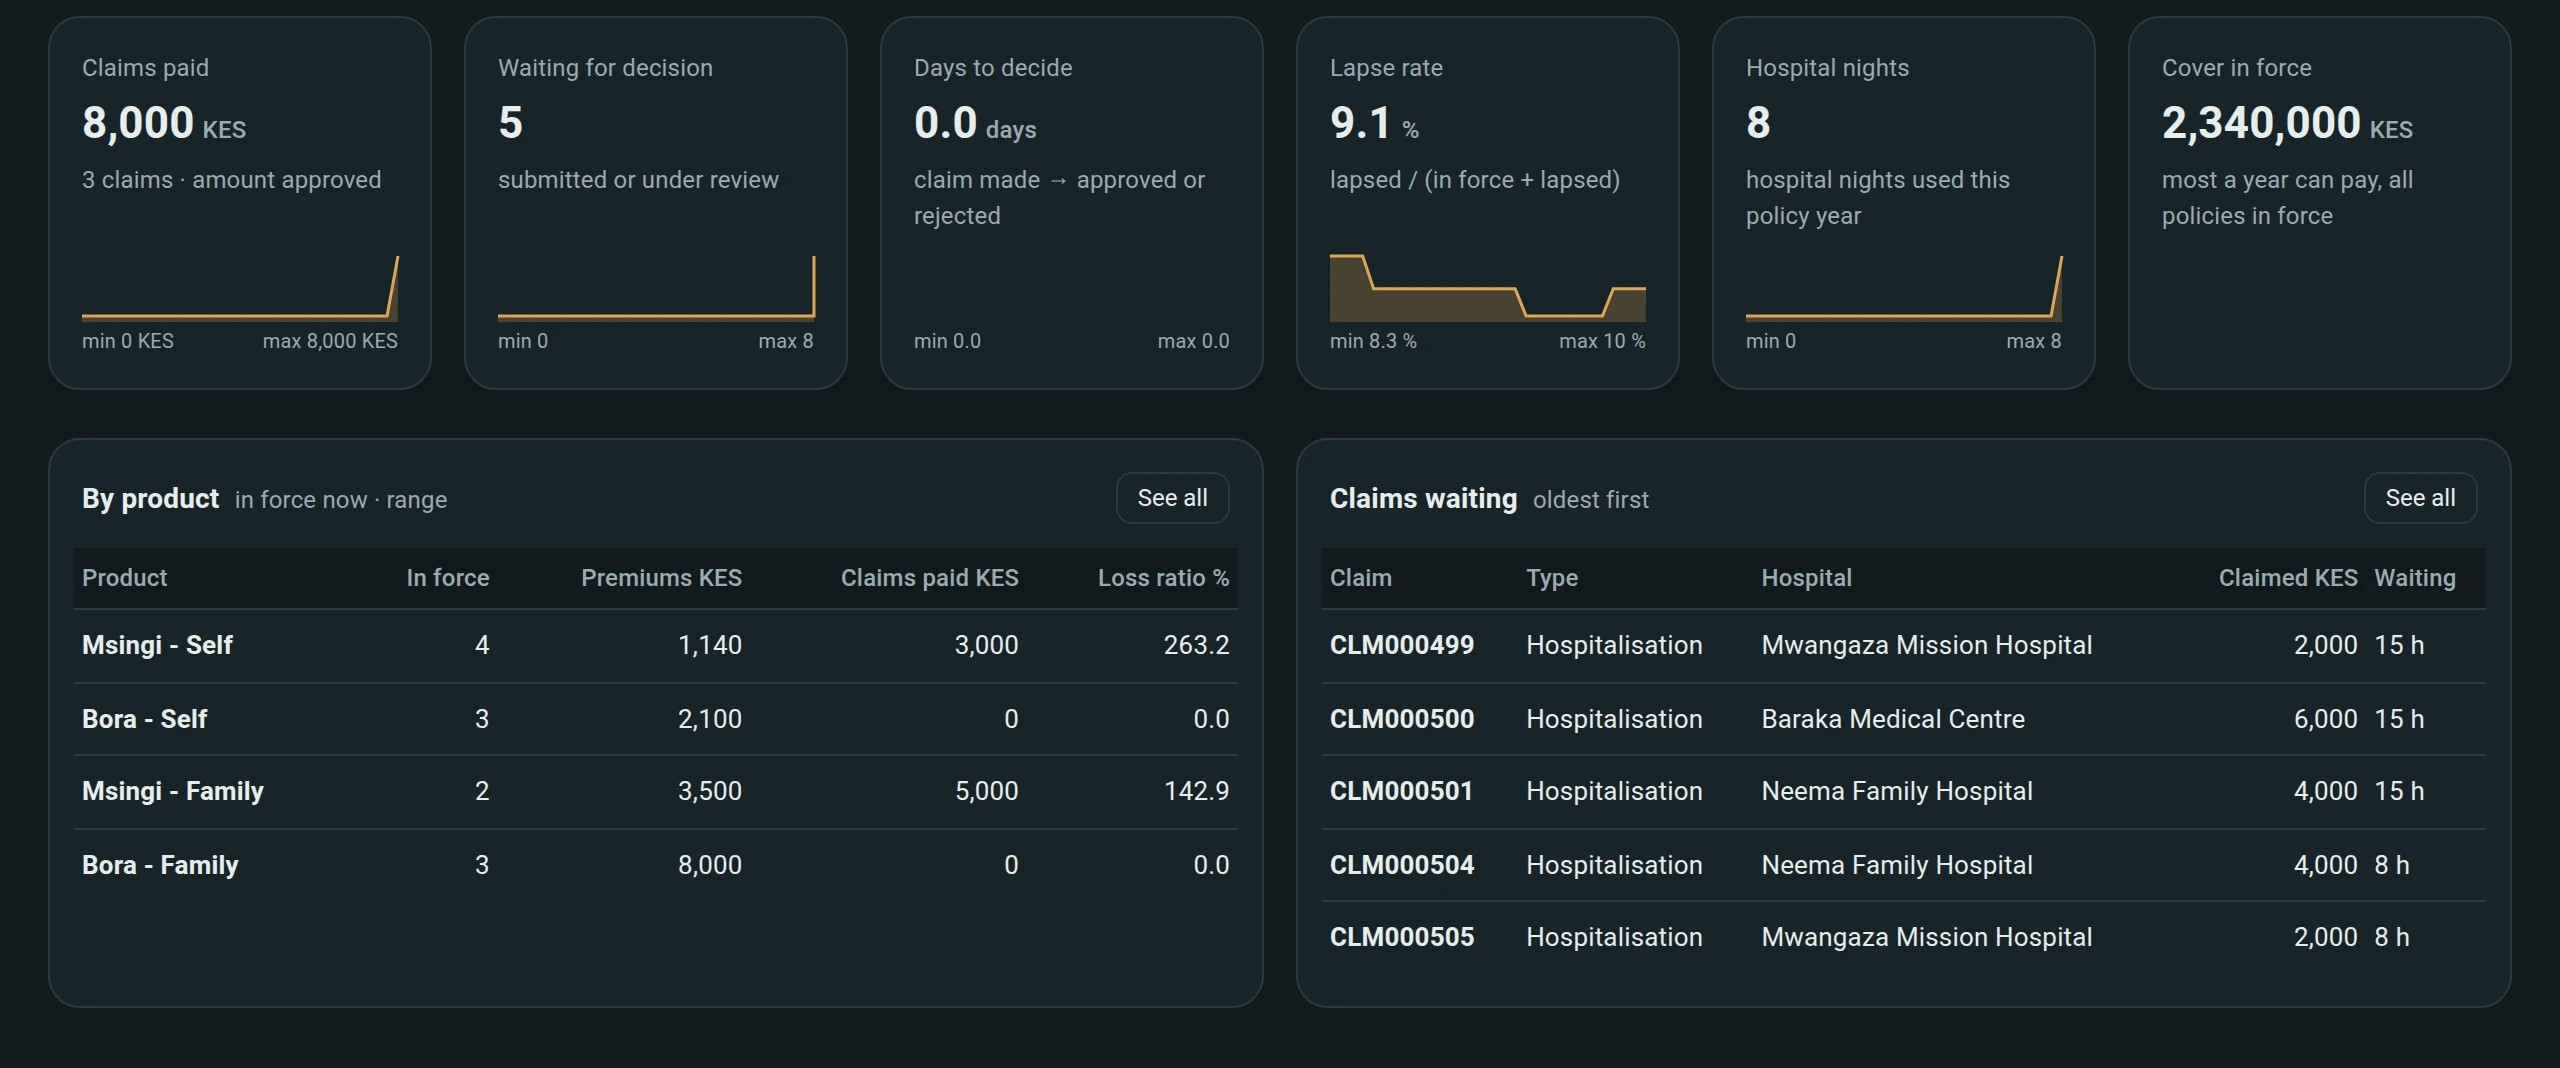
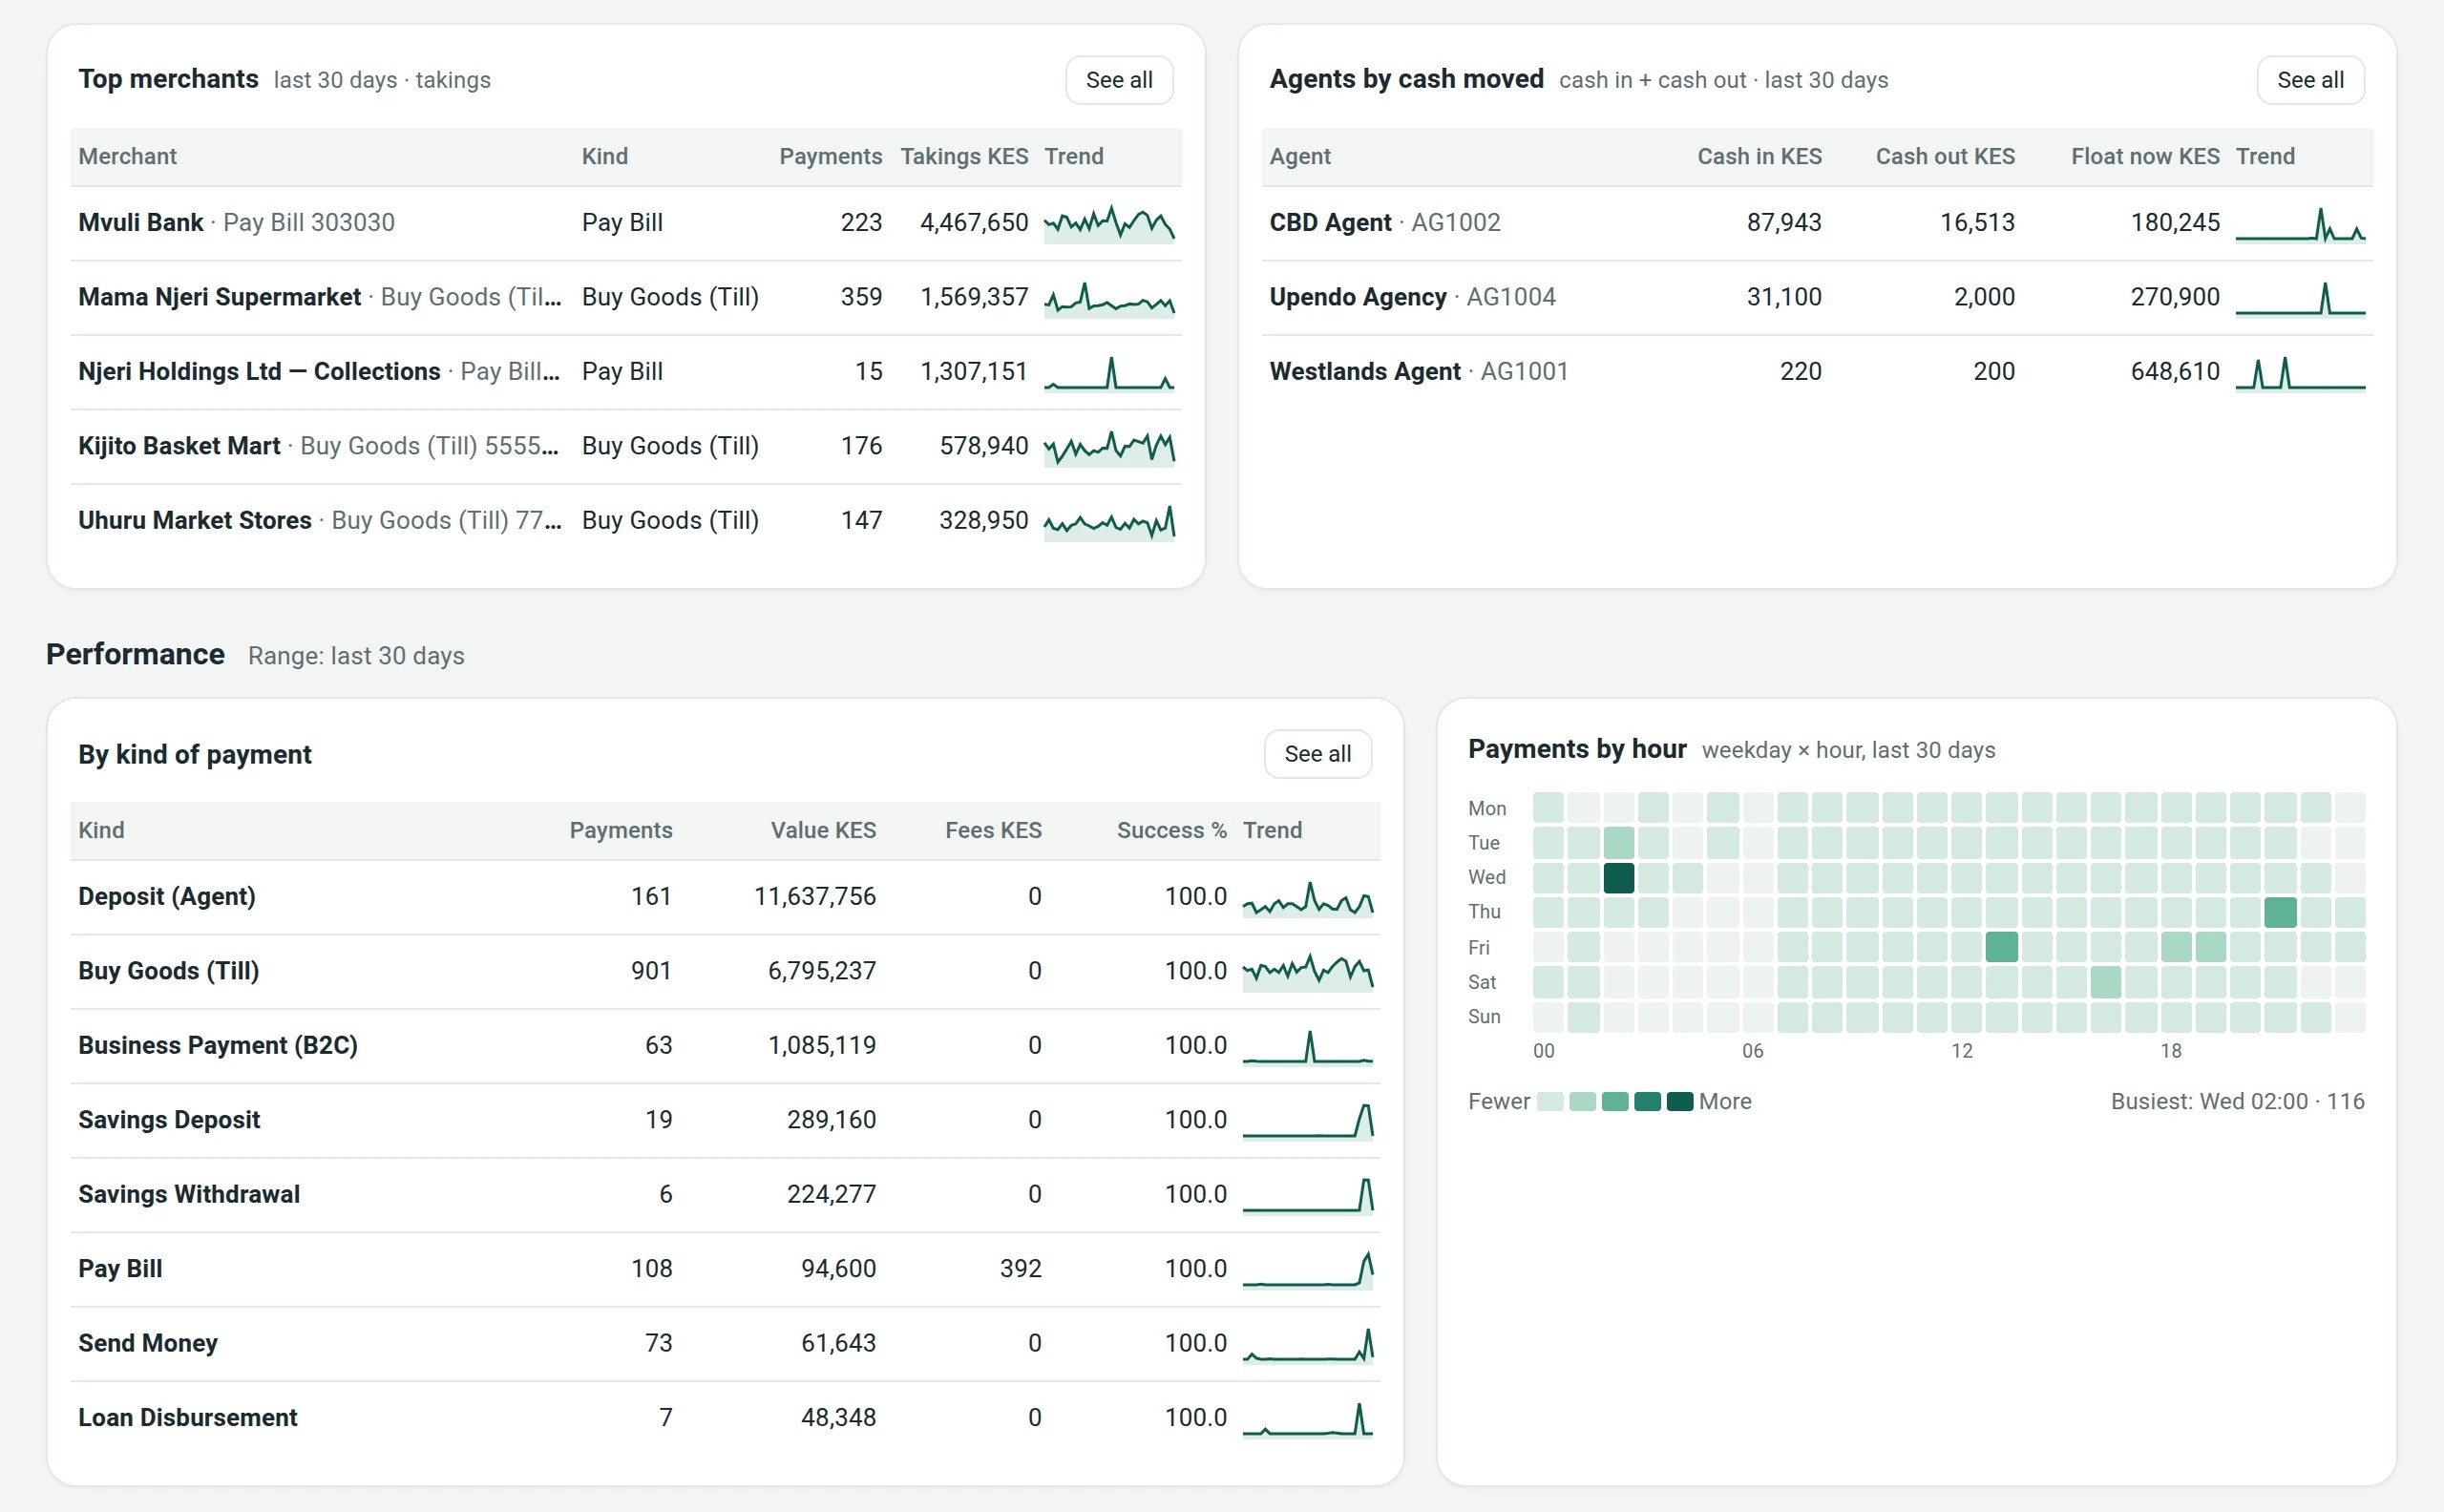
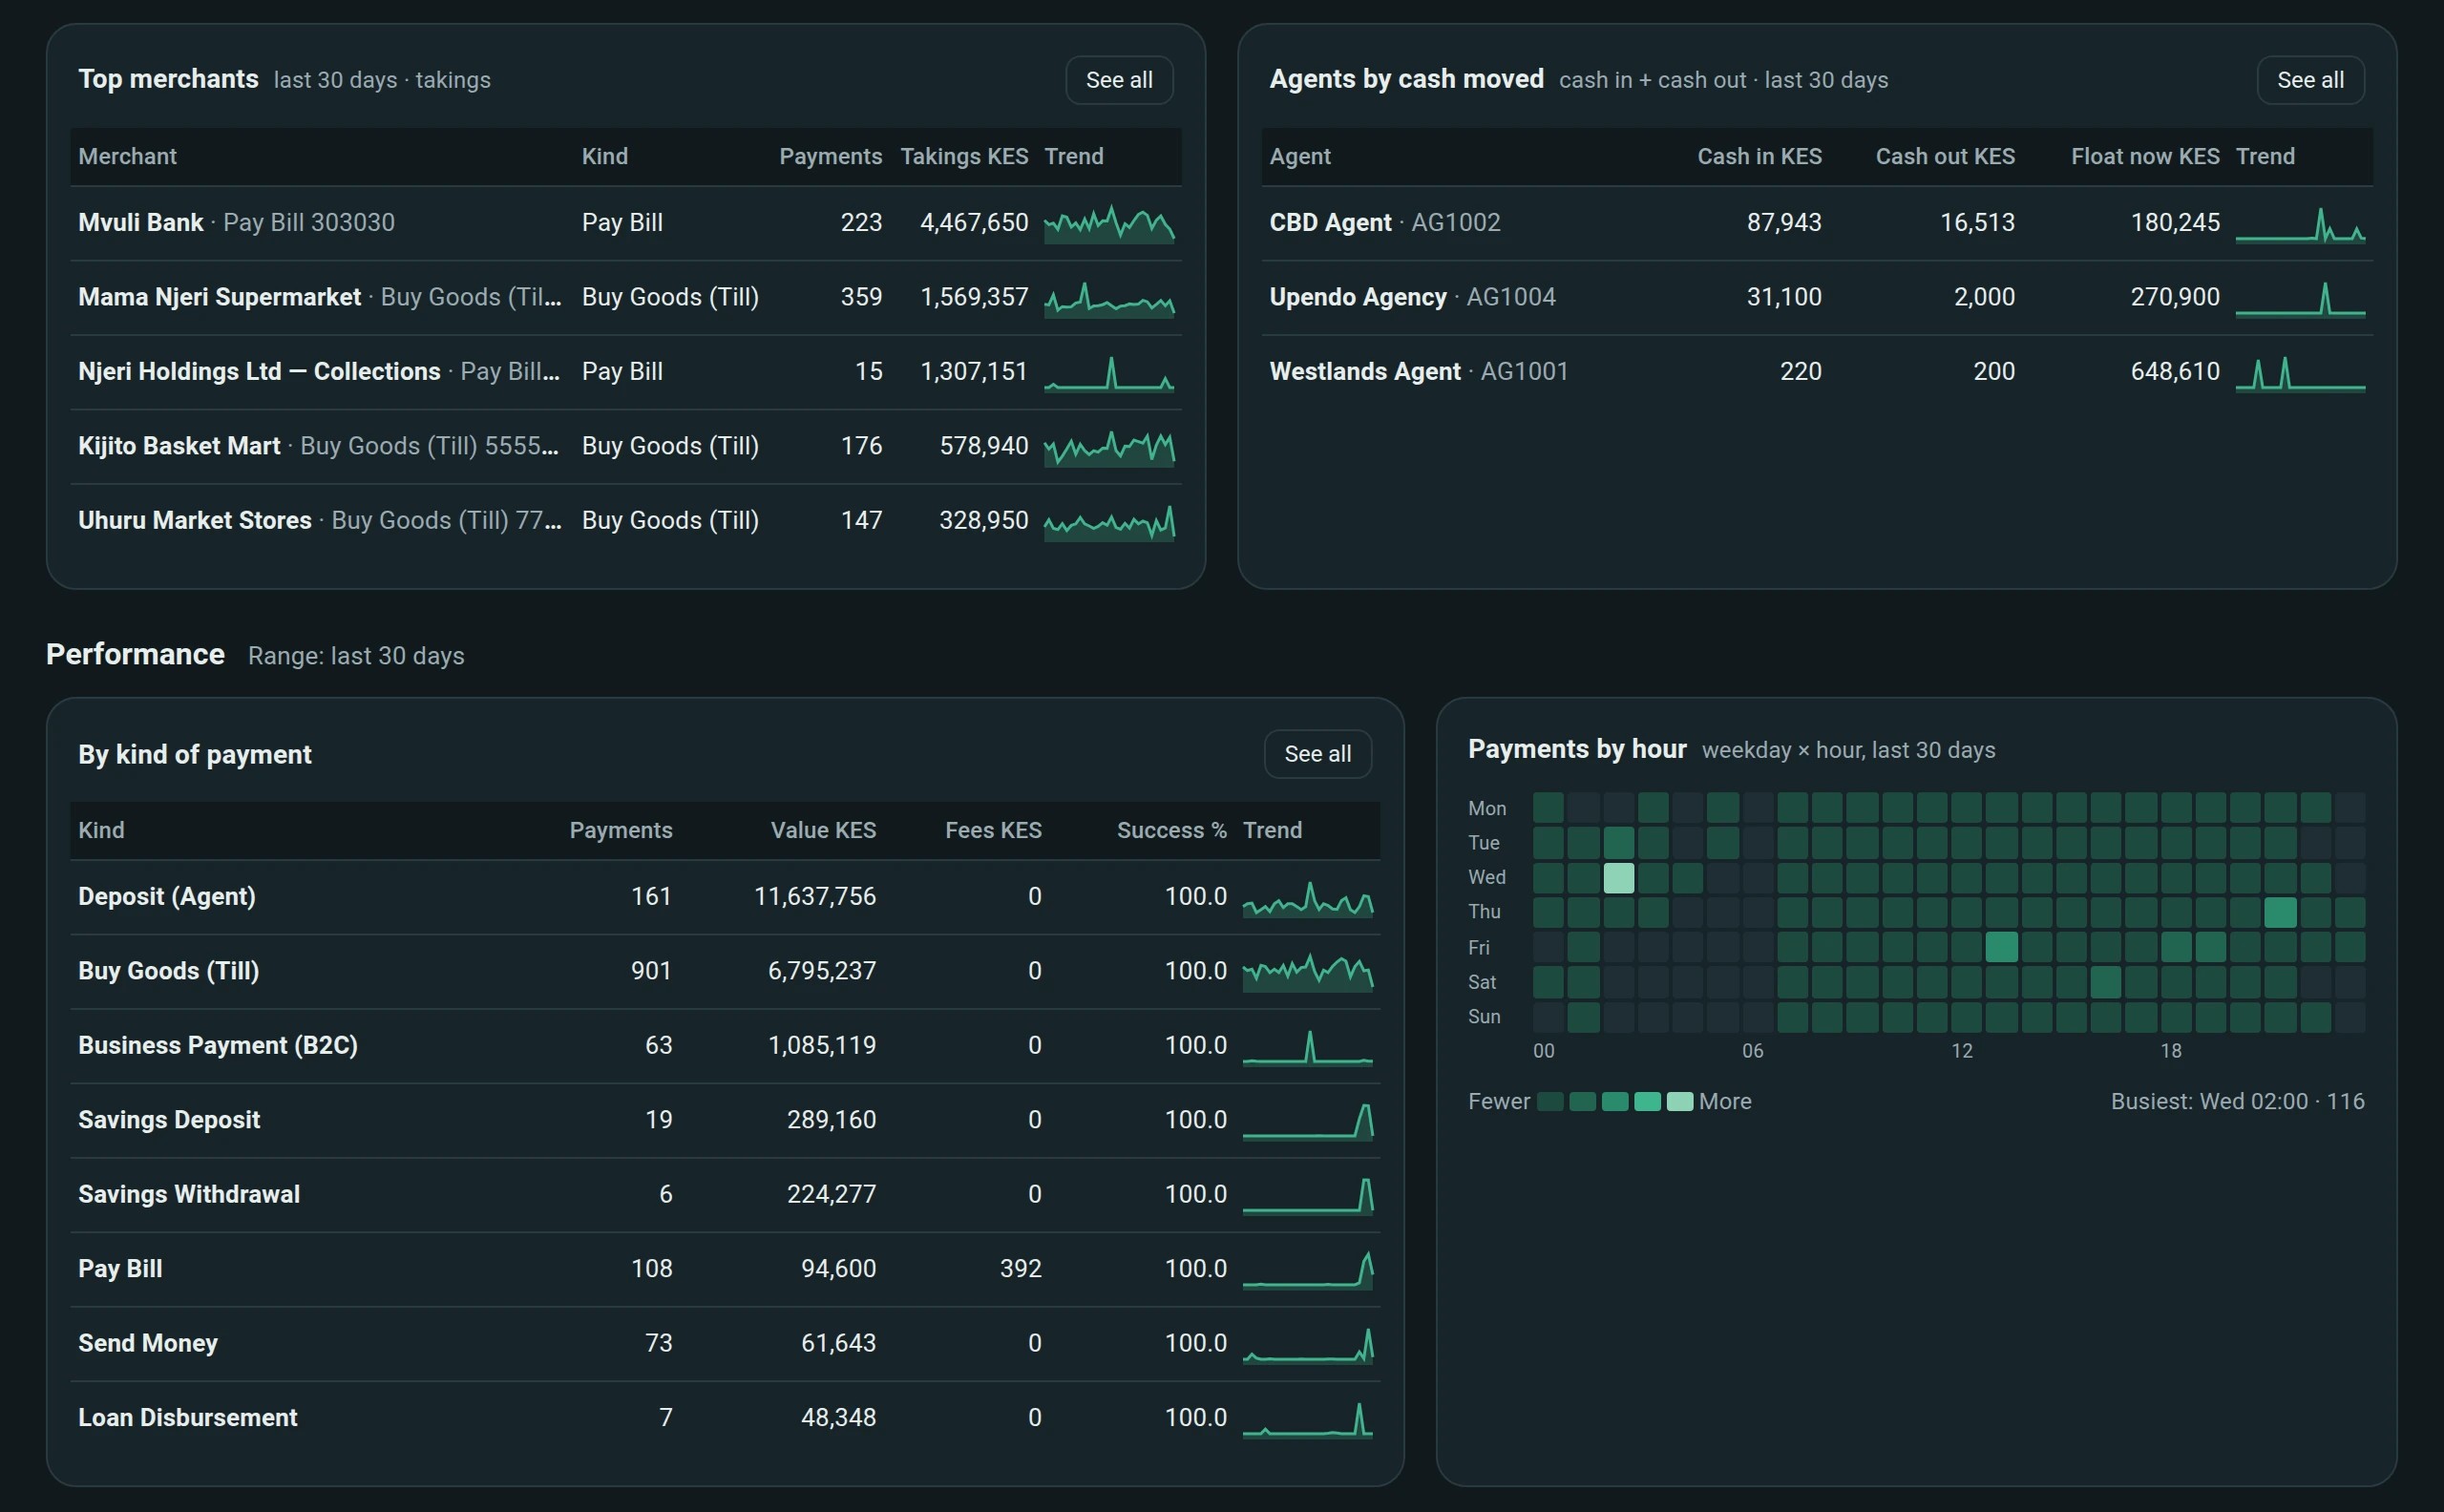
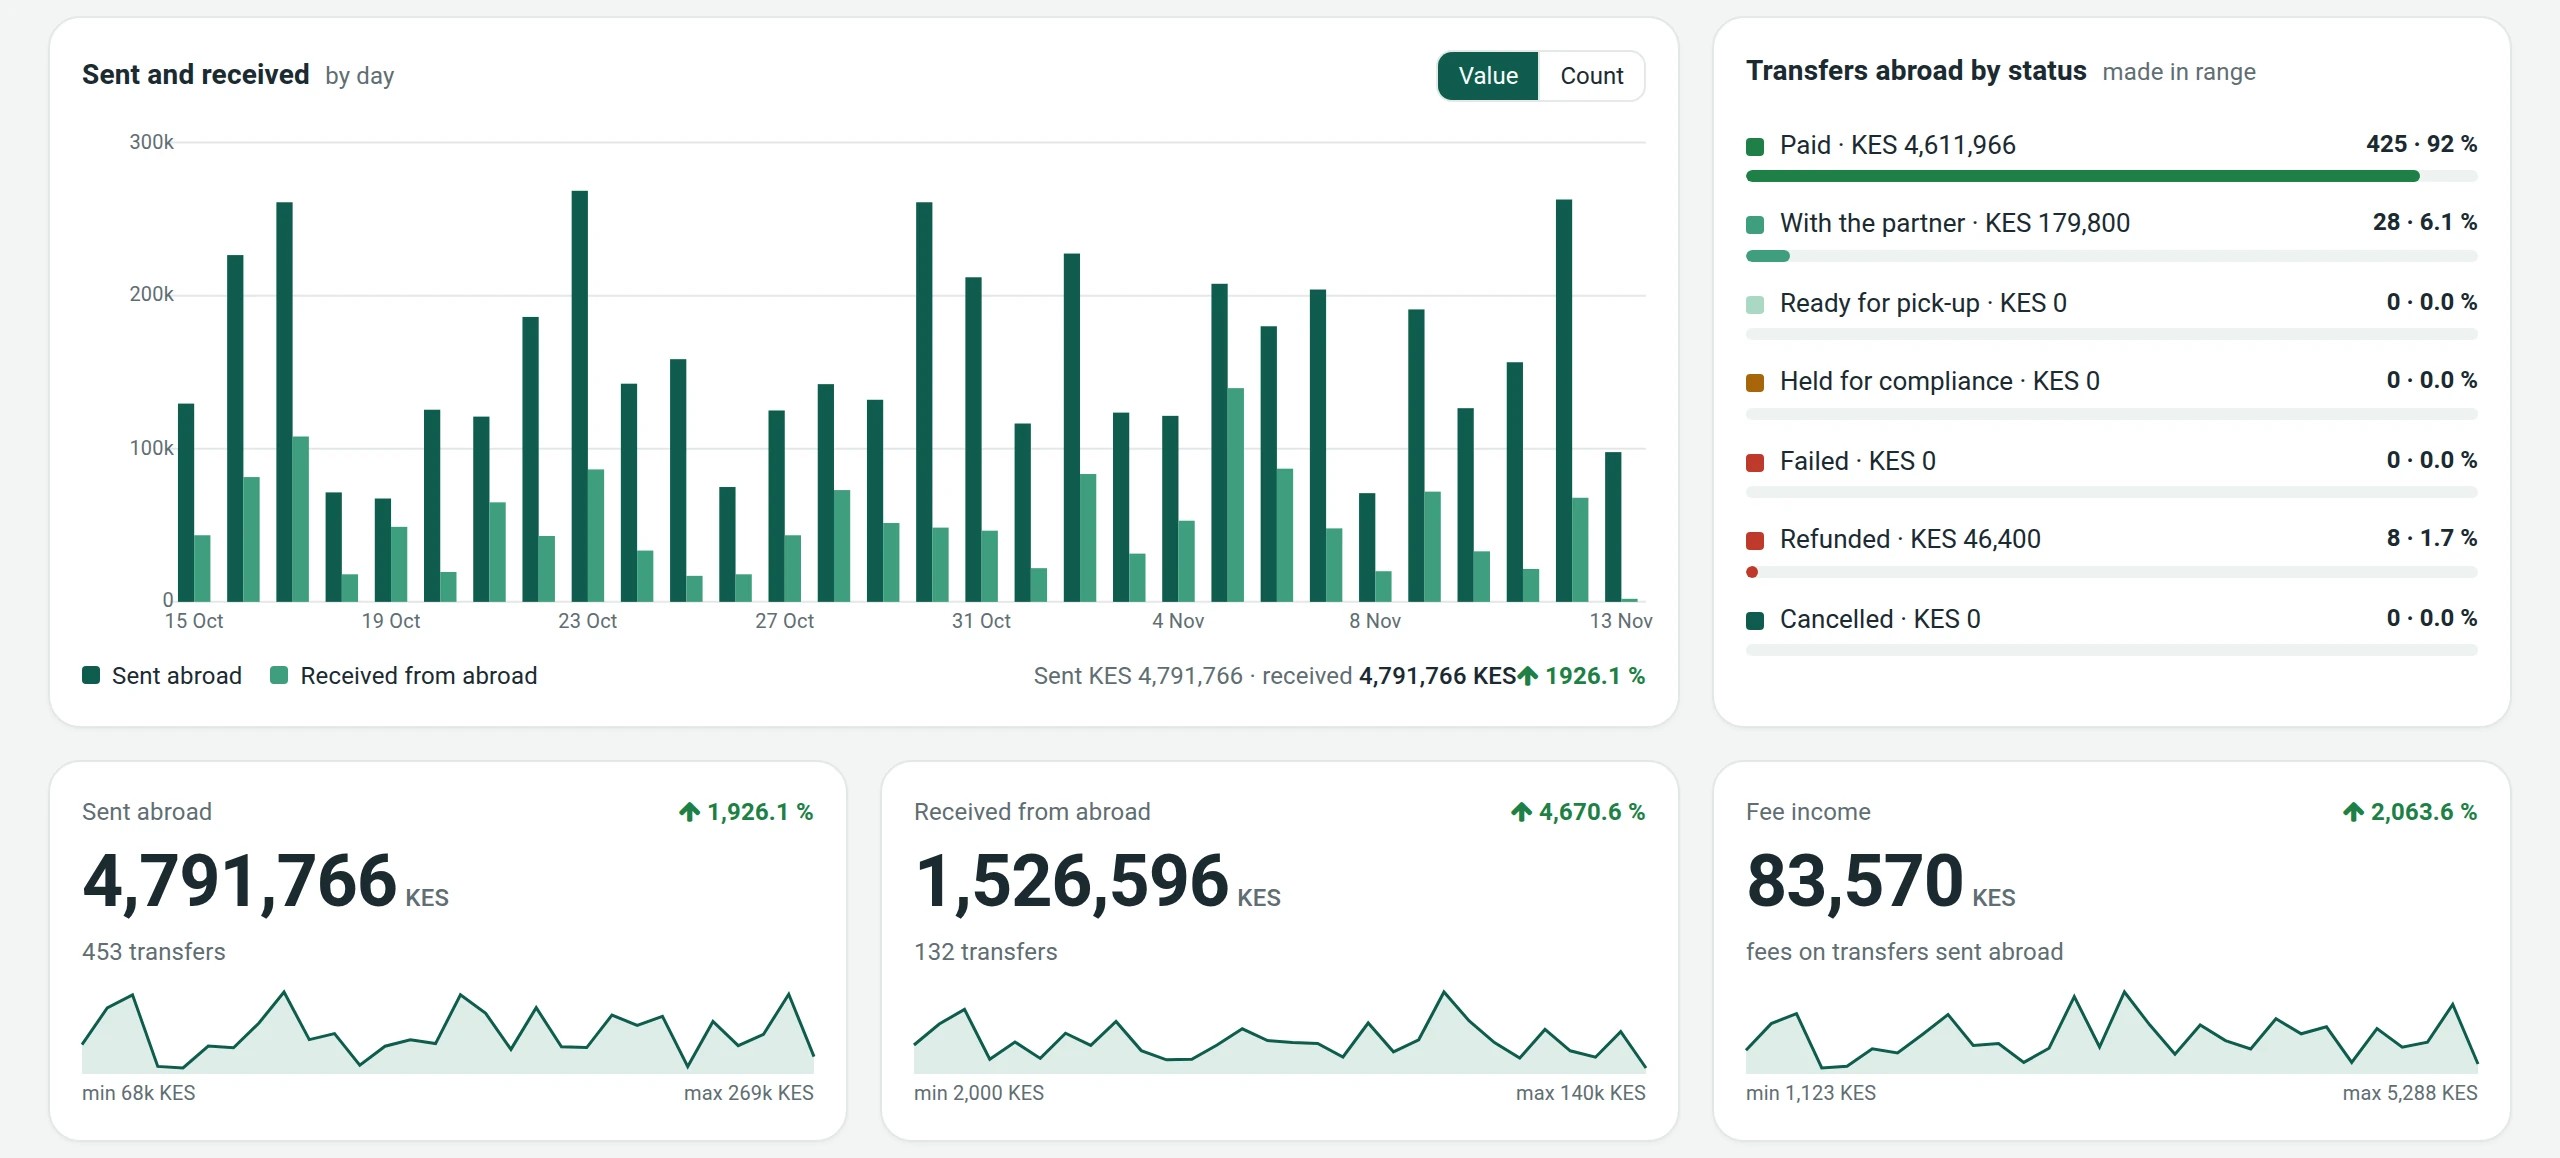
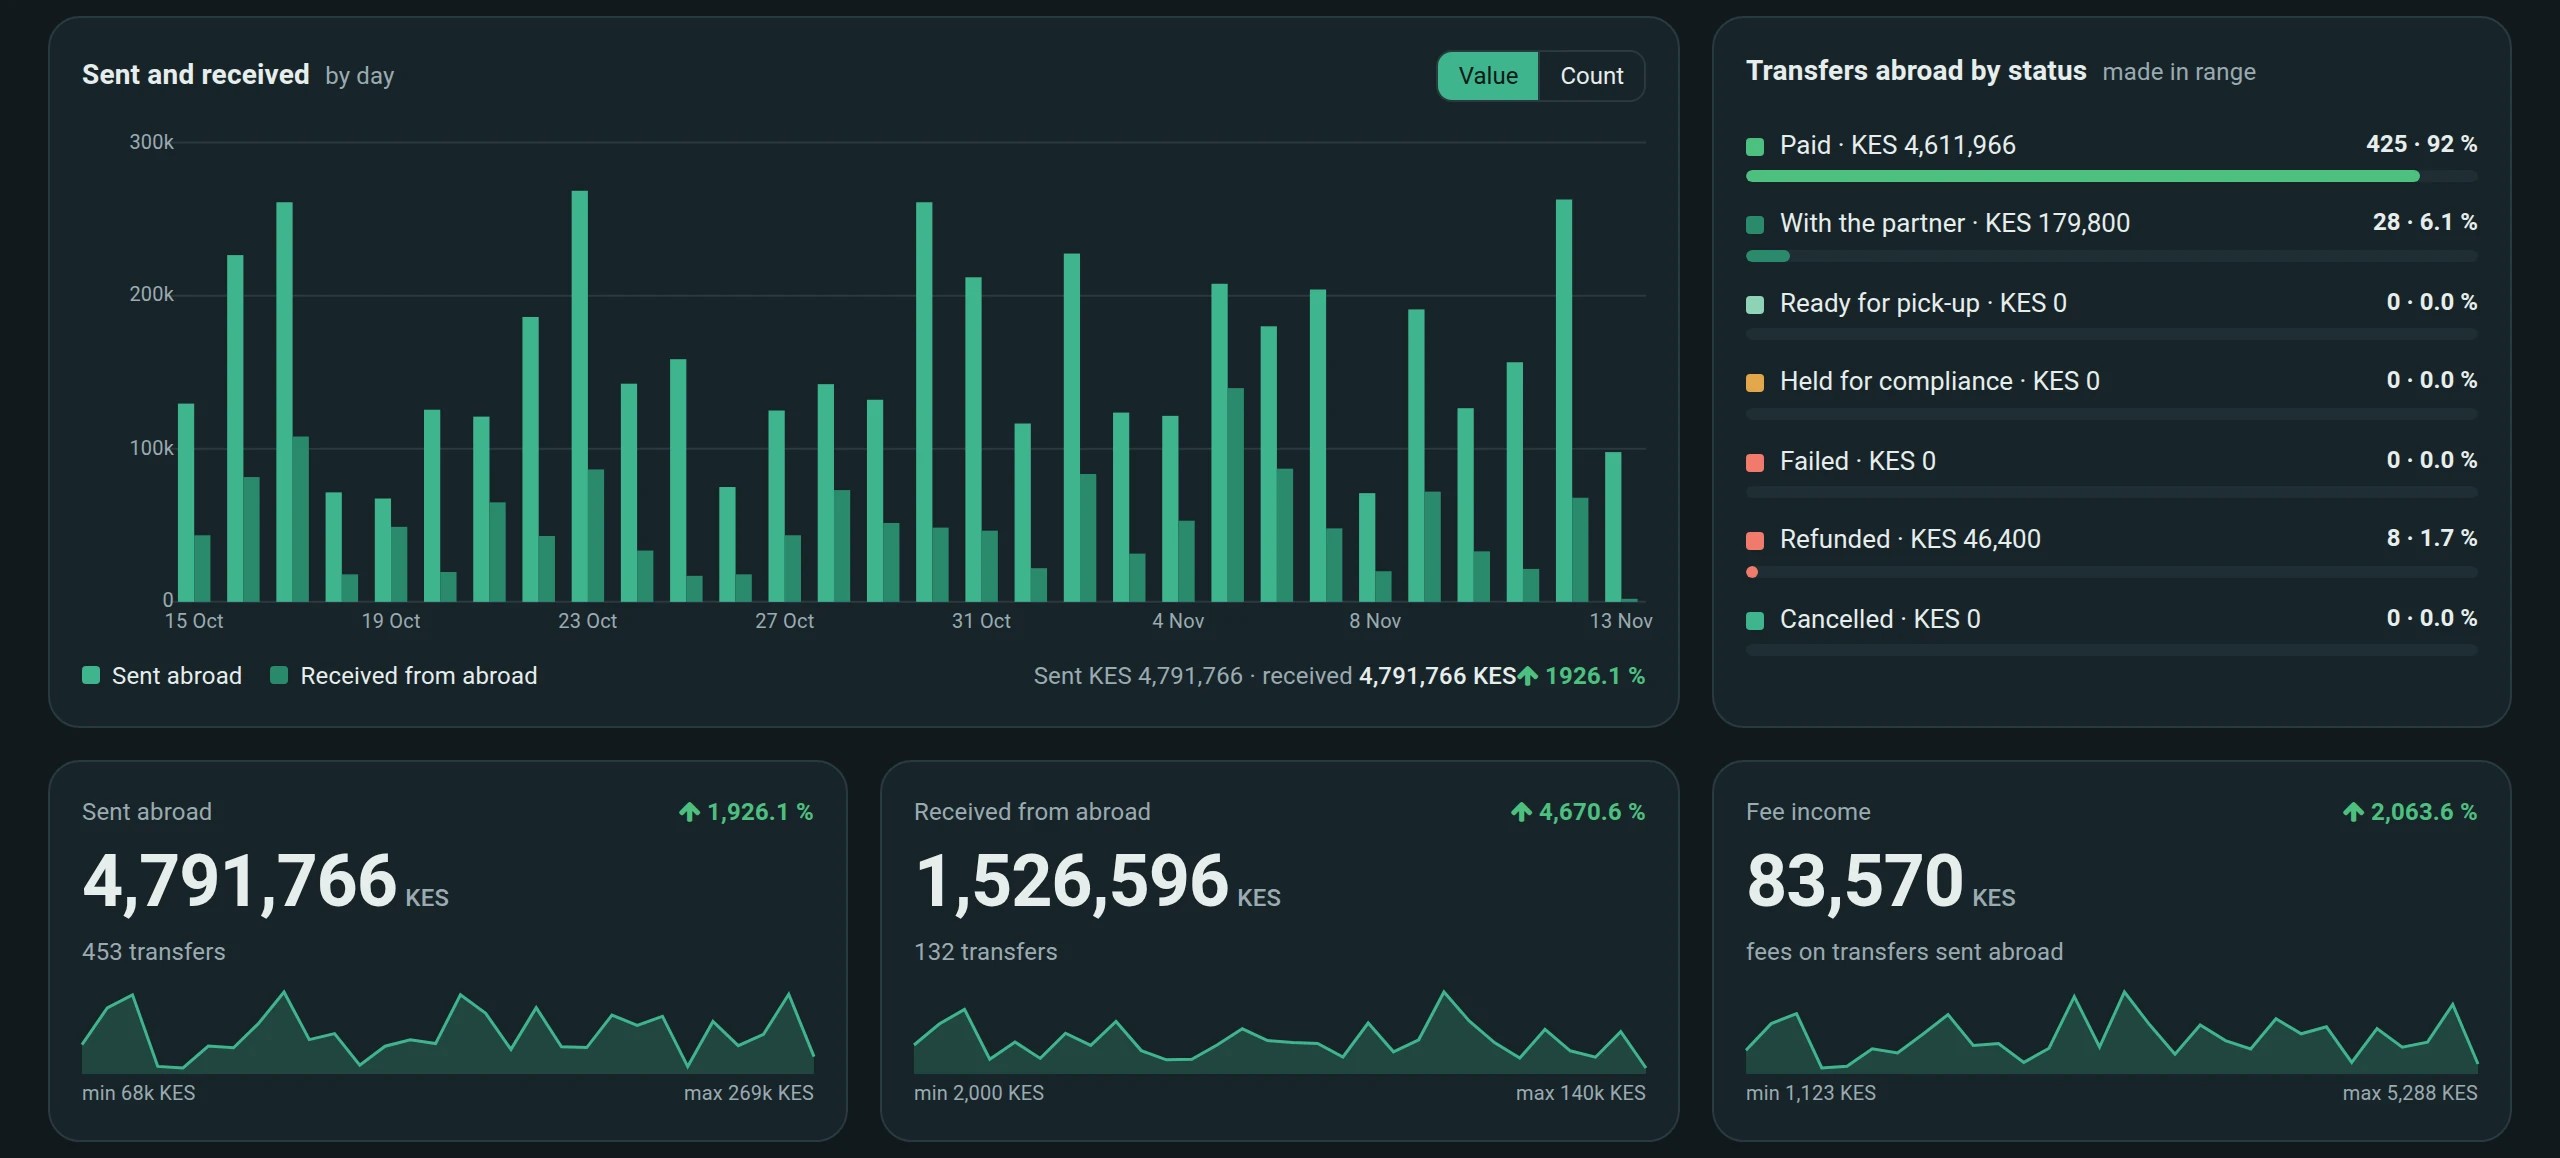
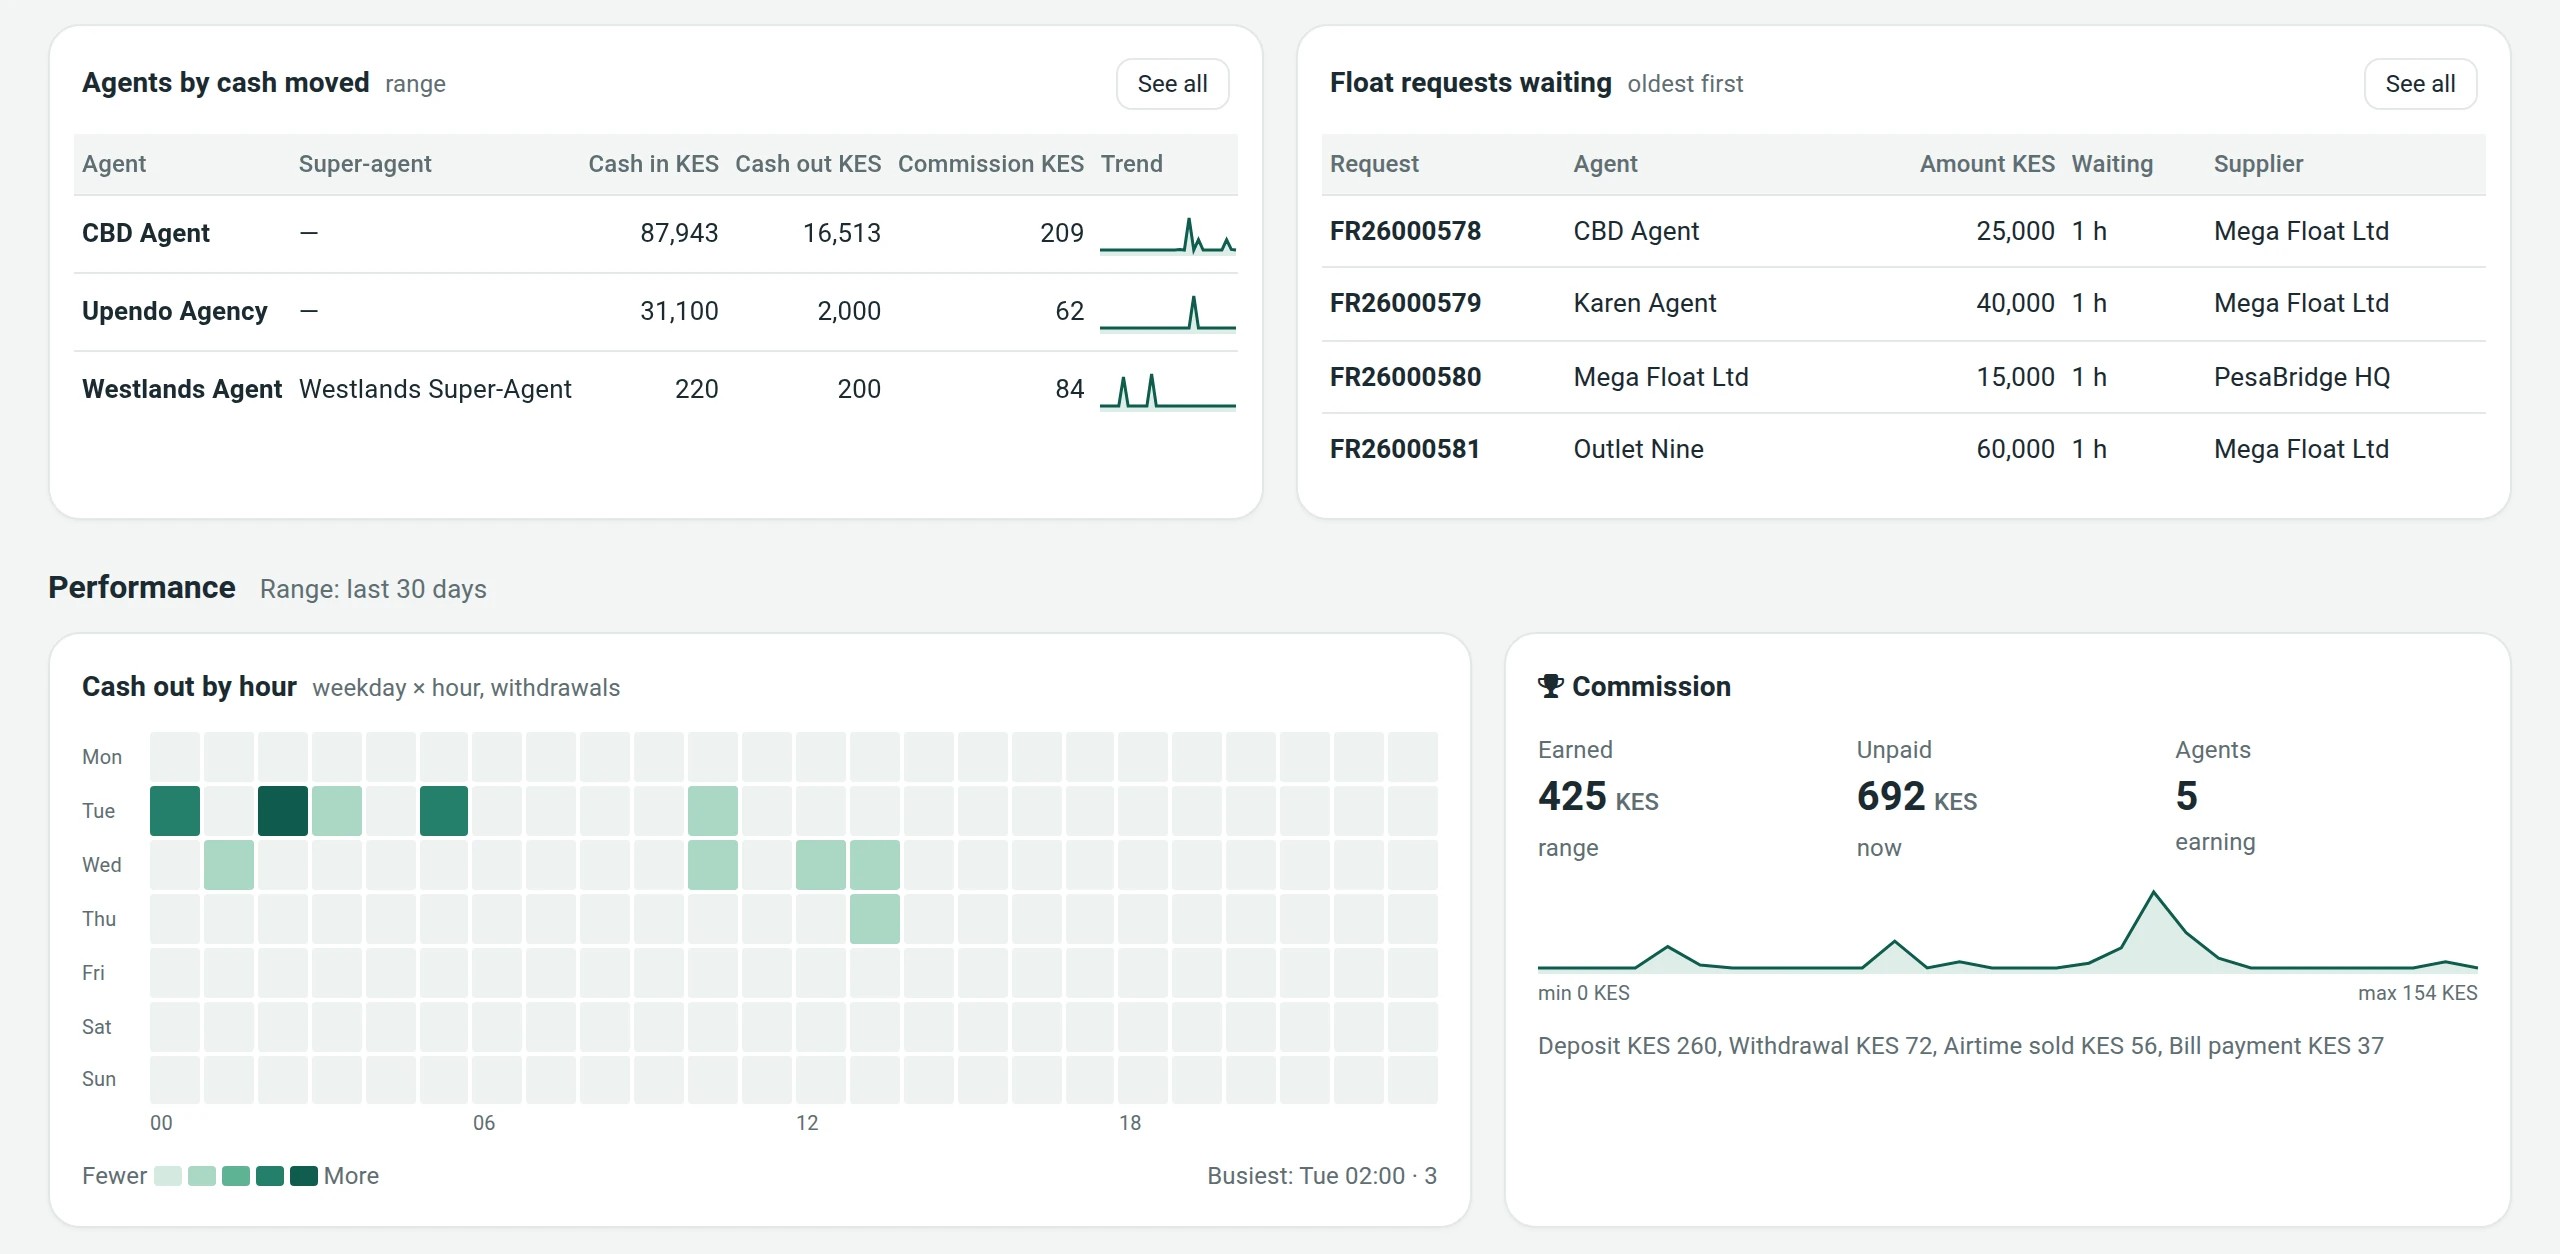
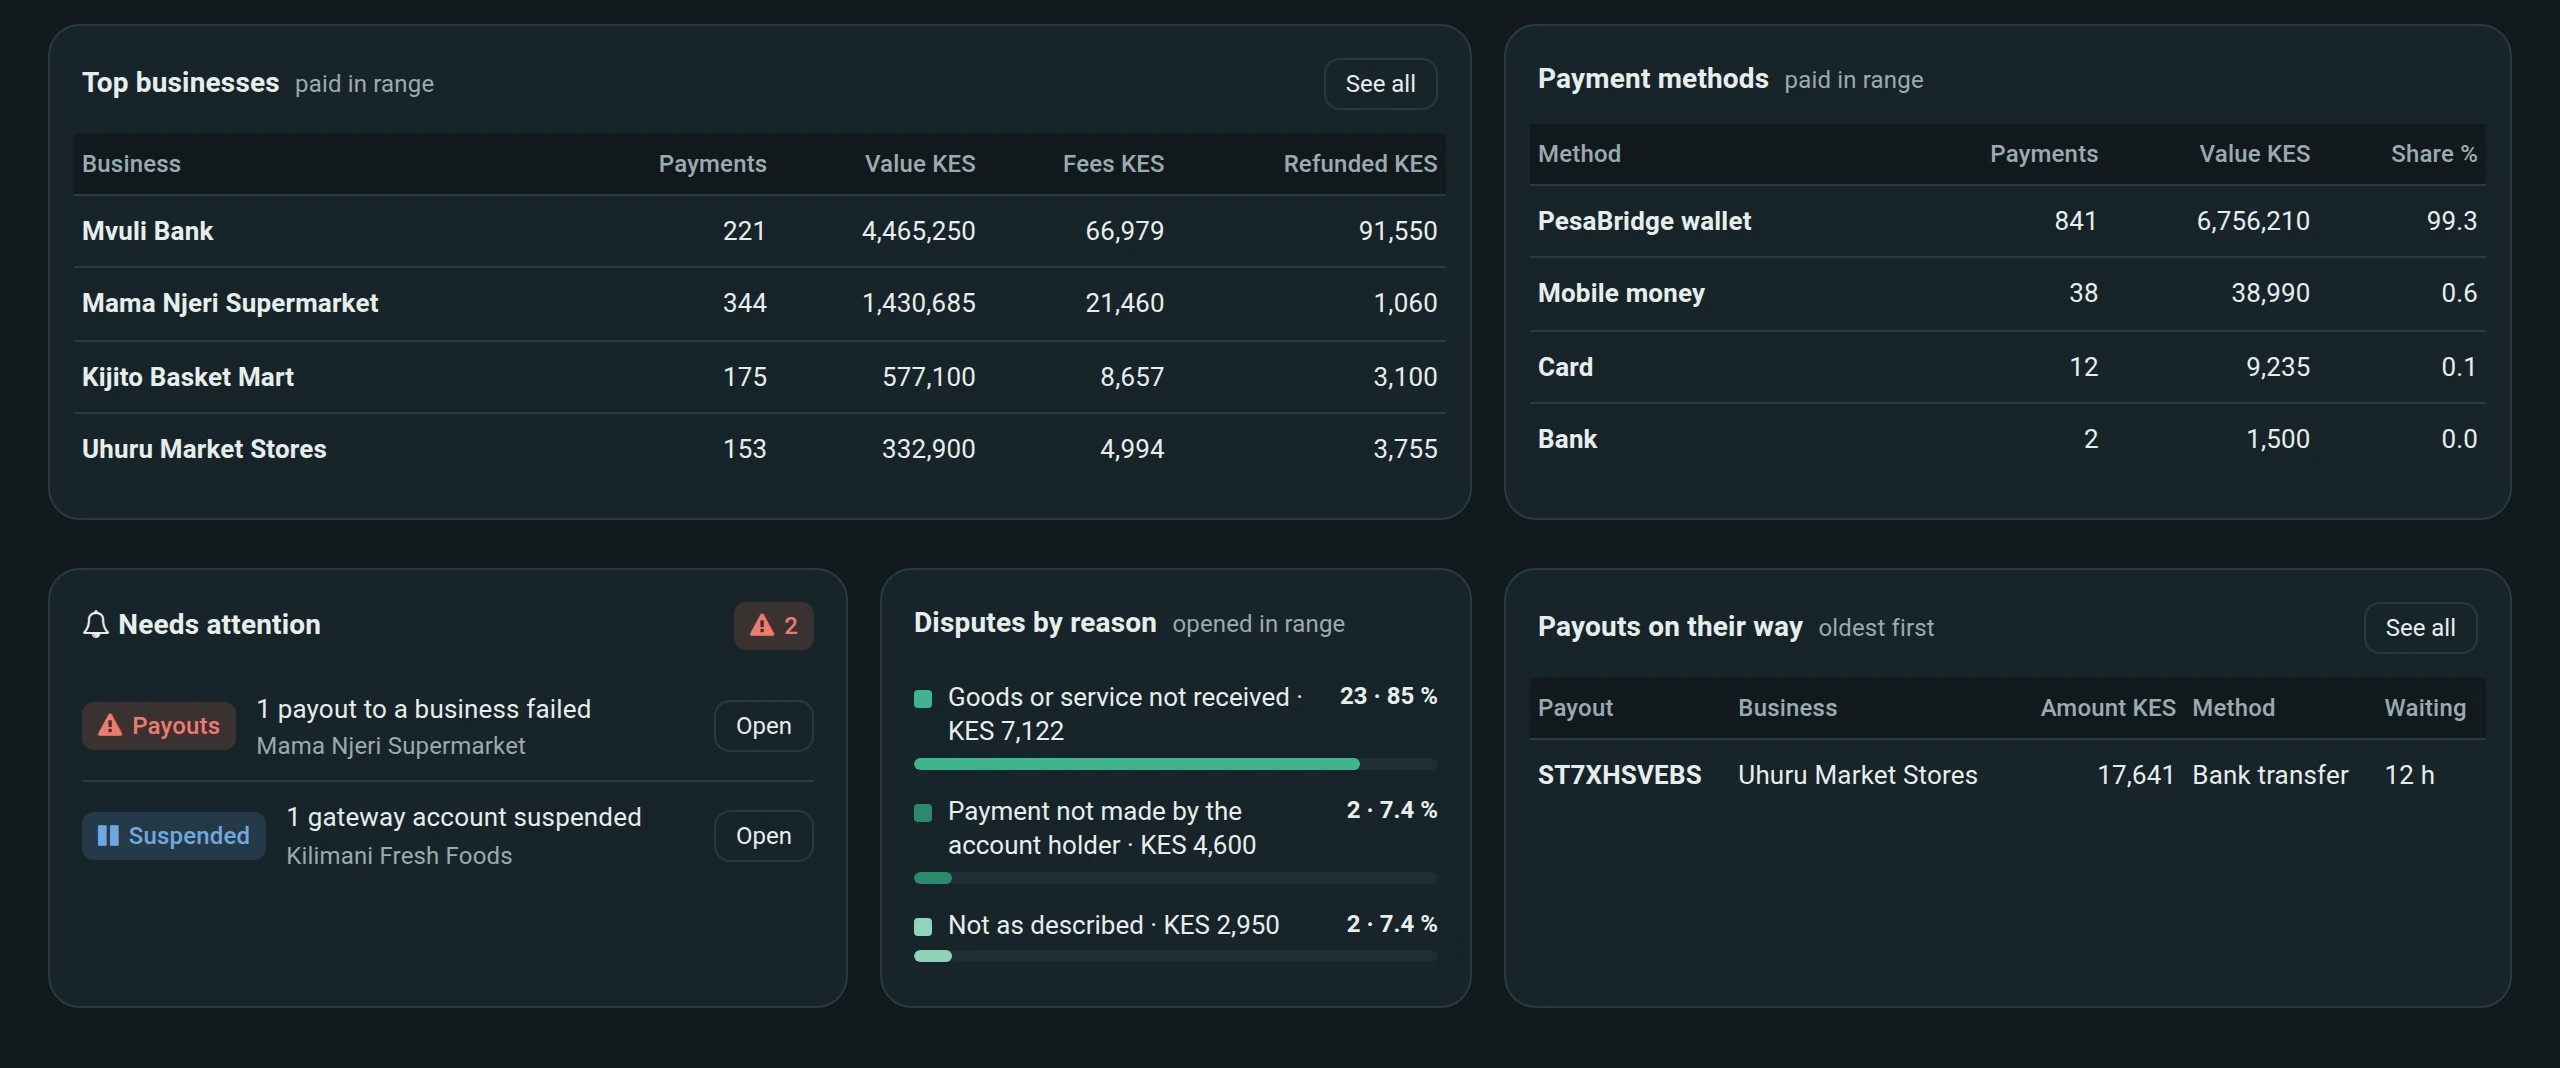
Swipe to see the whole dashboard
Integrations
Connected to the money rails your market uses
Each connection is an adapter. 16 have ready-made code today, and the others in the catalogue run on the sandbox until you need them. You switch on only what your market uses.
Mobile money
Collections, top-ups and cash-outs on the main mobile money networks, with hold, send once, confirm and refund.
Banks
Virtual account numbers for paying in, bank funding for corporate accounts and settlement to bank accounts.
Cards
Card payments through the payment providers you choose, on the hosted page, payment links and saved cards.
Remittance and identity
Payout partners for money sent abroad, an identity connector for KYC, and SMS providers for codes and alerts.
How you launch
From first demo to live, step by step
You test the real platform before you sign, then we set it up in your name and connect it to your market.
Step 1
Try it live
Open the live demo apps and portals, or book a walk-through with our team.
Step 2
Set your brand and country
Name, logo, colours, currency, languages and KYC tiers.
Step 3
Connect your rails
Mobile money, banks, cards and partners, only what you need.
Step 4
Go live
Your Android and iOS apps in the stores, your USSD shortcode and your web portals.
Countries you can launch in
Native apps, one platform
Channels — App · USSD · Web · API
Double-entry, always balanced
For developers
Collect & disburse with a few calls.
Self-serve keys, a sandbox, and a prompt-to-pay flow: push a charge, the customer confirms in their wallet, you get a signed webhook.
- OAuth2 client-credentials, sandbox + production keys
- Prompt-to-pay (STK push) + status polling
- Signed, retried webhooks (HMAC-SHA256)
- Balance & transaction queries
# 1. Exchange your key pair for a 1-hour token
curl -s https://pesa-bridge.com/api/bridgepay/v1/oauth/token \
  -H "Content-Type: application/json" \
  -d '{"client_id":"pk_test_…","client_secret":"sk_test_…"}'

# 2. Push a payment prompt to the customer's phone
curl -s https://pesa-bridge.com/api/bridgepay/v1/partner/stk \
  -H "Authorization: Bearer $TOKEN" \
  -H "Content-Type: application/json" \
  -d '{"payer_msisdn":"254708374149","amount":250,
       "reference":"INV-1001","idem":"inv-1001-1"}'← 200  {"charge_ref":"STK0000123","state":"pending"}→ webhook  charge.completed  KES 250.00  ok
FAQ
Questions, answered.
Buying PesaBridge
Can we start with part of the platform?
Yes. The Starter plan covers the customer and agent apps with the back office and KYC. Merchants, the developer API, USSD, lending, savings and bulk payments switch on later on the same ledger, so nothing is rebuilt as you grow.
How is PesaBridge priced?
Four ways: the Starter, Growth and Enterprise plans, or a Partnership in which you pay no licence fee and we share net revenue instead. The proposal builder on this site gives your exact price and a draft contract in about 10 minutes.
What do you need from us to launch?
A licence, or a licensed partner that holds the customer funds; accounts with the banks and payment providers you want to connect; your brand; and your tariffs. Once the provider credentials arrive, a first country usually goes live in 4 to 12 weeks.
Can we try it before we sign?
Yes. Request test access and you receive the Android apps for the products you pick, the web portals and test logins by email. Everything runs in a sandbox, so no real money moves. Developers can open a sandbox account on the developer portal at any time.
What support and training do you provide?
Every plan includes support: email on Starter, priority support on Growth, and a service-level agreement with onboarding on Enterprise. During the launch we train your back-office, support and agent-network teams, and the help hub, guides and API docs stay online for everyone.
The platform
Is PesaBridge a platform I share, or my own?
Your own. PesaBridge is a product BridgeERP resells — every operator gets their own deployment, branded and configured for them. No shared database, no shared super-admin.
Which countries and currencies are supported?
Any. Country, currency, language and KYC rules are configuration drawn from the full ISO set — not hardcoded. We have live markets today and stand up new ones without a rewrite.
Does it work on feature phones?
Yes. Over USSD, customers send, withdraw, pay bills, buy goods, buy airtime, check their balance and get a mini statement, settling on the same ledger as the apps.
Can I connect my own banks and payment rails?
Yes. Rails are pluggable adapters — banks, mobile money, cards and PSPs — so you connect only what your market needs.
How fast can we go live?
Weeks, not years. Configure your brand and country, wire your rails, then ship your apps, USSD code and web portals from one platform.
Is it secure and auditable?
Every movement is double-entry and balanced to zero, PIN- and KYC-gated, with signed webhooks and a full audit trail for regulators.
Which apps do operators and their customers get?
Six native Android and iOS apps: a User app for customers, a Send app for transfers abroad, an Agent / Super-agent app for cash-in, cash-out and float, a Merchant app to accept and settle, a Counter app for shop tills, and a Corporate app for bulk payouts with maker-checker approvals, which also runs as a web portal.
How does settlement and reconciliation work?
Funds settle to the relevant wallet in real time. Every transaction produces balanced ledger entries you can reconcile, with statements and exports, and a GL bridge for your accounting system.
Can it handle loans, savings and group finance?
Yes — overdraft credit, MFI loans with schedules and portfolio-at-risk, goal savings, and savings groups (chama / merry-go-round) are part of the platform and switch on per market.
Do you support bulk disbursement for payroll, aid or subsidies?
Yes. The Corporate portal and API run bulk disbursement to thousands of wallets with maker/checker approvals, payee books, scheduling and full reconciliation.
What does it take to run it day-to-day?
A single operator admin console runs brand, tariffs, KYC, the agent and merchant network, the ledger, reversals, support and KPIs — no code required for everyday operations.
Who owns the deployment and the data?
You do. Each operator runs their own deployment with their own database — branded and configured for them. It's a product you resell as your own, not a shared SaaS tenant.
Ready to launch your wallet?
Book a demo and we'll stand up your brand, country and rails — and walk you through the apps, admin and API.
Prefer to talk? Call +254 746 883809